
Kodiak Gas Services (KGS) Lands Data Center Power Deal, Is It Still 33% Undervalued?
Kodiak Gas Services (KGS) has agreed to supply 76 megawatts of behind the meter natural gas power for a West Texas data center over six years, with revenue expected from early 2027.
Recent trading has been choppy for Kodiak Gas Services, with the share price down 4.24% over the past day and 8.49% over the past month, while still showing a strong year-to-date share price return of 49.42% and a three-year total shareholder return of 268.76%, which points to longer term momentum.
Scan for other Kodiak Gas Services style infrastructure plays tied to power hungry data centers by reviewing our hand picked list of 88 AI infrastructure stocks in one place.
The recent pullback in Kodiak Gas Services after such a strong multi year run raises a simple tension: Are investors reassessing the business, or just resetting sentiment before the next look at valuation?
Most Popular Narrative: 33% Undervalued
Kodiak Gas Services last closed at $56.24, while the most followed narrative anchors fair value at $84.07 based on a 7.77% discount rate and long term cash flow assumptions. That gap frames the current pullback as a valuation question rather than just a chart pattern.
High fleet utilization (over 97%), increased contracting of new large horsepower units at premium rates, and the long-term, fee-based nature of Kodiak's contracts underpin resilient, recurring revenue and EBITDA stability, providing earnings visibility even across choppy commodity price environments. Greater outsourcing of compression by E&Ps, particularly amid customer efforts to free up capital via partnership and sale-leaseback structures, is set to expand Kodiak's addressable market and create incremental growth opportunities in future years, with direct upside to revenue-generating horsepower and potential operating leverage.
See why 4 investors see Kodiak Gas Services as 33% undervalued.
Result: Fair Value of $84.07 (UNDERVALUED)
Still, the Kodiak Gas Services story can be knocked off course if Permian activity cools, or if capital hungry data center power projects slip on timing or returns.
Find out about the key risks to this Kodiak Gas Services narrative.
Another View on Kodiak Gas Services Valuation
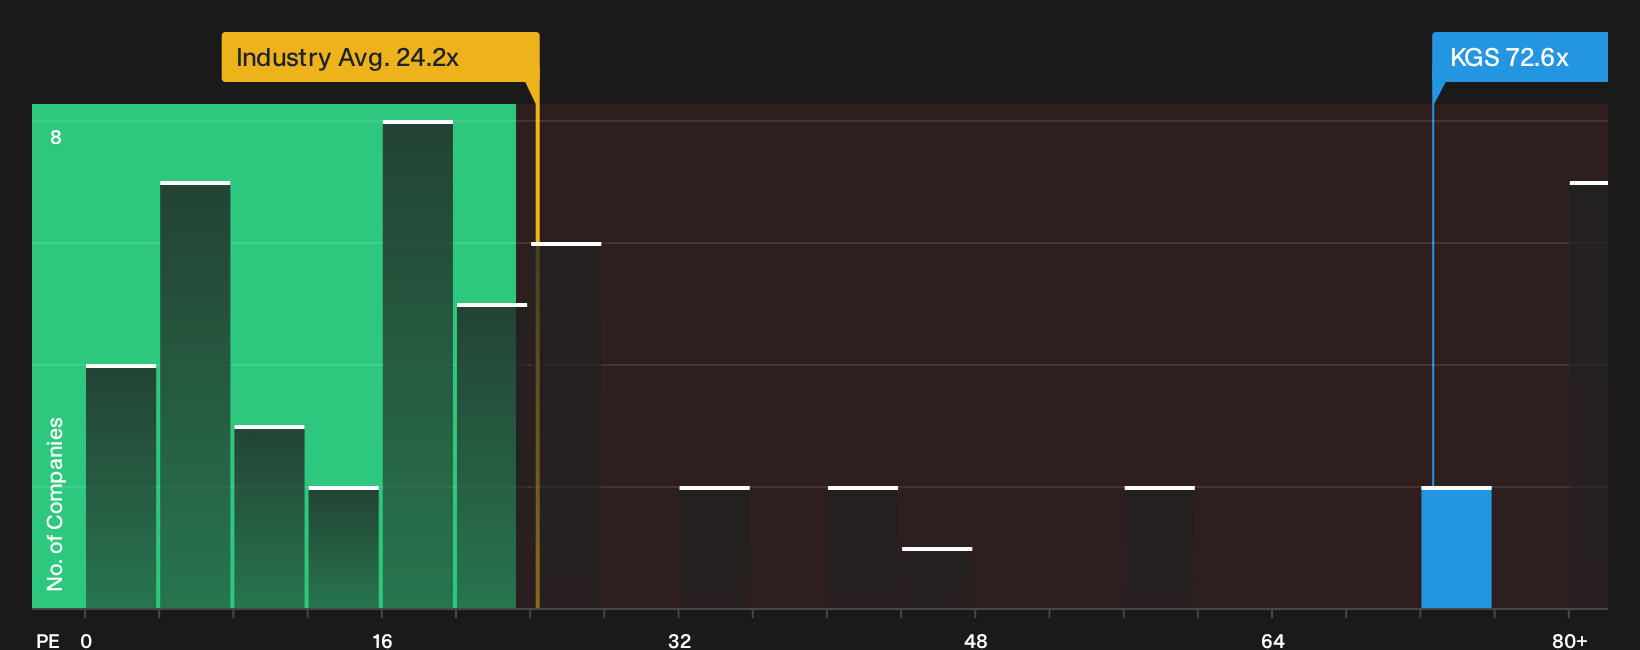
On the flip side, a simple P/E lens points to a very different picture for Kodiak Gas Services. The stock trades around 72.6x earnings compared with 24.2x for the US Energy Services industry, 44.3x for peers, and a fair ratio of 30.1x. That gap frames valuation risk more than opportunity. So which signal do you trust?
See what the numbers say about this price in more detail by reviewing the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals on Kodiak Gas Services so far. If you want your own read on whether the risk or reward side wins, start by weighing the 3 key rewards and 4 important warning signs.
Looking for more Kodiak Gas Services style ideas?
If Kodiak Gas Services has you thinking about what else might be hiding in plain sight, do not stop with one ticker. Broaden your watchlist and give yourself more options when the next opportunity lines up.
- Target quality at a discount by scanning our 30 high quality undervalued stocks that combine strong fundamentals with prices that may not fully reflect their financial profile.
- Anchor your portfolio with income by reviewing a focused set of 7 dividend fortresses that pair higher yields with business models built around regular payouts.
- Dial down potential volatility by filtering for 30 resilient stocks with low risk scores that score well on financial strength and balance sheet resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com