
MakeMyTrip (MMYT) Pulls Back As Fair Value Debate Comes Back Into Focus
MakeMyTrip (MMYT) has drawn fresh attention after a sharp pullback, with the share price down about 21% over the past month and roughly 41% lower year to date.
This pullback comes after a mixed run for MakeMyTrip, with the share price down sharply year to date but still ahead over three and five years when looking at total shareholder return. Recent weakness, including a 7 day share price decline of about 5%, suggests momentum has faded as investors reassess growth potential and risk after a strong multi year run.
Scan beyond MakeMyTrip and stress test your travel thesis against a curated group of consumer and services companies in the list of solid balance sheet and fundamentals (23 results)
MakeMyTrip has shed a large chunk of its recent gains, yet still carries a long multi year track record and a big gap to analyst targets. Does that reset justify stepping in now, or waiting for a deeper markdown before reassessing value?
Most Popular Narrative: 36% Undervalued
Against a last close of $47.92, the most followed narrative pins MakeMyTrip’s fair value at $75.40. It frames today’s pullback as a wide gap between current pricing and what that crowd thinks the travel platform could be worth when long term drivers play through.
Expanding online travel adoption, driven by continued growth in internet and smartphone penetration and increasing comfort with digital bookings, especially in underpenetrated tier-2 and tier-3 cities, is likely to further expand MakeMyTrip's addressable market and support sustained top-line revenue and booking volume growth.
Rising disposable incomes and a structural shift in consumer preferences towards experiences and frequent travel, including growth in international outbound travel, offer a long runway for increased gross bookings and recurring revenues, as reflected in robust year-on-year growth in both domestic and international segments.
See why 10 investors see MakeMyTrip as 36% undervalued.
Result: Fair Value of $75.40 (UNDERVALUED)
Still, this story can break if competition squeezes MakeMyTrip’s commissions or if high advertising spend continues to eat into profit progress for longer than bullish models assume.
Find out about the key risks to this MakeMyTrip narrative.
Another View on MakeMyTrip’s Valuation
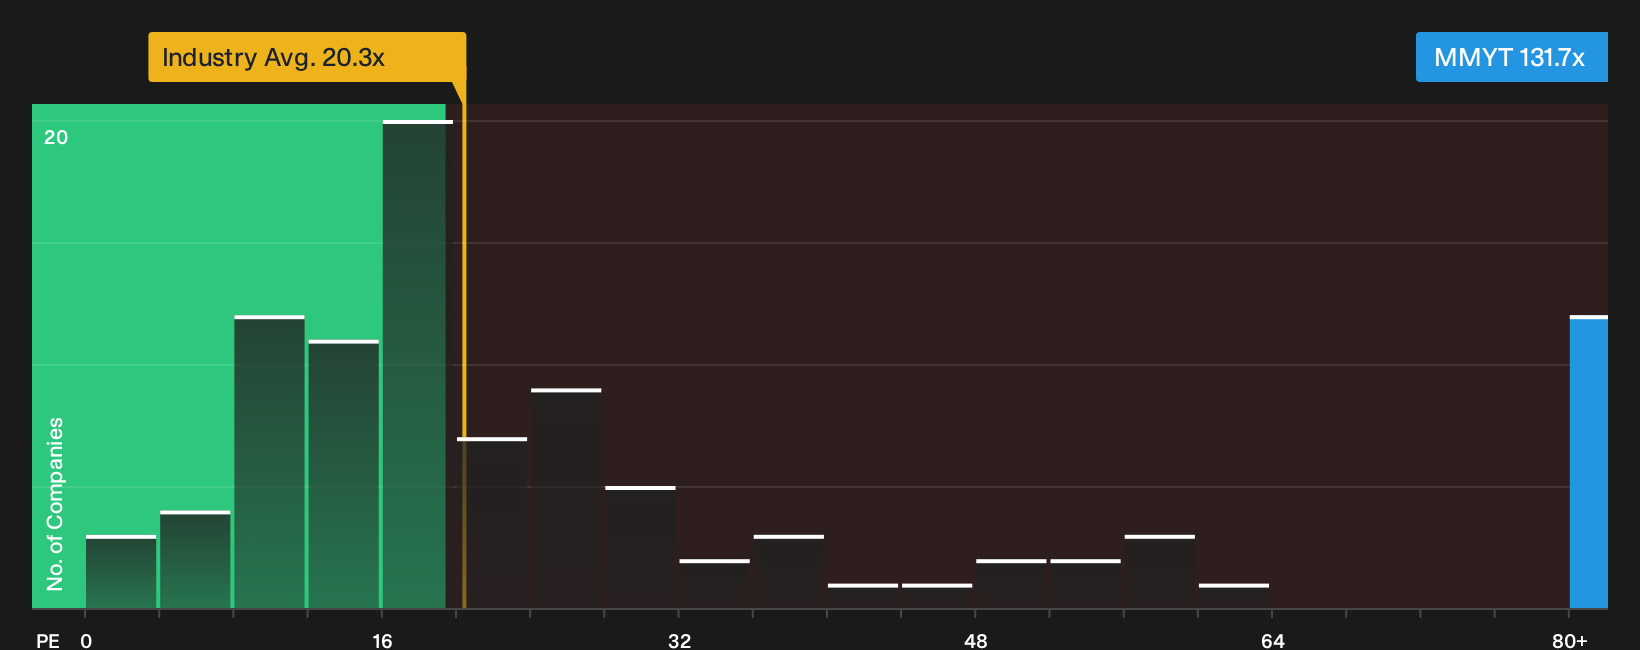
That 36% “undervalued” fair value narrative leans heavily on long term earnings forecasts. A second lens tells a different story. On raw pricing, MakeMyTrip trades on a P/E of 131.7x, while the Hospitality industry sits near 20.3x and peers around 27.5x, with a fair ratio estimate of 51.1x.
This gap means investors are paying a far higher multiple today than both sector averages and the level the market could move towards over time. The question is simple: Are you comfortable underwriting that much optimism, or does that premium feel like valuation risk that needs a bigger margin of safety?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on MakeMyTrip can feel paralysing. Move quickly on the data and pressure test the bullish and cautious angles for yourself with the 2 key rewards and 3 important warning signs.
Looking for more ideas beyond MakeMyTrip?
Do not stop at one opportunity. Use the Simply Wall Street Screener to quickly surface fresh stock ideas that match your risk tolerance and income goals.
- Target potential value upside by scanning companies that combine strong fundamentals with attractive pricing in the 35 high quality undervalued stocks.
- Build more dependable income by focusing on resilient payers through the 7 dividend fortresses.
- Dial back risk while staying invested by filtering for sturdier businesses using the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com