
Is Norwegian Cruise Line Holdings (NCLH) Undervalued As Norwegian Aura Entertainment Plans Roll Out?
Norwegian Cruise Line Holdings (NCLH) just put entertainment at center stage for its upcoming Norwegian Aura ship, outlining a Whitney Houston tribute show and several original productions tailored exclusively to this vessel.
For investors tracking Norwegian Cruise Line Holdings, the focus on exclusive entertainment comes against a weaker trading backdrop. The share price is at US$14.12 after a 30-day share price return that is down 18.10% and a 1-year total shareholder return that has declined 44.39%. This points to fading momentum as the market reassesses both growth potential and perceived risk.
Scan beyond Norwegian Cruise Line Holdings and assess other travel and leisure stocks that may be setting up for a rebound with the help of our curated 35 high quality undervalued stocks.
Bulls see Norwegian Cruise Line Holdings as a discounted way to play a recovering cruise market, while bears focus on the sharp share price slide. Which story does the current valuation actually support?
Most Popular Narrative: 32% Undervalued
On the most followed narrative, Norwegian Cruise Line Holdings screens as undervalued, with a fair value of $20.68 against the recent $14.12 close. This raises a clear question about whether sentiment has swung too far relative to fundamentals.
Strong progress on cost discipline and a trajectory toward sub-inflationary unit cost growth, combined with higher margins and EBITDA, allows for greater financial flexibility and deleveraging. This improves long-term return on invested capital and sets up future EPS growth as the operating leverage of new capacity and amenities comes online.
See why 53 investors see Norwegian Cruise Line Holdings as 32% undervalued.
Result: Fair Value of $20.68 (UNDERVALUED)
Still, the Norwegian Cruise Line Holdings turnaround story leans heavily on high debt and softer near term yields, which could quickly weaken confidence in that undervaluation case.
Find out about the key risks to this Norwegian Cruise Line Holdings narrative.
Another View on Norwegian Cruise Line Holdings’ Value
The earlier discussion leans on analyst targets and implied upside for Norwegian Cruise Line Holdings. A different lens comes from the SWS DCF model, which puts fair value at $4.23 per share, well below the current $14.12 price, and therefore points to the stock as overvalued on that framework.
That is a wide gap between analyst-driven upside and a cash flow based estimate. It leaves you with a simple question: Which set of assumptions do you trust more for Norwegian Cruise Line Holdings over the long haul?
Look into how the SWS DCF model arrives at its fair value.
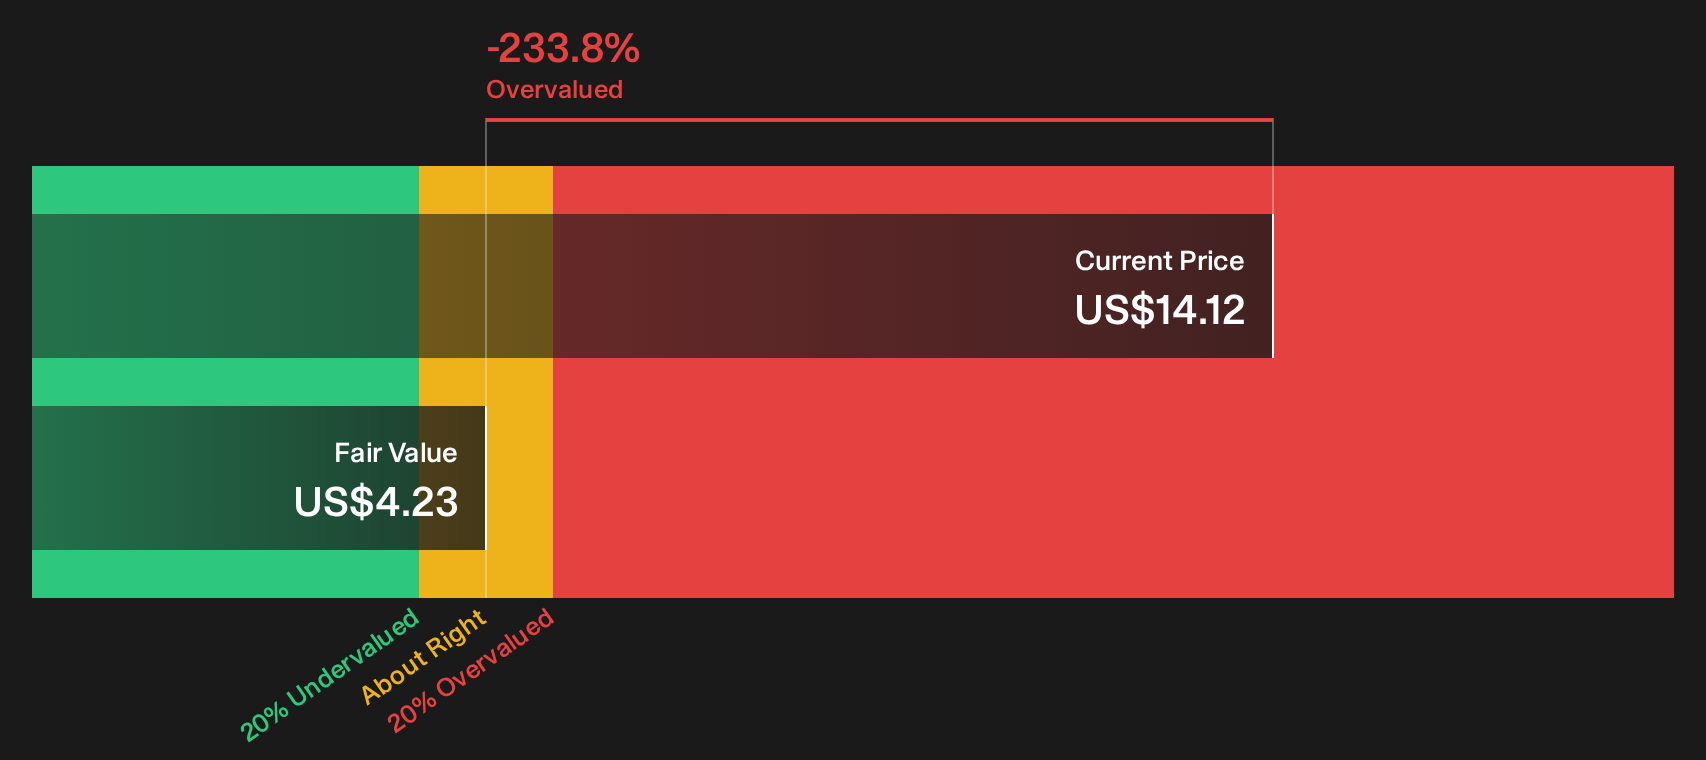
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Norwegian Cruise Line Holdings for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Norwegian Cruise Line Holdings so far. To cut through the noise, move fast, look at the core numbers yourself, then weigh the 4 key rewards and 1 important warning sign.
Looking For More Investment Ideas Beyond Norwegian Cruise Line Holdings?
If Norwegian Cruise Line Holdings has you rethinking your watchlist, do not stop there. Use the Simply Wall Street Screener to uncover fresh opportunities across sectors before others move first.
- Target potential value rebounds by scanning companies that combine quality fundamentals with discounted pricing through our curated 35 high quality undervalued stocks.
- Strengthen portfolio resilience by filtering for businesses with cleaner finances and robust metrics using the focused list of solid balance sheet and fundamentals (23 results).
- Spot potential future leaders early by zeroing in on smaller firms with strong underlying data through the carefully built 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com