
3 Canadian Value Stocks With P E Under 18
Long term interest rates have surged as central banks signal a higher cost of money for longer, which puts big, heavily owned stocks under the microscope and leaves many investors hugging cash. That creates a gap where high quality Canadian small caps can quietly trade on simpler stories and cleaner balance sheets. This article highlights three under followed companies from this high quality screen that may deserve a closer look.
The three stocks covered below are just a sample from this high quality idea. The full screen surfaces six more under the radar companies with equally compelling stories that are not discussed here.
If you want to quickly identify which of these high quality small caps best fits your own playbook, head straight into the High-Quality Undiscovered Gems screener to filter, analyze, and target your highest conviction candidates.
Minco Capital (TSXV:MMM)
Minco Capital is a Vancouver based investment firm that focuses on acquiring and selling stakes in public and private companies, with all of its CA$4 million in revenue tied to these investment activities. That aligns directly with the screener’s hunt for under followed small caps. The business is tiny at roughly CA$5 million in market value.
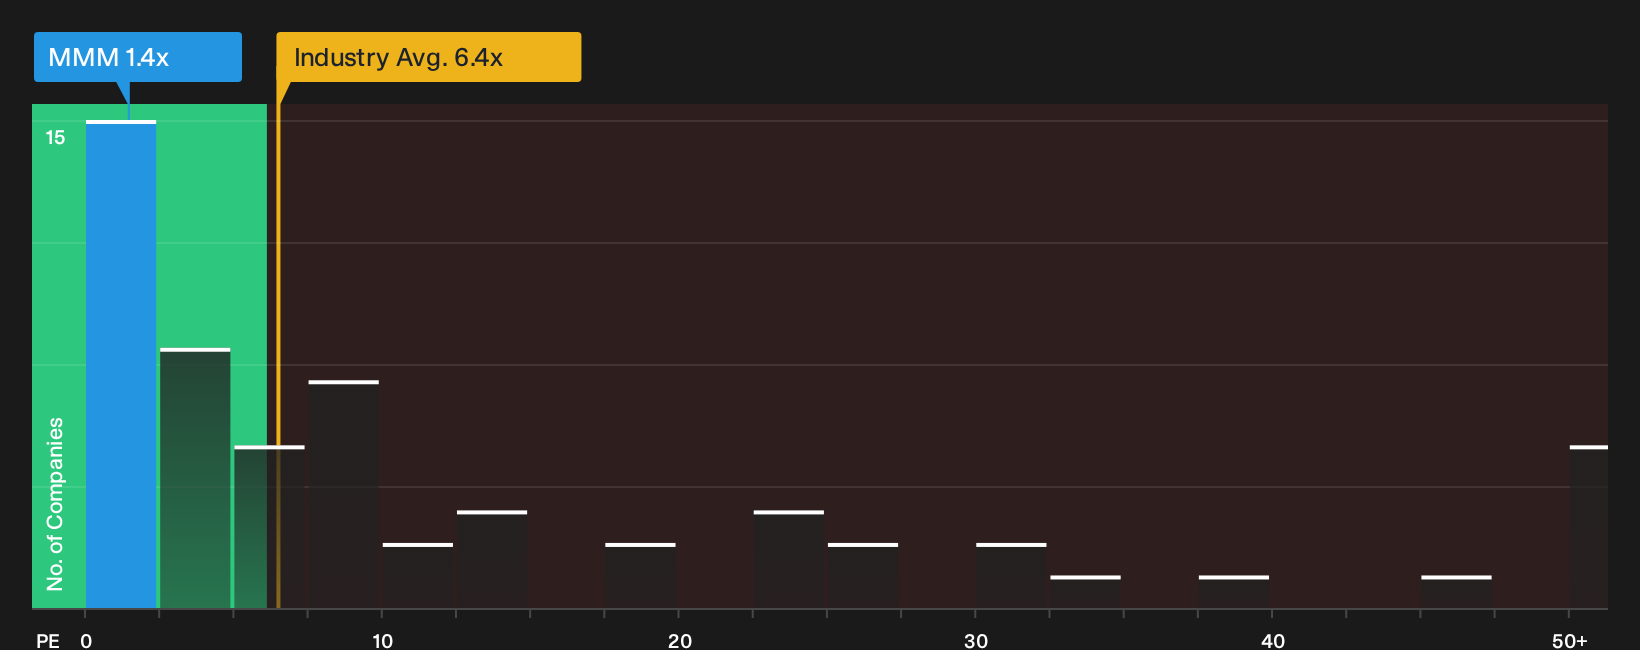
Minco Capital offers exposure to a curator of under followed early stage resource and tech stocks, rather than a single company. Strong recent earnings momentum and a low P/E of 1.4x are part of the High Quality Undiscovered Gems angle, depending on how one unseen pressure shapes the durability of those returns.
That hinge point is what you need to pressure test through the 2 key rewards and 2 important warning signs to see what might be driving or capping Minco Capital’s momentum.
Amerigo Resources (TSX:ARG)
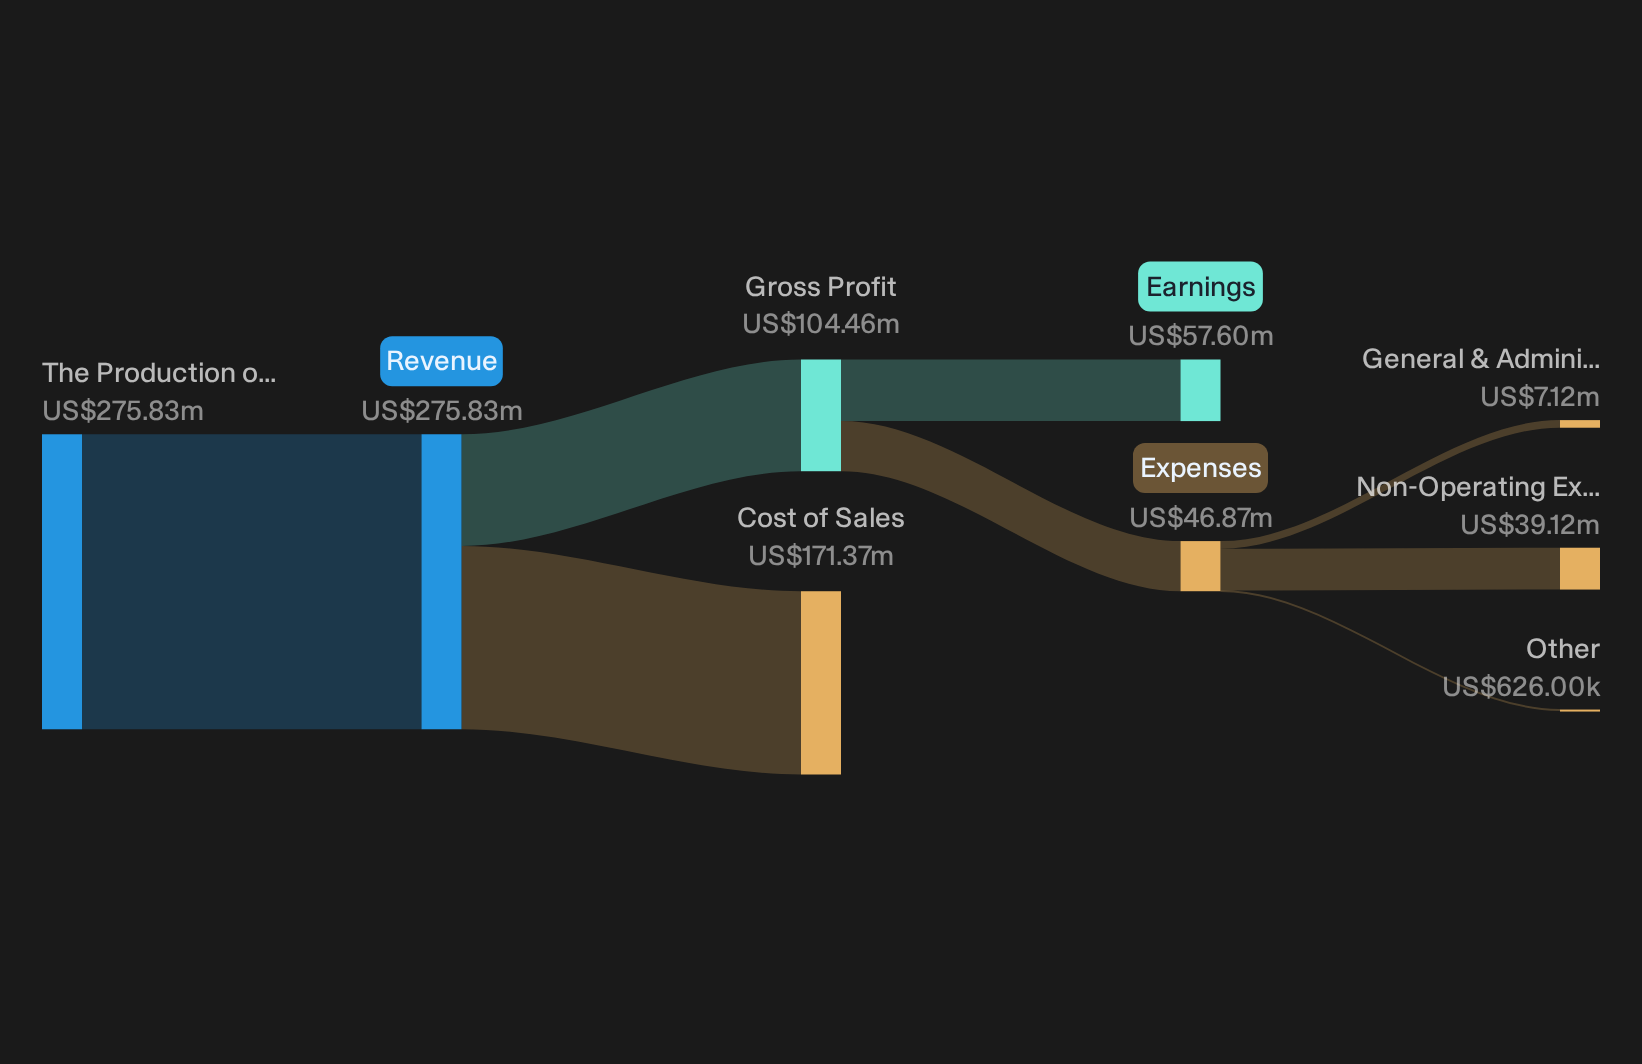
Amerigo Resources is a Vancouver based producer of copper and molybdenum concentrates tied directly to the copper theme through its Minera Valle Central operation. This operation generated about US$276 million from a single tolling agreement, and the stock carries a market value of roughly CA$1.4b.
Amerigo Resources taps directly into the copper supply chain through a single producing asset that has turned into a powerful earnings engine, with net margins at 20.9% and return on equity at 50.7%. That quality profile fits the High-Quality Undiscovered Gems idea, depending on how one unresolved pressure on its copper linked cash flows plays out.
That copper cash flow hinge is exactly what you can unpack in the 1 key reward and 2 important warning signs so you see what might accelerate or hold back Amerigo Resources next.
Fortuna Mining (TSX:FVI)
Fortuna Mining is a Vancouver based precious metals producer whose Lindero and Séguéla gold mines anchor its High-Quality Undiscovered Gems profile, generating about US$680 million from Sango, US$357 million from Mansfield and US$145 million from Bateas, with a market value near CA$4.9b.
For investors hunting quality precious metals exposure that has not yet become a household story, Fortuna Mining brings a growing cluster of producing and near term gold projects that fit neatly with the screener’s focus on overlooked small caps with solid fundamentals.
"Expansion at Seguela and the development of Diamba Sud position Fortuna to restore and surpass its previous production levels, with higher‑margin and longer‑life ounces, aligning with anticipated increases in global demand for gold and other strategic metals, supporting future revenue and cash flow growth."
What happens to Fortuna Mining’s earnings power now largely hinges on how one cost and execution swing factor plays out across these flagship projects.
If that cost swing matters to your thesis on Fortuna Mining, read the full narrative for Fortuna Mining to see how execution risk, jurisdiction and capital plans could reshape the story.

Seeking Fresh Alternatives Before They Fly
Some of the sharpest breakout stories start quietly, then move fast once momentum catches. Before fresh ideas get caught by the crowd and pricing shifts, consider your options early.
- Spot income workhorses early and use the 1 dividend fortresses to track payouts that could hold up even when prices drop or headlines turn noisy.
- Rotate into potential compounding machines with the 5 high quality undervalued stocks while these financially solid picks are still under the radar for now and pricing still matters.
- Target future-facing infrastructure by scanning the 88 AI infrastructure stocks before capital floods in and the best positioned contenders finish quietly rerating.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com