
We Think Borealis Mining (CVE:BOGO) Can Easily Afford To Drive Business Growth
We can readily understand why investors are attracted to unprofitable companies. For example, although software-as-a-service business Salesforce.com lost money for years while it grew recurring revenue, if you held shares since 2005, you'd have done very well indeed. Having said that, unprofitable companies are risky because they could potentially burn through all their cash and become distressed.
Given this risk, we thought we'd take a look at whether Borealis Mining (CVE:BOGO) shareholders should be worried about its cash burn. In this report, we will consider the company's annual negative free cash flow, henceforth referring to it as the 'cash burn'. The first step is to compare its cash burn with its cash reserves, to give us its 'cash runway'.
When Might Borealis Mining Run Out Of Money?
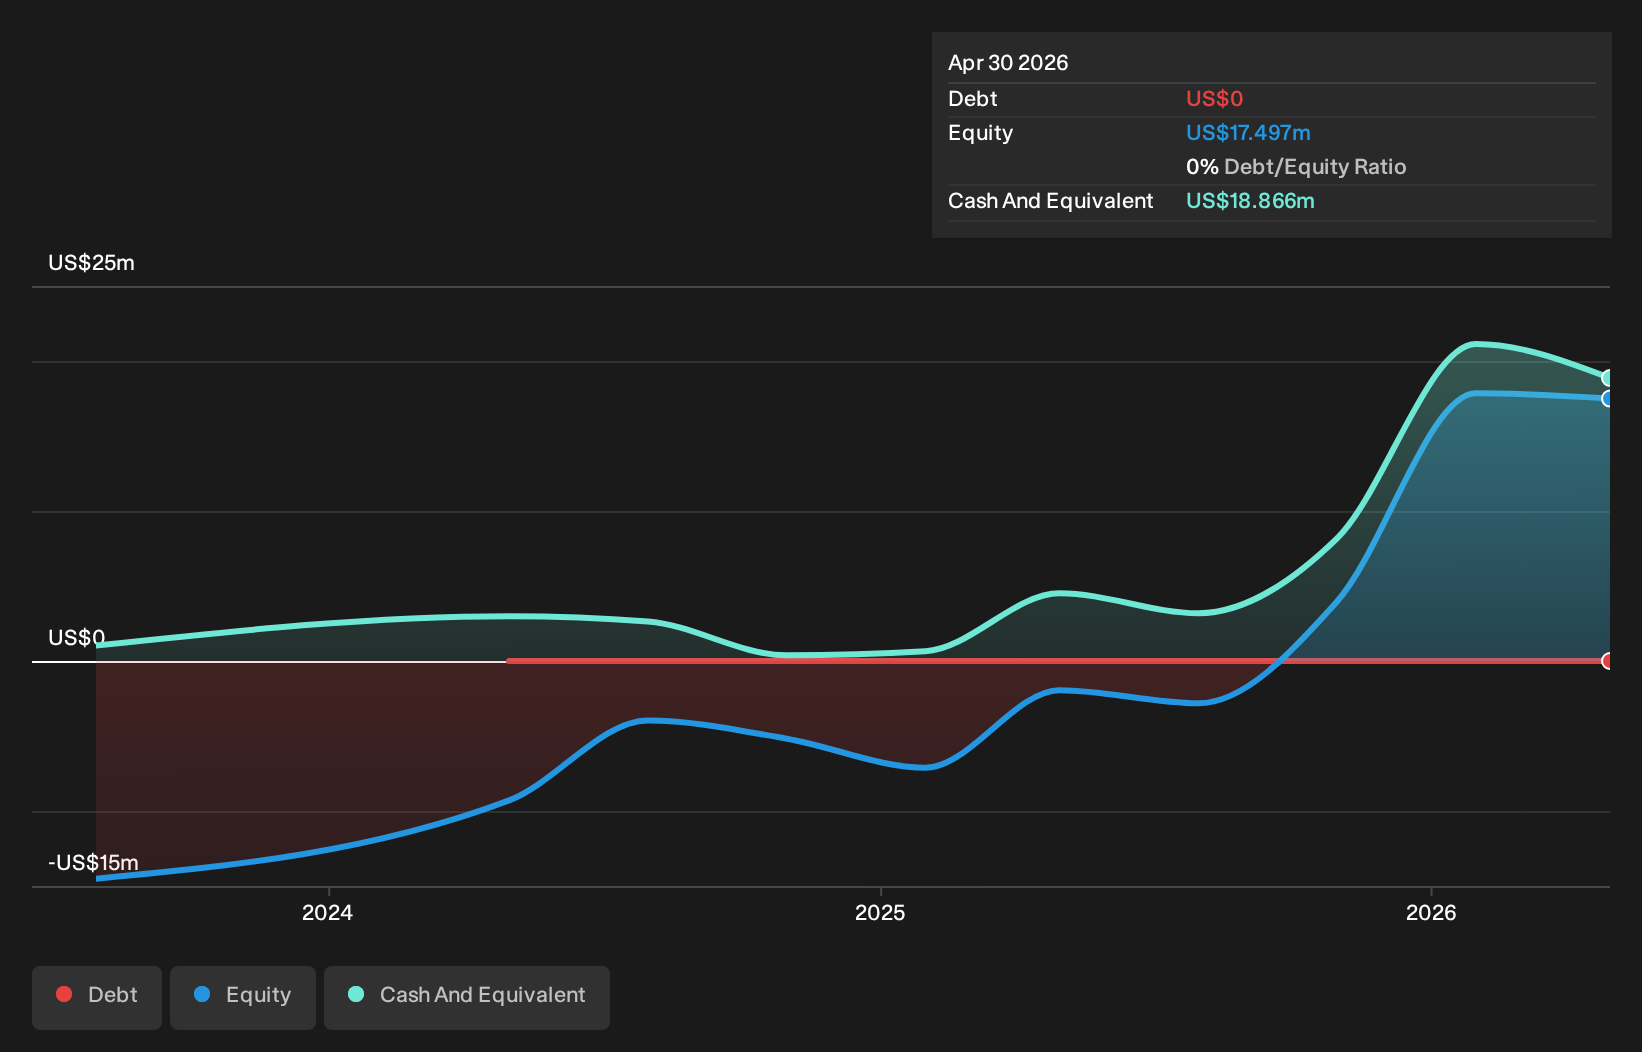
You can calculate a company's cash runway by dividing the amount of cash it has by the rate at which it is spending that cash. As at April 2026, Borealis Mining had cash of US$19m and no debt. In the last year, its cash burn was US$9.7m. That means it had a cash runway of around 23 months as of April 2026. Importantly, though, analysts think that Borealis Mining will reach cashflow breakeven before then. In that case, it may never reach the end of its cash runway. You can see how its cash balance has changed over time in the image below.
Check out our latest analysis for Borealis Mining
How Well Is Borealis Mining Growing?
At first glance it's a bit worrying to see that Borealis Mining actually boosted its cash burn by 27%, year on year. On a more positive note, the operating revenue improved by 277% over the period, offering an indication that the expenditure may well be worthwhile. If revenue is maintained once spending on growth decreases, that could well pay off! It seems to be growing nicely. Clearly, however, the crucial factor is whether the company will grow its business going forward. For that reason, it makes a lot of sense to take a look at our analyst forecasts for the company.
Can Borealis Mining Raise More Cash Easily?
While Borealis Mining seems to be in a fairly good position, it's still worth considering how easily it could raise more cash, even just to fuel faster growth. Generally speaking, a listed business can raise new cash through issuing shares or taking on debt. Commonly, a business will sell new shares in itself to raise cash and drive growth. By looking at a company's cash burn relative to its market capitalisation, we gain insight on how much shareholders would be diluted if the company needed to raise enough cash to cover another year's cash burn.
Since it has a market capitalisation of US$118m, Borealis Mining's US$9.7m in cash burn equates to about 8.2% of its market value. That's a low proportion, so we figure the company would be able to raise more cash to fund growth, with a little dilution, or even to simply borrow some money.
So, Should We Worry About Borealis Mining's Cash Burn?
It may already be apparent to you that we're relatively comfortable with the way Borealis Mining is burning through its cash. In particular, we think its revenue growth stands out as evidence that the company is well on top of its spending. Although its increasing cash burn does give us reason for pause, the other metrics we discussed in this article form a positive picture overall. It's clearly very positive to see that analysts are forecasting the company will break even fairly soon. After considering a range of factors in this article, we're pretty relaxed about its cash burn, since the company seems to be in a good position to continue to fund its growth. Its important for readers to be cognizant of the risks that can affect the company's operations, and we've picked out 1 warning sign for Borealis Mining that investors should know when investing in the stock.
Of course Borealis Mining may not be the best stock to buy. So you may wish to see this free collection of companies boasting high return on equity, or this list of stocks with high insider ownership.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team (at) simplywallst.com.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.