
Exploring Three Undiscovered Gems in Global Markets
In the current global market landscape, small-cap stocks have been under pressure as the Russell 2000 Index lagged behind its large-cap counterparts amidst rising interest rates and geopolitical tensions impacting oil prices. However, these challenging conditions can sometimes create opportunities to identify undiscovered gems that possess strong fundamentals and potential for growth. In this context, a good stock might be one that demonstrates resilience in volatile times, has a robust business model, and is positioned to capitalize on emerging trends despite broader market uncertainties.
Top 10 Undiscovered Gems With Strong Fundamentals Globally
| Name | Debt To Equity | Revenue Growth | Earnings Growth | Health Rating |
|---|---|---|---|---|
| Chongqing Machinery & Electric | 18.92% | 8.43% | 26.16% | ★★★★★★ |
| Taiyo KagakuLtd | 0.68% | 6.49% | 11.88% | ★★★★★★ |
| C-Rad | NA | 13.57% | 13.83% | ★★★★★★ |
| GROUPE SFPI | 18.02% | 4.25% | -29.76% | ★★★★★★ |
| Fourth Milling | NA | 12.93% | 16.76% | ★★★★★☆ |
| Alexandria Group Oyj | 5.79% | 6.84% | 8.17% | ★★★★★☆ |
| Forth Smart Service | 44.85% | -3.80% | 10.19% | ★★★★★☆ |
| Skue Sparebank | 122.31% | 16.16% | 27.93% | ★★★★☆☆ |
| Sing Investments & Finance | 0.10% | 5.85% | 7.00% | ★★★★☆☆ |
| Primo Global Holdings | 70.93% | 9.87% | 28.79% | ★★★☆☆☆ |
Below we spotlight a couple of our favorites from our exclusive screener.
Mota-Engil SGPS (ENXTLS:EGL)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: Mota-Engil SGPS, S.A. is involved in public and private construction works and related services across Europe, Africa, and Latin America with a market capitalization of approximately €1.54 billion.
Operations: Mota-Engil SGPS generates revenue primarily from its Engineering & Construction (E&C) segments in Africa (€2.24 billion) and Latin America (€2.09 billion), with additional contributions from Europe (€380 million) and the Environment segment (€662.03 million). The company's revenue streams highlight a significant focus on E&C activities across multiple continents, particularly in Africa and Latin America.
Mota-Engil, a construction player with a knack for growth, has seen its earnings climb 35.9% annually over the past five years. Despite this impressive trajectory, interest payments on debt are not fully covered by EBIT, which stands at 2.8x coverage rather than the desired 3x. The company's net debt to equity ratio remains high at 223.7%, though it has decreased from a staggering 643.4% in five years. Recent results show sales of €2.9 billion and net income of €74 million for H1 2026, reflecting steady progress from last year's figures of €2.7 billion and €59 million respectively.
- Click here to discover the nuances of Mota-Engil SGPS with our detailed analytical health report.
Evaluate Mota-Engil SGPS' historical performance by accessing our past performance report.

STEF (ENXTPA:STF)
Simply Wall St Value Rating: ★★★☆☆☆
Overview: STEF SA specializes in temperature-controlled road transport and logistics services for the agri-food industry, with a market cap of €1.56 billion.
Operations: STEF SA's primary revenue streams are derived from its operations in France, generating €2.58 billion, and international activities contributing €2.11 billion.
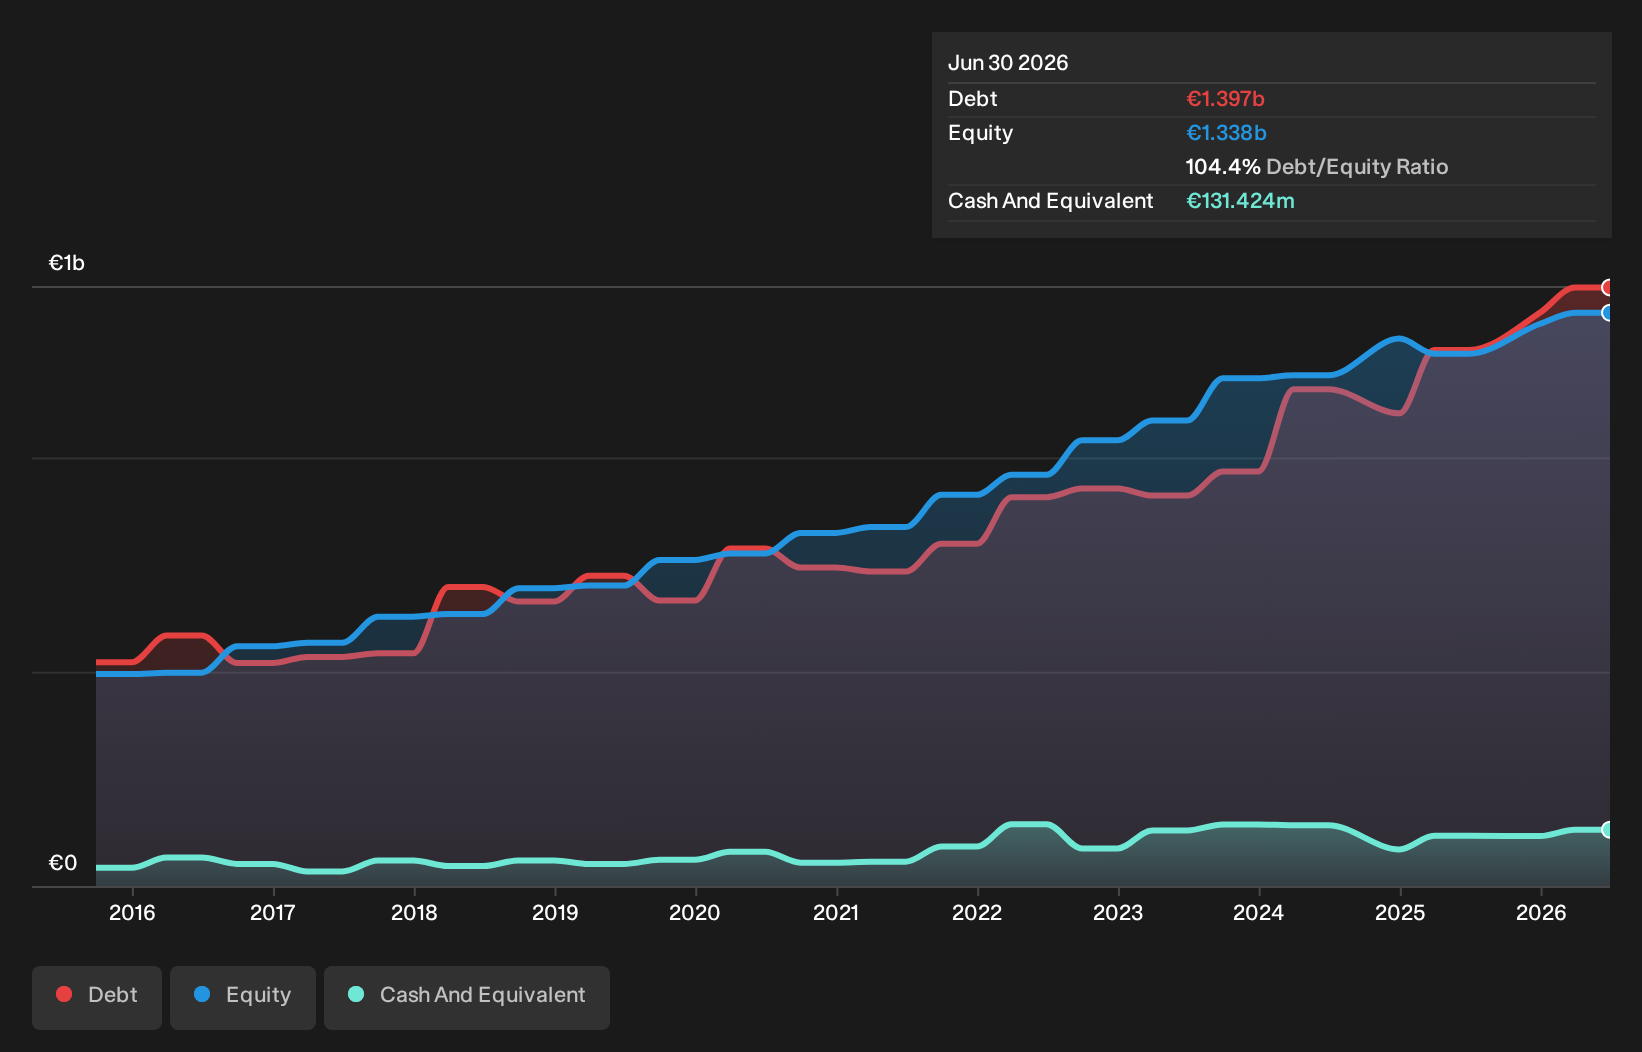
STEF has shown impressive growth with recent earnings jumping to €55.92 million for the half year, a significant rise from €15.83 million last year, and sales reaching €2.69 billion from €2.47 billion previously. Despite this, the debt to equity ratio has climbed to 104.4% over five years, indicating a high leverage level with net debt at 94.6%. Trading at 42% below estimated fair value suggests potential undervaluation, while its EBIT covers interest payments comfortably at 4.9 times interest repayments, reflecting strong operational performance amidst its high debt profile in the transportation sector.
- Get an in-depth perspective on STEF's performance by reading our health report here.
Understand STEF's track record by examining our Past report.
HD Hyundai Energy SolutionsLtd (KOSE:A322000)
Simply Wall St Value Rating: ★★★★★★
Overview: HD Hyundai Energy Solutions Co., Ltd. specializes in the production of solar cells and modules, with a market capitalization of ₩1.42 trillion.
Operations: The company generates revenue primarily from the production and sale of solar cells and modules. Its financial performance is reflected in a market capitalization of ₩1.42 trillion.
HD Hyundai Energy Solutions seems to be a promising candidate in the energy sector, trading at 46.9% below its estimated fair value. Over the past five years, it has significantly reduced its debt-to-equity ratio from 40.9% to 3.3%, indicating improved financial health. The company's earnings have skyrocketed by 333% in the past year, outpacing the semiconductor industry's growth of 71.5%. Despite recent share price volatility, HD Hyundai's strong cash position relative to debt and high-quality earnings suggest resilience and potential for future growth within its industry context.

Key Takeaways
- Reveal the 167 hidden gems among our Global Undiscovered Gems With Strong Fundamentals screener with a single click here.
- Are you invested in these stocks already? Keep abreast of every twist and turn by setting up a portfolio with Simply Wall St, where we make it simple for investors like you to stay informed and proactive.
- Simply Wall St is your key to unlocking global market trends, a free user-friendly app for forward-thinking investors.
Ready For A Different Approach?
- Explore high-performing small cap companies that haven't yet garnered significant analyst attention.
- Fuel your portfolio with companies showing strong growth potential, backed by optimistic outlooks both from analysts and management.
- Find companies with promising cash flow potential yet trading below their fair value.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com