
What Is Drawing Fresh Attention To Palantir Technologies (PLTR)?
Palantir Technologies (PLTR) is back in the spotlight after unveiling a cluster of alliances with NVIDIA, Nebius and Method Security that tie its AI platforms more deeply into supply chains, cyber defense and sovereign infrastructure.
Recent price action suggests investors are still rewarding Palantir Technologies for its AI push. The share price has climbed 48.65% over the past 90 days, while the 1-year total shareholder return is slightly down 2.6%. This shows strong near term momentum on top of a very large 3-year total shareholder return.
Scan how other AI infrastructure plays stack up to Palantir Technologies by reviewing the hand picked 88 AI infrastructure stocks embedded in this theme.
The recent surge leaves Palantir Technologies looking far richer than it did just three months ago. Does it make more sense to accept today’s price, or wait and hope the next pullback arrives first?
Most Popular Narrative: 3.8% Overvalued
According to the most widely followed Palantir Technologies narrative on Simply Wall St, the fair value sits at $171.06, a shade below the recent $177.64 close, which frames the current move as a stretch above intrinsic value rather than a bargain.
Earlier this year, I exited my Palantir position, expecting lower prices and a potential revisit to the $107 to $120 range. While I maintained that it remains a great company, the valuation and price action did not look attractive in the near/medium term, leading me to seek better opportunities elsewhere.
See why 228 investors see Palantir Technologies as 4% overvalued.
According to BlackGoat, this slight premium to the $171.06 narrative fair value reflects a market that is already factoring in strong earnings growth forecasts of around 32% per year and high returns on equity near 30%, leaving less margin for disappointment if execution or sentiment cools.
Result: Fair Value of $171.06 (OVERVALUED)
Still, any slip in Palantir Technologies’ high growth forecasts, or a reset in investor enthusiasm for premium AI valuations, could quickly flip this overvaluation story.
Find out about the key risks to this Palantir Technologies narrative.
Another View on Palantir Technologies’ Value
While the leading Palantir Technologies narrative calls the stock 3.8% overvalued, the SWS DCF model points in the other direction. On that framework, the recent $177.64 price sits about 4.5% below an estimated future cash flow value of $185.97. This frames today’s level as mildly undervalued instead of stretched.
The gap between a slightly rich narrative fair value and an SWS DCF result that signals a small discount raises a practical question: Are current expectations already fully priced in, or is the market leaving a bit of headroom for those cash flow forecasts to play out, even if the margin of safety is thin?
For investors who want to see how sensitive that outcome is to different growth or margin inputs, it can help to go straight to the source and review the full SWS cash flow workup behind these numbers Look into how the SWS DCF model arrives at its fair value.
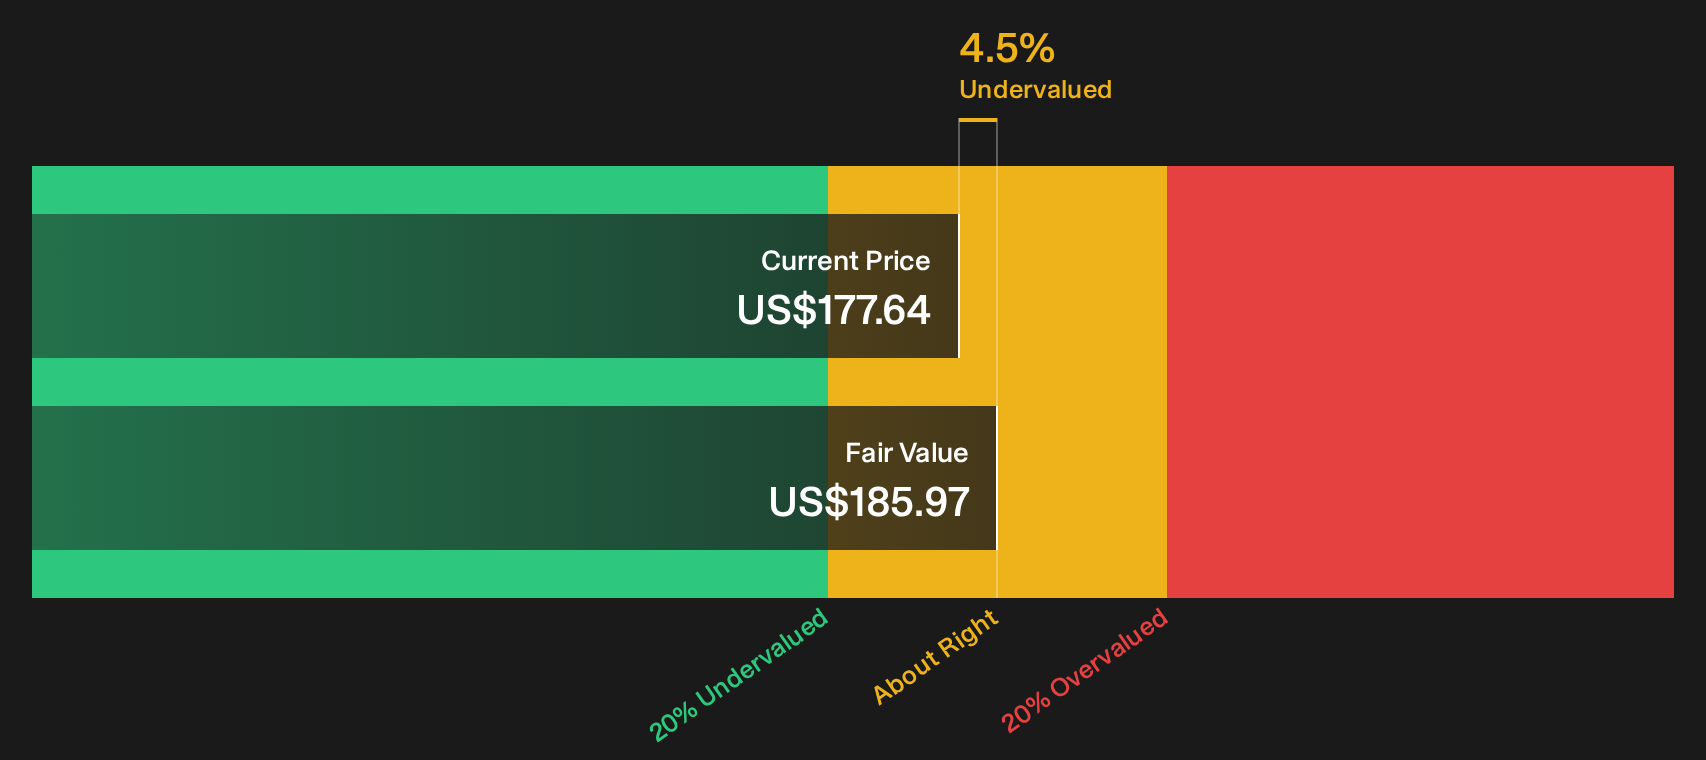
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Palantir Technologies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 35 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed messages on Palantir Technologies valuation so far. If you want to move quickly and rely on your own judgment, consider both the upside potential and the risk flags by checking the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Palantir Technologies?
If Palantir Technologies is already on your radar, do not stop there. Broaden your watchlist with other clear, data backed ideas that could complement your portfolio.
- Target potential bargains by screening for companies with strong fundamentals that trade at a discount using the 35 high quality undervalued stocks.
- Prioritise resilience by filtering for businesses with robust finances through the list of solid balance sheet and fundamentals (23 results).
- Hunt for underfollowed opportunities by scanning the 16 high quality undiscovered gems before the crowd turns its attention their way.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com