
PDF Solutions (PDFS) Could Be 25% Undervalued After Exensio Aurora Launch
PDF Solutions (PDFS) has introduced Exensio Aurora, a new analytics architecture designed for petabyte-scale semiconductor manufacturing data and agentic AI. Beta access begins this month, with public demos planned for October.
Despite unveiling Exensio Aurora, PDF Solutions’ recent share price performance has been choppy, with the stock down 31.82% on a 90 day share price return, but still showing a 49.85% year to date share price gain and a 101.18% 1 year total shareholder return. This suggests that investors may have already priced in substantial progress while reassessing near term risk around execution and sentiment.
Scan how PDF Solutions fits into the wider AI-driven chip supply chain by comparing it with a curated group of 88 AI infrastructure stocks shaping data-heavy manufacturing and compute demand.
Bulls view PDF Solutions as a scarce asset in AI-heavy chip manufacturing, while bears see a stock that ran too far, too fast. Which case does the current valuation support next?
Most Popular Narrative: 25% Undervalued
Against a last close of $44.28, the most followed valuation story for PDF Solutions pegs fair value at $59.38, pointing to a sizable gap that centers on earnings power, recurring software, and how much investors are prepared to pay for that mix.
Accelerated enterprise adoption of PDF's secure, cloud-based supply chain orchestration and analytics solutions, including secureWISE, Sapience Manufacturing Hub, and Exensio, positions the company to capitalize on the industry's growing need for integrated data traceability and resilient manufacturing networks; this supports robust recurring revenue growth and higher earnings stability.
See why 13 investors see PDF Solutions as 25% undervalued.
This narrative uses an 11.19% discount rate and assumes that by 2029 PDF Solutions could reach $384.2 million in revenue and $86.6 million in earnings, with the stock trading on a P/E of 38.9x at that point. The implied fair value of $59.38 then sits only slightly above the current analyst consensus target, which suggests those forecasts and the discount rate are doing most of the heavy lifting rather than any aggressive multiple expansion from here.
Analysts supplying this framework also factor in share issuance, ongoing heavy investment, and risks around customer concentration and geopolitics. That means the undervaluation call is less about ignoring those issues and more about the belief that recurring analytics, AI integration across Exensio and Sapience, and cross selling into large chip manufacturers can offset them over time.
Result: Fair Value of $59.38 (UNDERVALUED)
Still, the PDF Solutions story can change quickly if geopolitical pressure limits access to China, or if heavy R&D spending fails to translate into stronger profitability.
Find out about the key risks to this PDF Solutions narrative.
Another View: PDF Solutions Looks Expensive On Sales
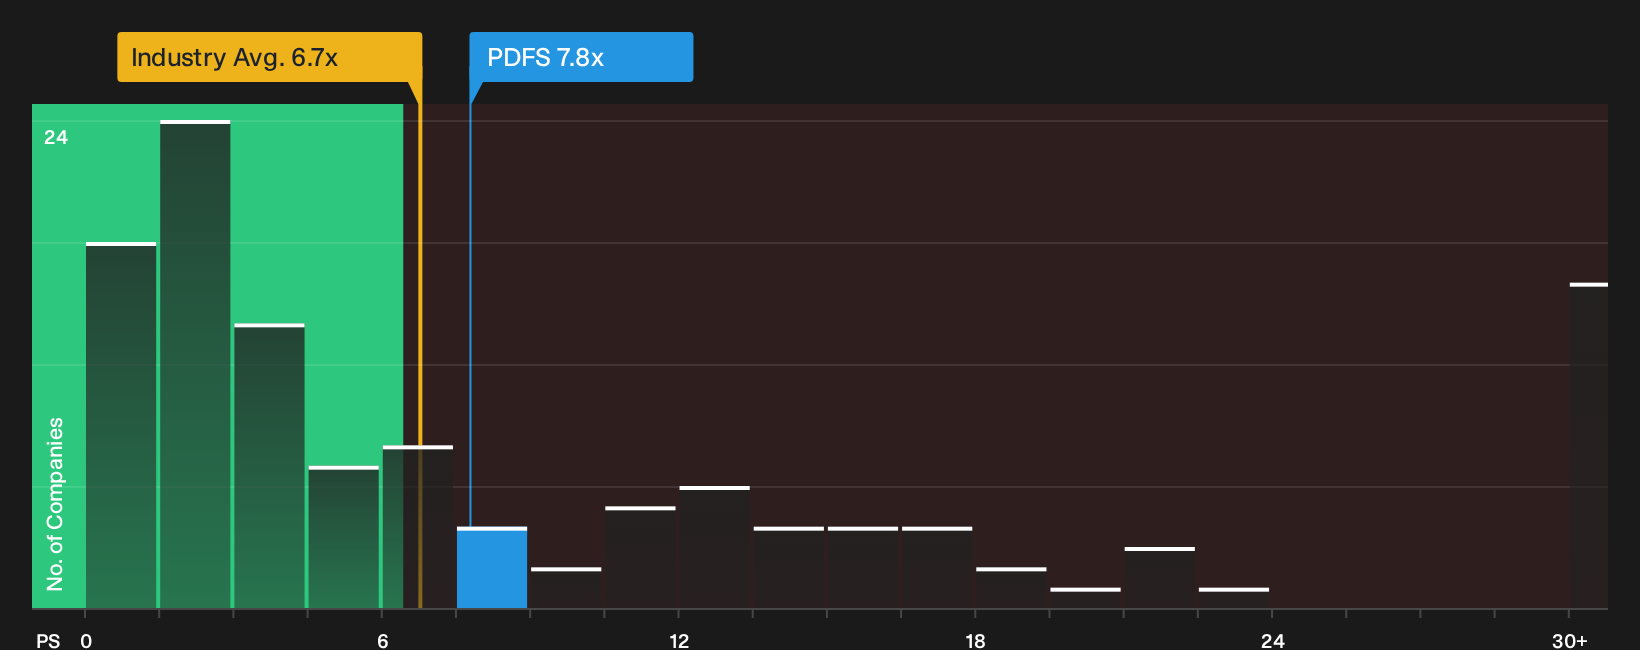
The story changes when you look at PDF Solutions through its P/S ratio. The stock trades around 7.8x sales compared with 6.7x for the US semiconductor industry and a 7.1x fair ratio. That higher multiple suggests there may be less room for error if growth or margins disappoint.
Our P/S-based view does not match the 25% undervalued narrative, so it places more weight on your own assumptions about how long high growth and margin expansion can continue before the market potentially re-rates the shares. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around PDF Solutions can be confusing, so move quickly, evaluate the potential upside and downside yourself, then weigh the 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond PDF Solutions?
If the PDF Solutions setup has your attention, do not stop here. Broader context often reveals opportunities that a single ticker can never show alone.
- Target stronger upside potential by scanning a focused group of high quality opportunities using the 35 high quality undervalued stocks.
- Prioritize resilience and sleep better at night by filtering for companies on the 30 resilient stocks with low risk scores.
- Hunt for future standouts before they attract the crowd by zeroing in on the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com