
JD.com (JD) Looks Fairly Valued Following Rising Earnings Optimism
Investor optimism around JD.com (JD) is building ahead of its upcoming earnings release, as upward revisions to analyst estimates and expectations for higher earnings and revenue focus attention on the stock’s recent move relative to the S&P 500.
That optimism is landing on a stock that has lost momentum over a longer stretch, with JD.com’s share price down 8.5% over the past month and 8.8% year to date, and total shareholder return falling about 20.6% over the last year as investors reassess both growth potential and risk.
Scan how other discounted consumer and e-commerce players stack up against JD.com by reviewing the hand-picked 33 high quality undervalued stocks now on Simply Wall St.
So after a painful year for JD.com holders and a recent slide, are you being paid enough on price to take the earnings risk from here, or does the valuation still look tight?
Most Popular Narrative: 0% Overvalued
The most followed JD.com narrative pegs fair value at about $26.83, almost exactly in line with the recent $26.92 close. This puts the spotlight on the assumptions behind that tight gap rather than on any obvious bargain.
Broad-based revenue growth, improving retail margins, rapid user gains from new services, and expanding global footprint position JD.com for enhanced profitability and reduced reliance on its domestic market.
Management reiterated long-term confidence in profitability expansion, targeting high single-digit profit margin over time as new businesses scale and integration synergies materialize, which could support overall group-level net margin improvement and higher long-term earnings.
See why 16 investors see JD.com as 0% overvalued.
Result: Fair Value of $26.83 (ABOUT RIGHT)
Still, if JD.com sustains broad-based revenue strength and continues to expand retail margins, that could quickly call into question the idea that the stock is fully priced.Find out about the key risks to this JD.com narrative.
Another View: JD.com Through The P/E Lens
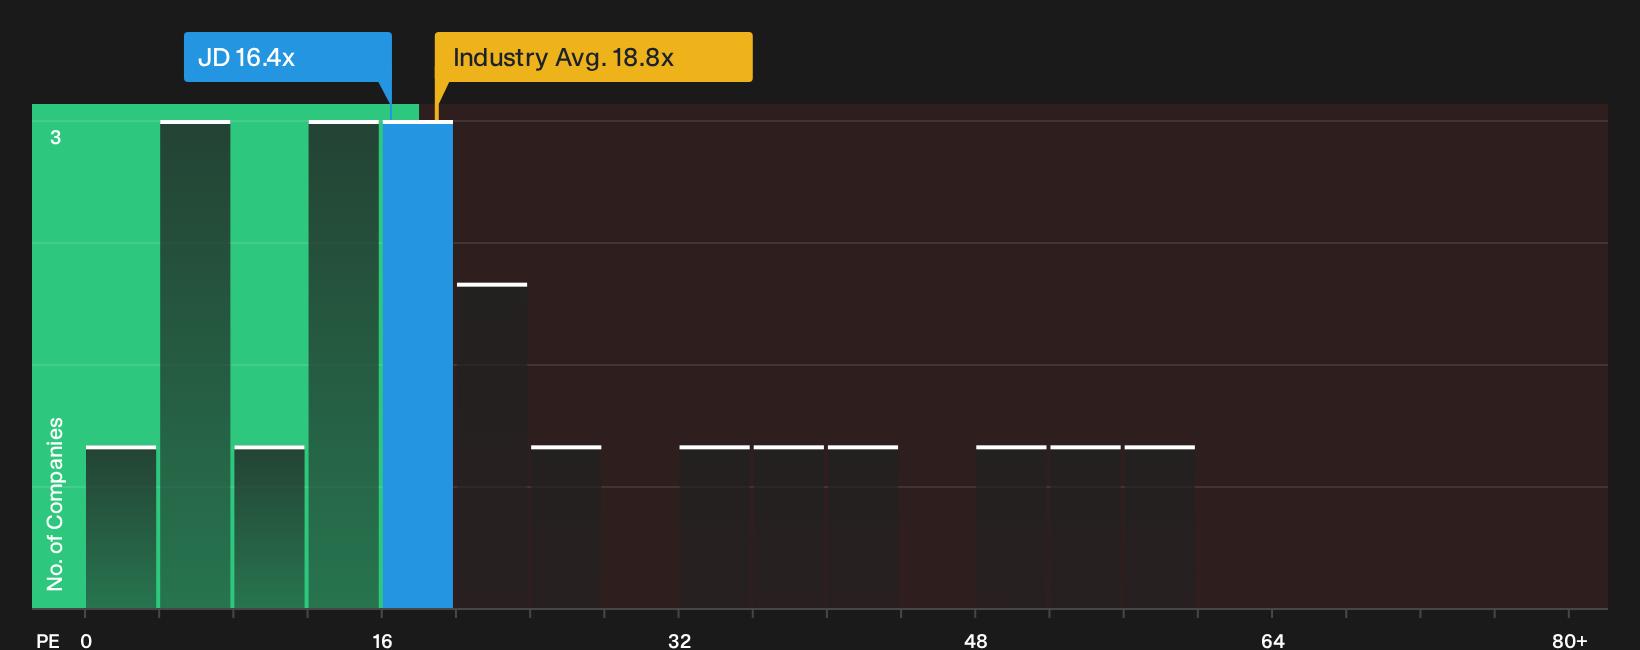
Zooming out from that $26.83 fair value mark, JD.com looks different when you focus on its current P/E of 16.4x. That level sits well below peer averages at 29.4x and under the 30x fair ratio, which points to a valuation gap that could either signal a cushion or hint at lingering risk. Which side of that tradeoff do you lean toward?
For a numbers first cross check of JD.com's pricing, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed feelings on JD.com so far. If you want to move beyond the headline debate and evaluate the thesis yourself, start with the 4 key rewards and 1 important warning sign
Looking for more JD.com investment ideas?
If JD.com has sharpened your focus on pricing and risk, do not stop here. Fresh ideas often come from comparing very different kinds of opportunities.
- Target reliable income streams by reviewing companies in the 6 dividend fortresses that may suit a more payout focused approach.
- Hunt for resilient balance sheets and steadier profiles through the list of solid balance sheet and fundamentals (23 results) to see which businesses match your risk comfort.
- Spot early stage potential by working through the 16 high quality undiscovered gems before the crowd starts paying attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com