
Should Product Launches Require Action From Semtech (SMTC) Investors?
- Semtech recently released three connectivity focused products, including the TDS2621LP SurgeSwitch device, a 10G PON OLT chipset, and 224G linear TIA and driver solutions for data centers and AI or ML clusters.
- The breadth of these launches points to Semtech concentrating R&D and product execution on industrial automation, fiber broadband infrastructure, and high speed data center connectivity in parallel.
- We will now look at how Semtech's investment narrative could be influenced by the new 10G PON OLT chipset announcement.
Scan how Semtech’s connectivity push lines up with broader infrastructure trends by comparing it with hand picked 88 AI infrastructure stocks powering next generation data centers and fiber networks.
Semtech Investment Narrative Recap
To own Semtech, you need to believe the business can turn strong product launches in data center, IoT and protection devices into consistent earnings, while keeping margins intact as mix shifts. The near term hinge point is execution on high performance connectivity and signal integrity, where customer adoption and stable orders matter more than headlines.
The biggest risk still sits in margin quality and integration. Past goodwill impairment, mix driven gross margin pressure and large one off items show how quickly profitability can wobble. The latest announcements help demonstrate R&D commitment; however, they do not yet change those core execution and demand risks in a material way.
Among the recent launches, the 10G PON OLT chipset appears closest to a near term catalyst. It directly targets fiber broadband infrastructure, one of the areas analysts already highlight as important for Semtech through signal integrity products and passive optical network exposure.
If this chipset moves from sampling into meaningful volume by the planned September 2026 production window, investors will likely focus on how it affects product mix, gross margin and order visibility in China and other key regions. Any delay, slow customer qualification or tighter data center and telecom CapEx would likely keep that potential upside in check.
Semtech's narrative projects US$2.3b revenue and US$546.9 million earnings by 2029. This assumes 27.5% yearly revenue growth and a shift in profitability from a loss of US$33.2 million today to earnings of US$546.9 million, which is an increase of about US$580 million.
Uncover why Semtech's fair value points to an 11% potential upside to its current price that could narrow quickly.
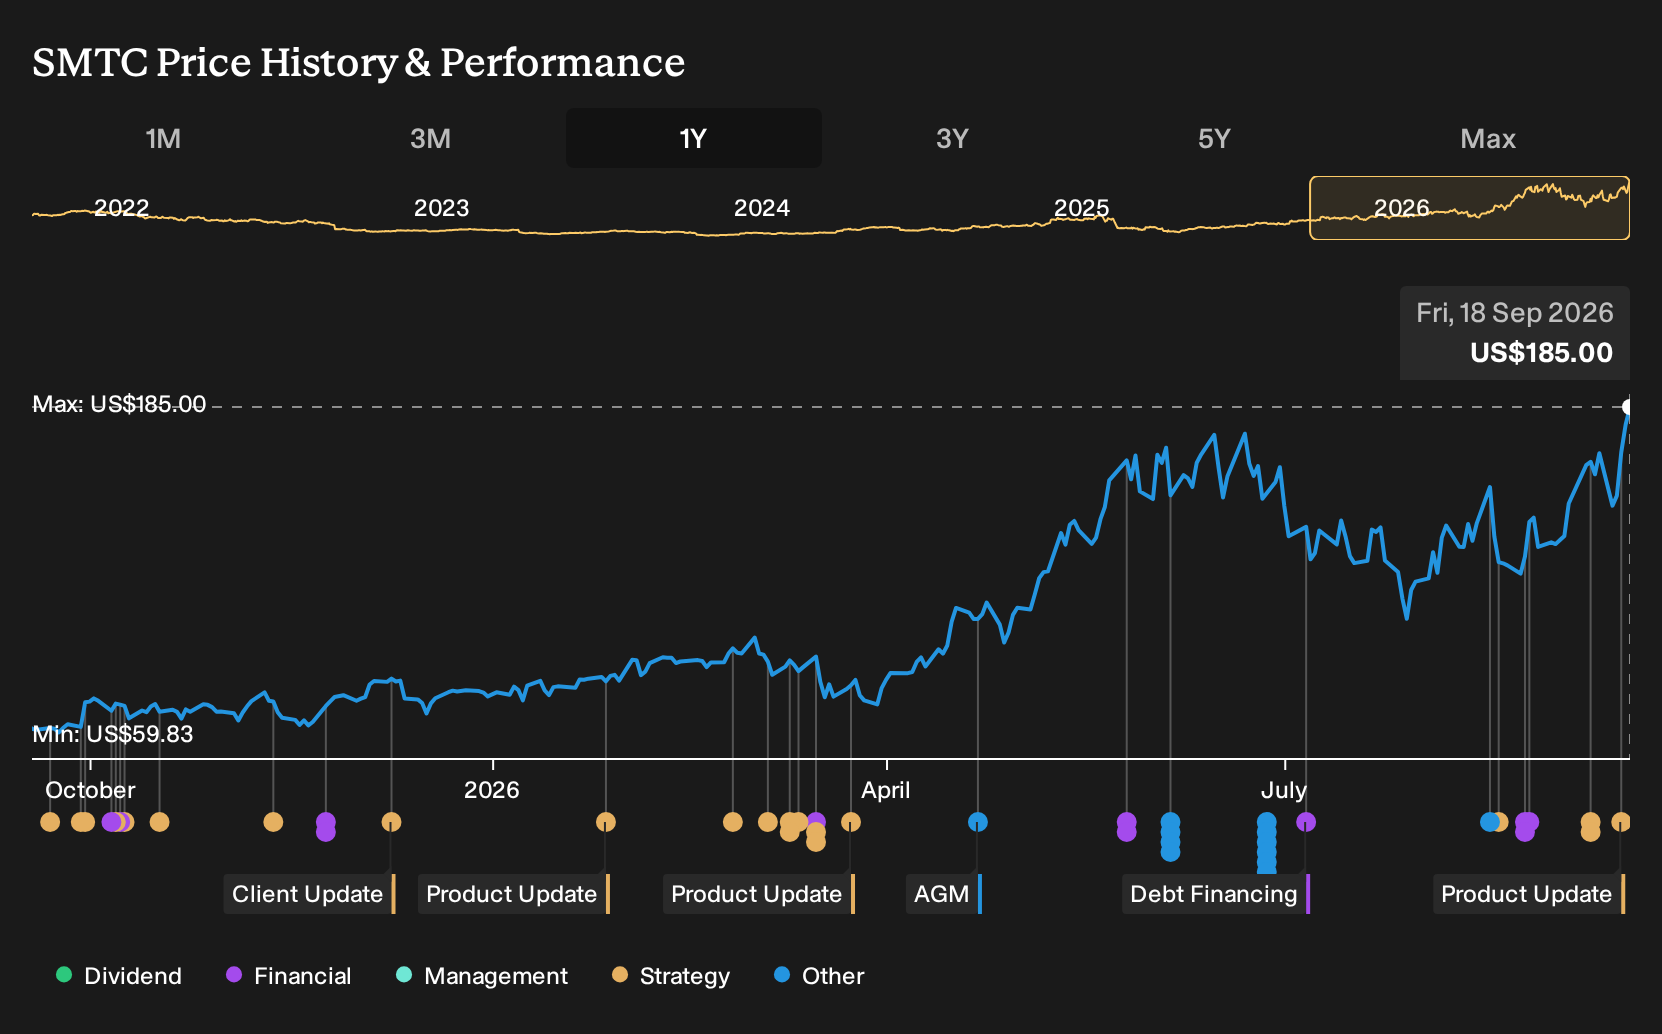
Exploring Other Perspectives
Some of the most optimistic analysts treat the new 10G PON chipset and Semtech’s broader connectivity push as fuel for a much steeper ramp. Before this news, the bullish camp was already modeling US$4.3b revenue and US$1.1b earnings by 2029. That is far above consensus, and it shows how sharply opinions can differ. You do not need to agree with either view today. However, it is worth exploring both before deciding how this round of product launches might reshape the story.
Explore 2 other Semtech fair value estimates, including one that suggests up to 13% upside from the current price.
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Semtech research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Semtech. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Semtech's overall financial health at a glance.
Looking For More Investment Ideas Beyond Semtech?
Once you have formed a view on Semtech, it can help to compare it with other opportunities that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener is built for exactly that kind of side by side work.
- If capital preservation ranks high on your list, start with a group of companies that screen as relatively resilient by reviewing 30 resilient stocks with low risk scores that may better match your tolerance.
- For investors hunting for quality at a reasonable entry point, broaden your watchlist with a carefully filtered 33 high quality undervalued stocks that combine stronger fundamentals with more attractive pricing.
- Those who care most about balance sheet strength can focus their research on a curated list of solid balance sheet and fundamentals (23 results) and see which businesses pair financial resilience with fundamentals that look robust.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com