
Will Robotic Hand Sensors Change ams OSRAM Stock Narrative
- Ams OSRAM has moved its optical force sensor technology into robotic hands, positioning these components as an alternative to incumbent piezoelectric solutions and highlighting their ability to keep force readings stable while relying on the company’s established automotive qualification standards.
- This expansion into robotics points to Ams OSRAM seeking new industrial end markets beyond its traditional automotive base. This development could influence product mix, capital allocation, and how investors think about the durability of its sensor demand across different hardware cycles.
- We will now look at how Ams OSRAM's investment narrative could shift as optical force sensors extend into robotic hand applications.
Scan how the robotics theme around ams-OSRAM fits into a wider opportunity set by comparing it with 95 robotics and automation stocks across automation, sensing, and industrial hardware demand.
What Is ams-OSRAM's Investment Narrative?
To be a shareholder in ams-OSRAM, you need to believe this optics specialist can convert its wide product portfolio into consistent, higher quality cash flows. The business currently generates €3,329.0m of revenue but reports a net loss of €324.0m and is expected to remain unprofitable for several years. That puts the focus squarely on execution, pricing discipline, and capital intensity. The move into optical force sensors for robotic hands fits this narrative as an attempt to deepen industrial demand beyond automotive, although on its own it is unlikely to shift the near term profit picture.
Short term, the story is still about stabilising margins, managing external borrowing and handling a highly volatile share price that has swung sharply over the past 3 months despite a 59.4% total return over the past year. Forecast revenue growth of 6.08% a year and a P/S of 0.5x, which screens as low against European semiconductor peers, give investors something to underwrite while the turnaround plays out. The robotics sensor push could help diversify end markets over time, but the core risk remains whether ams-OSRAM can close the gap between attractive sales metrics and sustained profitability.
That said, there is one structural issue in the background that could matter far more than any new sensor win...
There's only one way to know the right time to buy, sell or hold ams-OSRAM. Head to Simply Wall St's company report for the latest analysis of ams-OSRAM's Fair Value.
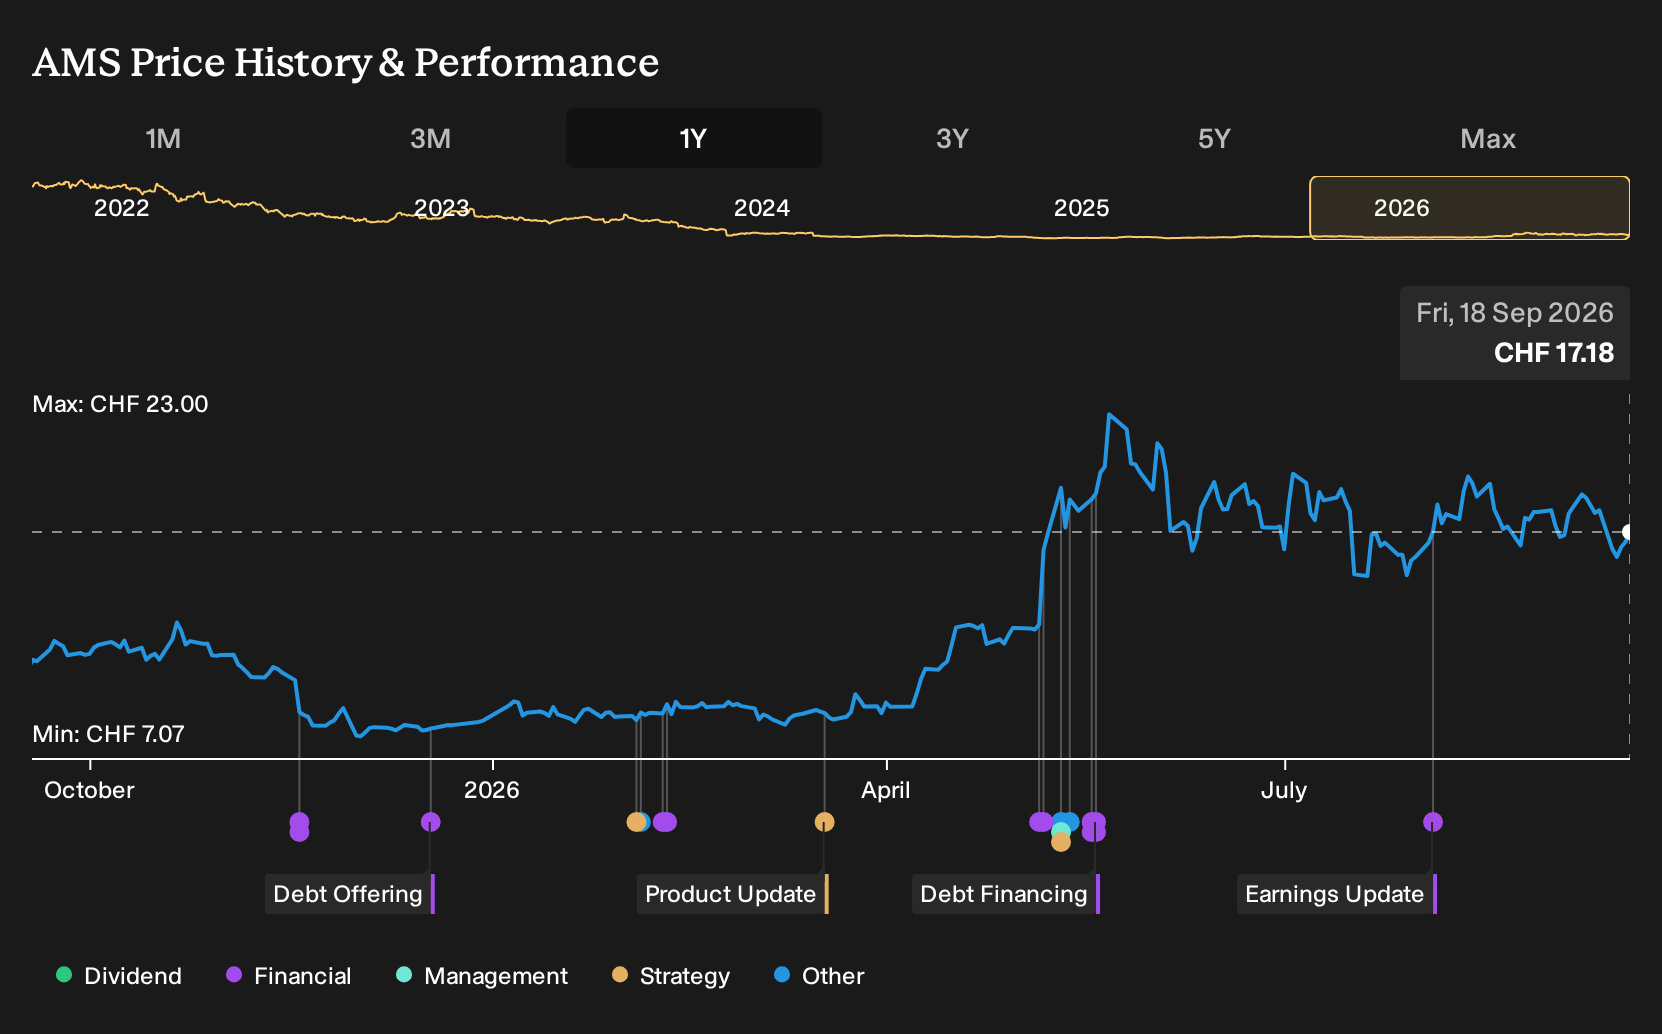
Exploring Other Perspectives
The two fair value estimates from the Simply Wall St Community span roughly €17.38 to €58.22, so you are looking at a wide gap in what different individuals think ams-OSRAM is worth. With the robotics sensor expansion not yet in those numbers, you can compare these contrasting views and decide which assumptions around future execution seem more realistic.
Explore another ams-OSRAM fair value estimate, including one that suggests it could be worth just CHF17.38.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your ams-OSRAM research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for ams-OSRAM. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate ams-OSRAM's overall financial health at a glance.
Looking For More Investment Ideas Beyond ams-OSRAM?
If the ams-OSRAM story has sharpened your thinking but you want a broader watchlist, the Simply Wall St Screener lets you apply the same disciplined approach across hundreds of other opportunities.
- For investors who want potential mispricing on their side, consider starting with 179 high quality undervalued stocks that combine strong fundamentals with comparatively low market expectations.
- If capital preservation matters to you as much as upside, filter for stability first by checking out 226 resilient stocks with low risk scores that score well on balance sheet strength and risk metrics.
- To widen your opportunity set beyond the usual blue chips, put some time into researching 612 high quality undiscovered gems that pair solid financial profiles with relatively low market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com