
3 US AI Infrastructure Stocks Worth Watching As Policy Shifts Capital
Washington now talks about an “AI tsar” and an “AI Force,” and that kind of political spotlight can reshape where capital and talent flow next. A looser regulatory tone around AI, cloud and data infrastructure may change how investors think about risk and reward across the sector. This article walks through three US AI and data infrastructure stocks that are exposed to that policy shift, and explains why their stories matter for your portfolio decisions.
The three stocks below are just a starting sample, and the full screen surfaced 43 more US-listed AI and data infrastructure companies with equally compelling narratives that are not covered here. To identify and analyze higher conviction opportunities across this wider group, head straight to the US-listed Artificial Intelligence and Data Infrastructure Stocks screener.
Ichor Holdings (ICHR)
Overview: Ichor Holdings designs fluid delivery subsystems that help semiconductor equipment makers produce advanced chips used in AI data centers and high-performance computing.
Operations: Ichor generates about US$1 billion from semiconductor equipment and services, with revenue concentrated in Singapore, the US, and other international markets.
Market Cap: US$2.1b
Ichor Holdings matters here because the fluid delivery hardware it supplies sits inside the tools that make AI chips. Product wins and design slots can influence future demand as chipmakers adjust capacity.
"The company is making material progress with the qualification and commercialization of new proprietary products like flow controllers and valves, which expand Ichor's addressable market and increase content per tool, providing a foundation for diversified and higher-margin revenues in future quarters as production ramps."
One risk factor is how any shift in a single pressure point could alter the balance between AI-related demand and the margins that support it.
That pressure point is exactly where Ichor Holdings gets interesting, so read the full narrative for Ichor Holdings to see how its content gains and policy risk are really interacting.

Cohu (COHU)
Overview: Cohu supplies semiconductor test equipment, automation, and AI driven analytics software that help chip makers qualify complex AI and data center processors.
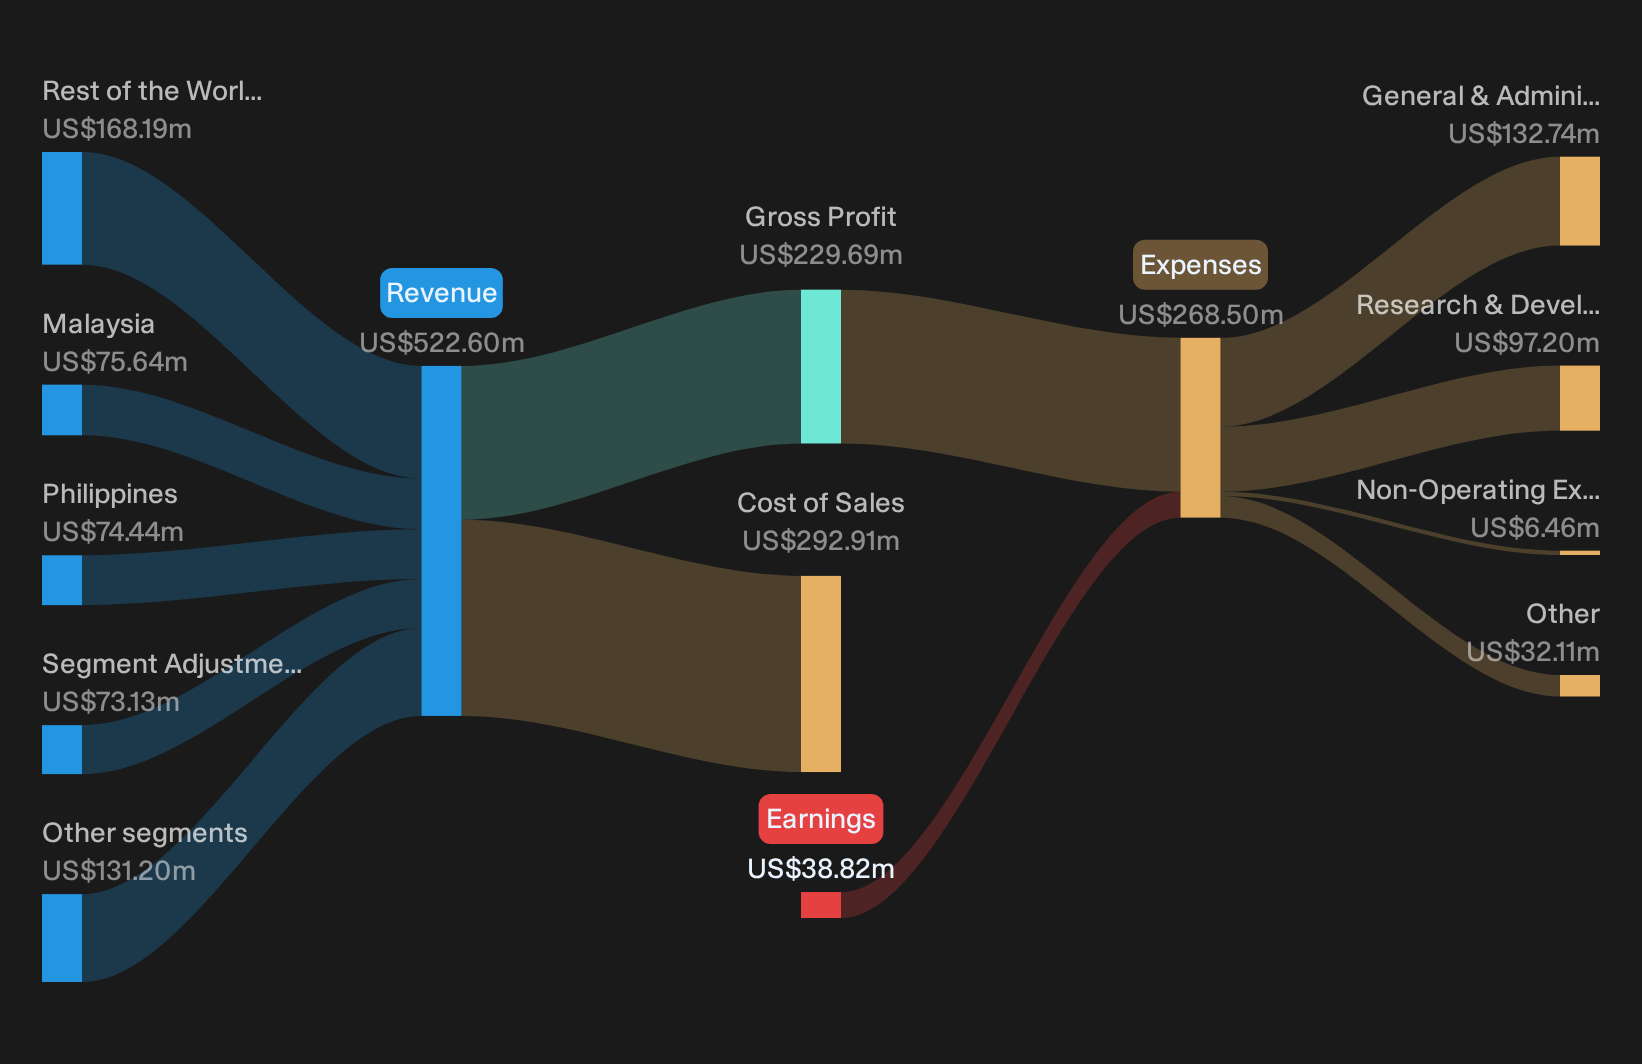
Operations: Cohu generates about US$522.6 million from semiconductor test and inspection equipment, with meaningful sales across China, Taiwan, Malaysia, the Philippines, and other regions.
Market Cap: US$2.7b
Cohu matters for this AI and data infrastructure screen because every high performance chip headed into servers or edge devices needs to be tested before it is trusted in the field.
"Cohu is capitalizing on the surge in high-performance computing and the complexity of modern semiconductors (AI infrastructure, GPUs, HBM, and display drivers). The company is rolling out advanced, configurable handler platforms and test solutions, which has positioned it to pursue market share gains and higher equipment sales, directly impacting top-line revenue."
What really moves the needle for Cohu is how one evolving demand driver shapes pricing power and profit potential over the next few years.
That pricing power question is exactly where things get interesting. Read the full narrative for Cohu to see how test demand, AI complexity and profitability are really interacting.
Penguin Solutions (PENG)
Overview: Penguin Solutions designs and manages high performance computing and AI infrastructure for enterprises, from GPU rich data center systems to edge deployments.
Operations: Penguin Solutions generates US$715 million from Integrated Memory, US$543 million from Advanced Computing, and US$244 million from Optimized LED products.
Market Cap: US$2.7b
Peguin Solutions sits squarely in the AI infrastructure story, building the hardware, memory, and software stack that turns GPU orders into running AI factories for real world customers.
"Accelerating adoption of AI and high-performance computing across major enterprise verticals (financial services, energy, biotech, federal, and neo-cloud providers) is driving robust demand for turnkey compute infrastructure, as evidenced by rising customer bookings and a diversified pipeline; this is likely to support sustained growth in revenue."
For investors, what happens to profitability if one pressure point shifts the mix between high margin services and more commodity style hardware will matter a lot.
That mix shift is exactly where the real story starts. Read the full narrative for Penguin Solutions to see how Penguin Solutions balances AI demand, pricing power and risk.

Seeking Alternatives Before The Crowd
Fresh themes move fast. Breakout momentum can be gone by the time headlines catch up, so scan these under the radar lists while it matters and consider them early.
- Spot sturdier balance sheets before volatility bites by running your filters through the list of solid balance sheet and fundamentals (23 results) curated from companies that already show financial discipline.
- Explore powerful income streams while yields are still elevated by checking the 6 dividend fortresses that focuses on businesses combining payouts with staying power.
- Track the next leg of AI momentum with the 38 profitable AI stocks that aren't just burning cash which highlights operators already turning AI demand into real earnings rather than just promises.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com