
Target Hospitality (TH) Raises Fresh Equity On An Undervalued Growth Narrative
Target Hospitality (TH) has moved back into focus after completing a US$259 million follow on equity offering at US$18.50 per share, increasing its common stock float.
That equity sale comes at a time when Target Hospitality’s momentum has been picking up, with a 30 day share price return of 24.35% and a year to date share price gain of 161.60%, contributing to a 1 year total shareholder return of 144.69% and a very large 5 year total shareholder return that suggests investors may already be pricing in a substantial amount of the story.
Compare Target Hospitality’s move with a curated group of companies showing sharp share price shifts and fresh catalysts using our 33 high quality undervalued stocks.
Target Hospitality has just raised fresh equity after a sharp run, so the puzzle now is whether that new capital supports more upside or whether most of the easy gains are already in the rearview mirror.
Most Popular Narrative: 11.7% Undervalued
Against the last close of $21.19, the most followed narrative on Target Hospitality pegs fair value at $24, which implies some upside once you accept its assumptions on growth, margins and discount rate.
Analysts are assuming Target Hospitality's revenue will grow by 45.1% annually over the next 3 years. Analysts assume that profit margins will increase from -10.8% today to 20.2% in 3 years time.
See why 2 investors see Target Hospitality as 12% undervalued.
Result: Fair Value of $24 (UNDERVALUED)
Still, the narrative could crack if data center commitments slow, or if political shifts change the pace and structure of Target Hospitality’s government related contracts.
Find out about the key risks to this Target Hospitality narrative.
Another View: Target Hospitality Through The Sales Lens
The SWS DCF model points to Target Hospitality trading 25.2% below an estimated future cash flow value of $28.34 per share, which fits with the 11.7% discount to the $24 fair value narrative. Yet the P/S ratio tells a very different story.
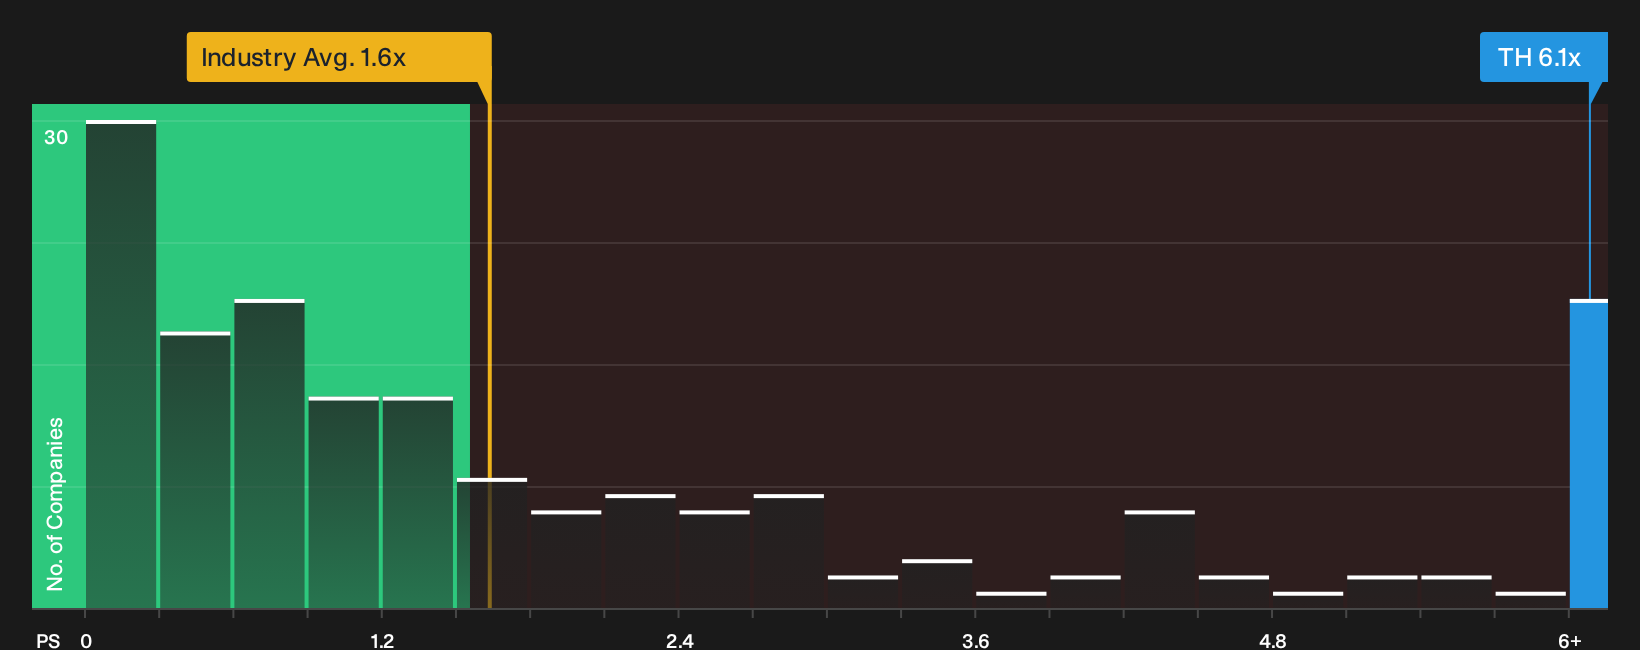
At 6.1x P/S, Target Hospitality screens far richer than the US Hospitality industry on 1.6x and peers on 1x, and it also sits above an estimated fair ratio of 4.1x that the market could eventually lean toward. If sentiment cools, how much multiple compression could shareholders be willing to tolerate before the DCF comfort zone feels less reassuring?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If the bullish tone around Target Hospitality feels compelling, move quickly from headline impressions to your own verdict by weighing the 2 key rewards.
Looking for more Target Hospitality sized ideas?
If Target Hospitality has sharpened your appetite for opportunity, do not stop here. Use focused screeners to uncover other setups that could fit your playbook.
- Chase high potential early movers by scanning the 8 elite penny stocks with strong financials that clear strict financial checks instead of relying on hype alone.
- Zero in on quality at a discount by sorting through the 33 high quality undervalued stocks that blend solid fundamentals with pricing that still looks reasonable.
- Prioritise resilience by filtering for the 30 resilient stocks with low risk scores that pair sturdier balance sheets with calmer return profiles when volatility spikes.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com