
nLIGHT (LASR) Faces Premium Valuation Scrutiny, Is The Stock Still Overvalued?
nLIGHT (LASR) is drawing fresh attention after a multi-year share price climb that has left the stock trading on a rich sales-based valuation compared with many laser industry peers.
Recent trading in nLIGHT has cooled. The 30-day share price return is down 15.58% and the 90-day move is down 38.45%, even though the year-to-date share price return is 3.83% and the 3-year total shareholder return is about 3x. This points to long term momentum but fading short term enthusiasm around a valuation that already prices in a lot of optimism.
Compare nLIGHT's rich P/S ratio with peers and hunt for other premium or overlooked laser and hardware plays using the curated 16 high quality undiscovered gems.
That mix of a three year share price surge and a sharp recent pullback leaves a simple dilemma. Does nLIGHT’s current premium valuation still offer enough upside to compensate for the hit if sentiment turns?
Most Popular Narrative: 56% Undervalued
On the most followed view, nLIGHT’s narrative fair value of $90.71 sits well above the last close at $39.84. This puts the recent pullback against a much higher long term earnings story built on defense lasers and advanced manufacturing exposure.
The rapid growth and expanding pipeline in aerospace and defense, particularly around high-power laser solutions (e.g., HELSI-2 program, DE M-SHORAD, Golden Dome initiative, and increased directed energy orders internationally), positions nLIGHT to benefit from rising global defense spending and modernization, supporting strong multi-year revenue growth.
Increasing adoption of advanced laser technologies for automation, smart manufacturing, and additive manufacturing (especially in high-growth EV, clean energy, and microfabrication segments) underpins long-term demand for nLIGHT's differentiated products, providing a runway for sustained top-line expansion.
See why 15 investors see nLIGHT as 56% undervalued.
Result: Fair Value of $90.71 (UNDERVALUED)
Still, nLIGHT’s heavy reliance on aerospace and defense programs, along with the execution risk in scaling amplifier manufacturing, leaves the upbeat narrative vulnerable if contracts slip or ramp-up stumbles.
Find out about the key risks to this nLIGHT narrative.
Another View: nLIGHT Looks Expensive On Cash Flows
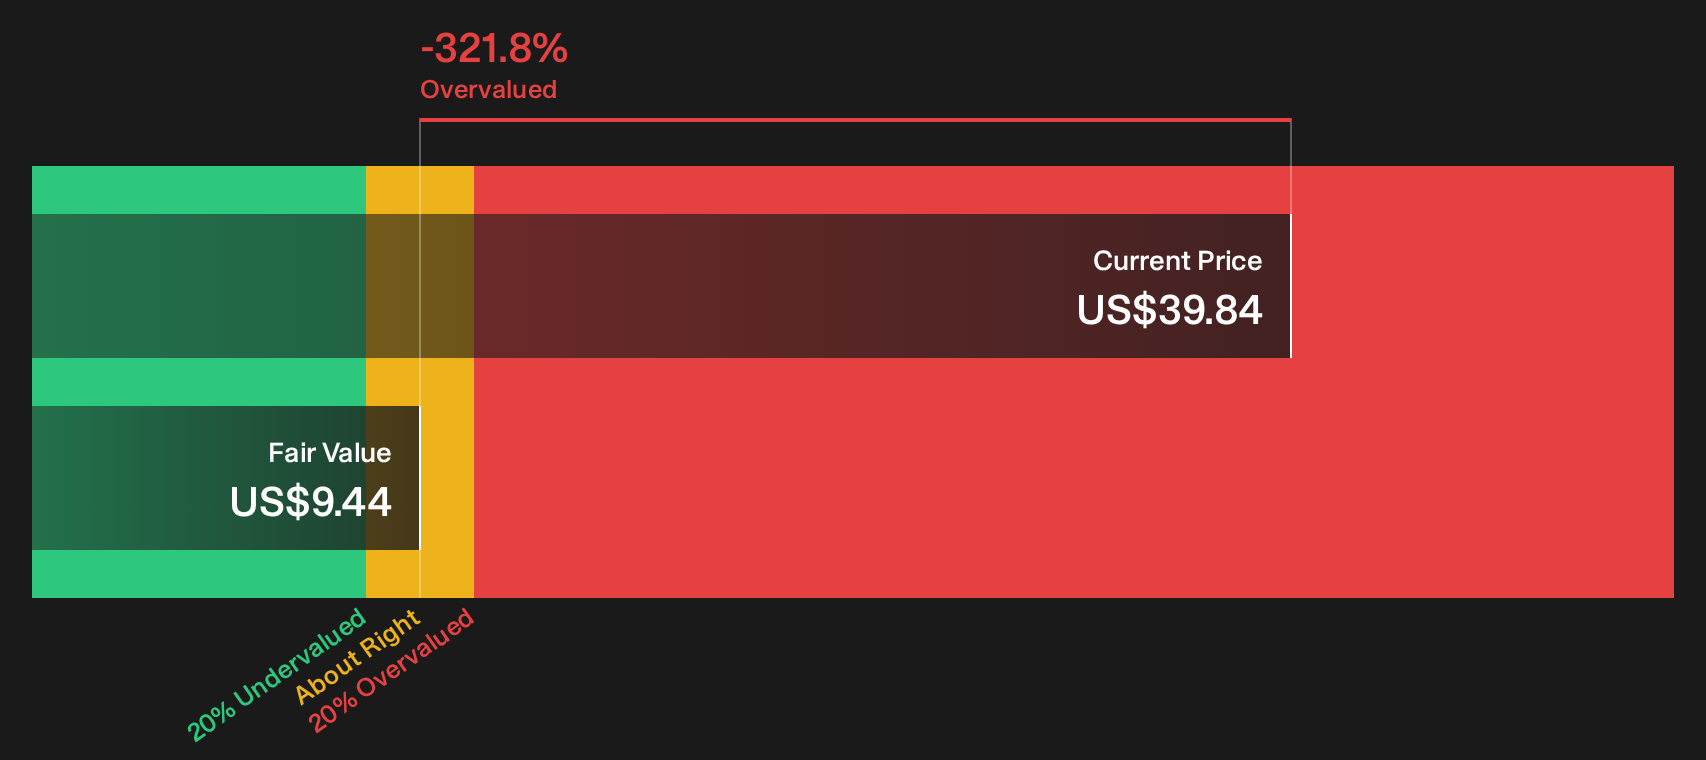
High-conviction narratives and analyst targets point to nLIGHT as 56% undervalued based on future earnings potential. The SWS DCF model paints a very different picture. On projected cash flows, nLIGHT’s estimated value is $9.44 per share, which makes the current $39.84 price look materially overvalued. Which story do you trust more: the long term growth path, or the cash in and out?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
The mixed tone around nLIGHT, part excitement and part hesitation, leaves the final call with you. Move quickly, study the full picture, and weigh both the upside narrative and the 2 key rewards and 3 important warning signs.
Looking for more investment ideas beyond nLIGHT?
If nLIGHT has your attention but you want a broader watchlist, use the screener to uncover other angles, sectors, and risk profiles you might be missing.
- Hunt for mispriced opportunities by scanning a curated pool of 33 high quality undervalued stocks that combine strong fundamentals with appealing entry points.
- Balance potential upside with sleep-at-night resilience by reviewing a 30 resilient stocks with low risk scores that screens for businesses with steadier risk profiles.
- Spot financially robust operators by filtering through a list of solid balance sheet and fundamentals (23 results) that highlights companies with stronger balance sheets and healthier fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com