
Vishay Intertechnology (VSH) Climbed, But What Is Drawing Fresh Attention?
Vishay Intertechnology (VSH) has introduced new high performance rectifiers, transient voltage suppressors, and an inductive position sensor, giving investors fresh product news to weigh against a sharply higher share price.
For context, Vishay Intertechnology’s share price has climbed strongly over 2026, with a year to date share price return of 112.62% and a 1 year total shareholder return of 115.43%. However, momentum has cooled recently, with the 90 day share price return down 49.91%.
Compare Vishay Intertechnology’s product driven story with other hardware-focused opportunities by screening for 38 power grid technology and infrastructure stocks, which could also benefit from demand for robust industrial and automotive electronics.
Vishay Intertechnology has shifted from sharp gains to a steep 90-day pullback, which leaves a simple question: Does the current valuation still compensate you for the product and cycle risks from here?
Most Popular Narrative: 19% Undervalued
At a last close of $32.51 versus a narrative fair value of $40, the current setup for Vishay Intertechnology prices in a hefty discount while the widely followed thesis leans on a multi year earnings rebuild and mix upgrade.
With major multi year investments in capacity expansion nearing completion, including readiness across nearly all product lines and the ramp of high growth, higher profit products, Vishay is well positioned to capture share as demand accelerates in areas like AI, smart grid infrastructure, data centers, and automotive electrification, supporting higher future revenues and improved operating leverage.
See why 10 investors see Vishay Intertechnology as 19% undervalued.
Result: Fair Value of $40 (UNDERVALUED)
Still, heavy capacity spending with negative free cash flow and persistently low operating margins at Vishay Intertechnology could derail the multi year earnings rebuild that investors are banking on.
Find out about the key risks to this Vishay Intertechnology narrative.
Another View: Vishay Intertechnology Through The Sales Lens
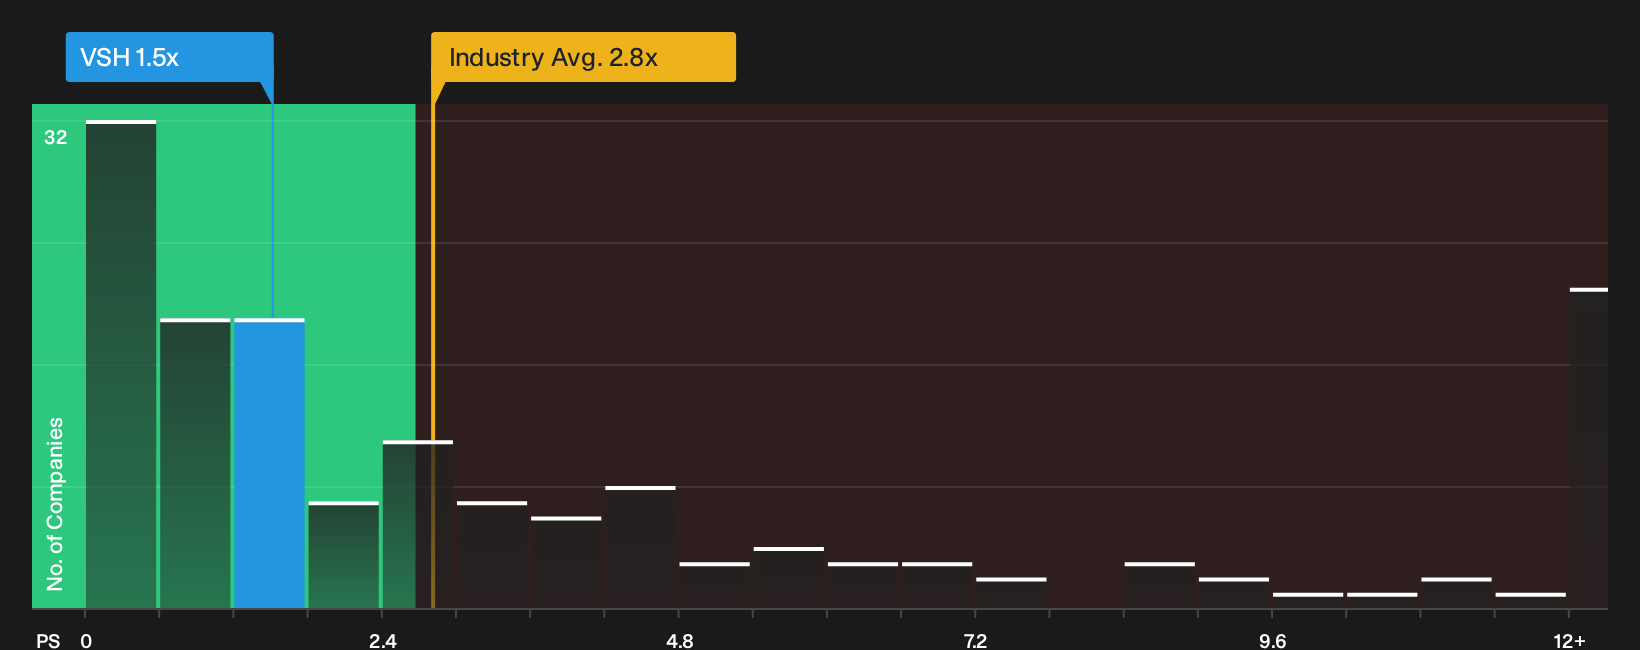
There is a twist. While the SWS DCF model flags Vishay Intertechnology as trading about 43.7% below an estimated future cash flow value of $57.77, the market is already asking for a P/S of 1.5x versus a fair ratio of 1.3x.
That current P/S is cheaper than the US Electronic industry on 2.8x and peers at 3.2x, yet still ahead of where the fair ratio suggests the multiple could drift over time. Is this a margin of safety or a sign that expectations already run hot?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Vishay Intertechnology can pull you in either direction, so move quickly to stress test the data and weigh both the 3 key rewards and 2 important warning signs in 3 key rewards and 2 important warning signs.
Looking For More Ideas Beyond Vishay Intertechnology?
Do not stop your research with Vishay Intertechnology. Use the Simply Wall Street screener to pressure test your thesis and line up your next watchlist candidates.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (23 results) that can handle tougher conditions without constant drama.
- Hunt for mispriced opportunities by working through the 33 high quality undervalued stocks that combine quality metrics with prices that still look reasonable on the numbers.
- Prioritise stability and lower volatility by checking out the 30 resilient stocks with low risk scores that could help anchor a portfolio when sentiment turns.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com