
Realty Income (O) Expands In Europe As Fair Value Stays In Focus
Realty Income (O) just announced a new euro joint venture with KKR that is expected to hold European net lease assets, giving investors fresh data to think about the REIT’s international footprint.
Realty Income’s share price has drifted lower in recent weeks, with a 30-day share price return down 9.99% and a 7-day move down 4.77% to about $56.66. At the same time, the 1-year total shareholder return is still up 1.0% and the 3-year total shareholder return sits at 29.83%, suggesting long term holders have seen steadier progress than the current soft momentum implies.
Capitalize on Realty Income’s latest European move by scanning a curated 33 high quality undervalued stocks that combine dependable cash flows with balance sheets built to weather softer share price momentum.Realty Income now has a larger European platform, a long dividend record, and a softer share price in the short term. The key question is whether that combination results in a fair valuation today.
Most Popular Narrative: 9% Undervalued
Realty Income last closed at $56.66, while the most followed narrative fair value sits at $62.11. This puts the shares at a modest discount that investors are weighing against a long running dividend track record.
Overall it seems Realty Income is fairly valued or at most a little undervalued at its current market price.
Fair Value: $62.11
See why 92 investors see Realty Income as 9% undervalued.
Result: Fair Value of $62.11 (UNDERVALUED)
Still, higher funding costs or weaker tenant demand for Realty Income’s European assets could pressure acquisition economics and challenge the current fair value story.
Find out about the key risks to this Realty Income narrative.
Another View on Realty Income’s Valuation
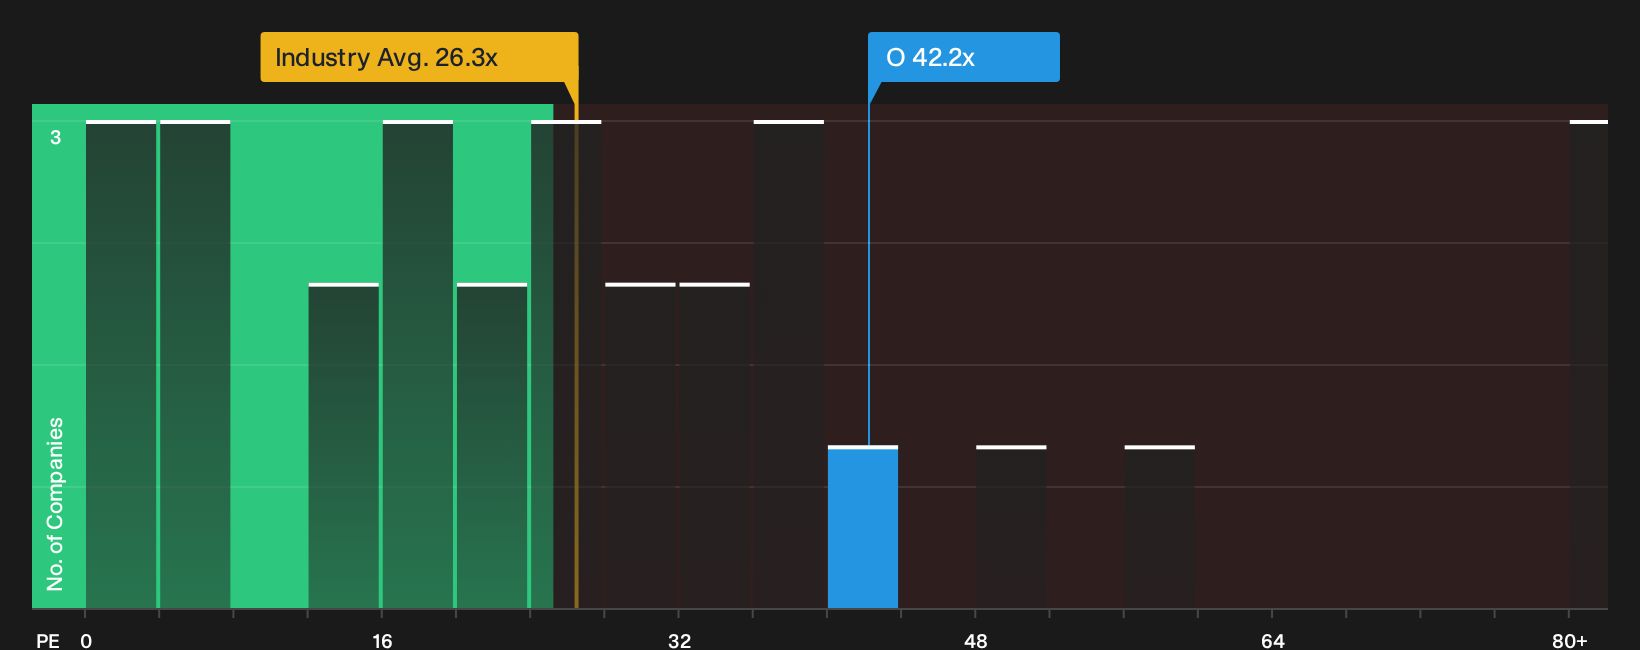
The fair value narrative around Realty Income leans on discounted dividend and cash flow work, yet the current market multiple tells a tougher story. The stock trades on a P/E of 42.2x, while the US Retail REITs group averages 26.3x and the fair ratio sits at 36.6x.
That gap suggests investors are already paying a premium for Realty Income compared with both peers and where the fair ratio implies the P/E could move. This raises a simple question: Is the comfort of the dividend record worth that extra multiple risk at today’s price?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the Realty Income story today. Move quickly through the numbers and sentiment, then weigh both sides with 5 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Realty Income?
If Realty Income has your attention, do not stop there. A broader watchlist gives you more options when prices or narratives shift.
- Target higher potential upside by scanning a focused group of 8 elite penny stocks with strong financials with stronger balance sheets than many traders expect in the lower price ranges.
- Strengthen your income stream by reviewing a curated set of 6 dividend fortresses that aim to pair yield with fundamental resilience.
- Protect your downside risk by zeroing in on a 30 resilient stocks with low risk scores that highlights businesses with sturdier financial profiles and calmer price moves.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com