
Learn Why The Bull Case For e.l.f. Beauty Stock Could Change Following Sephora Expansion
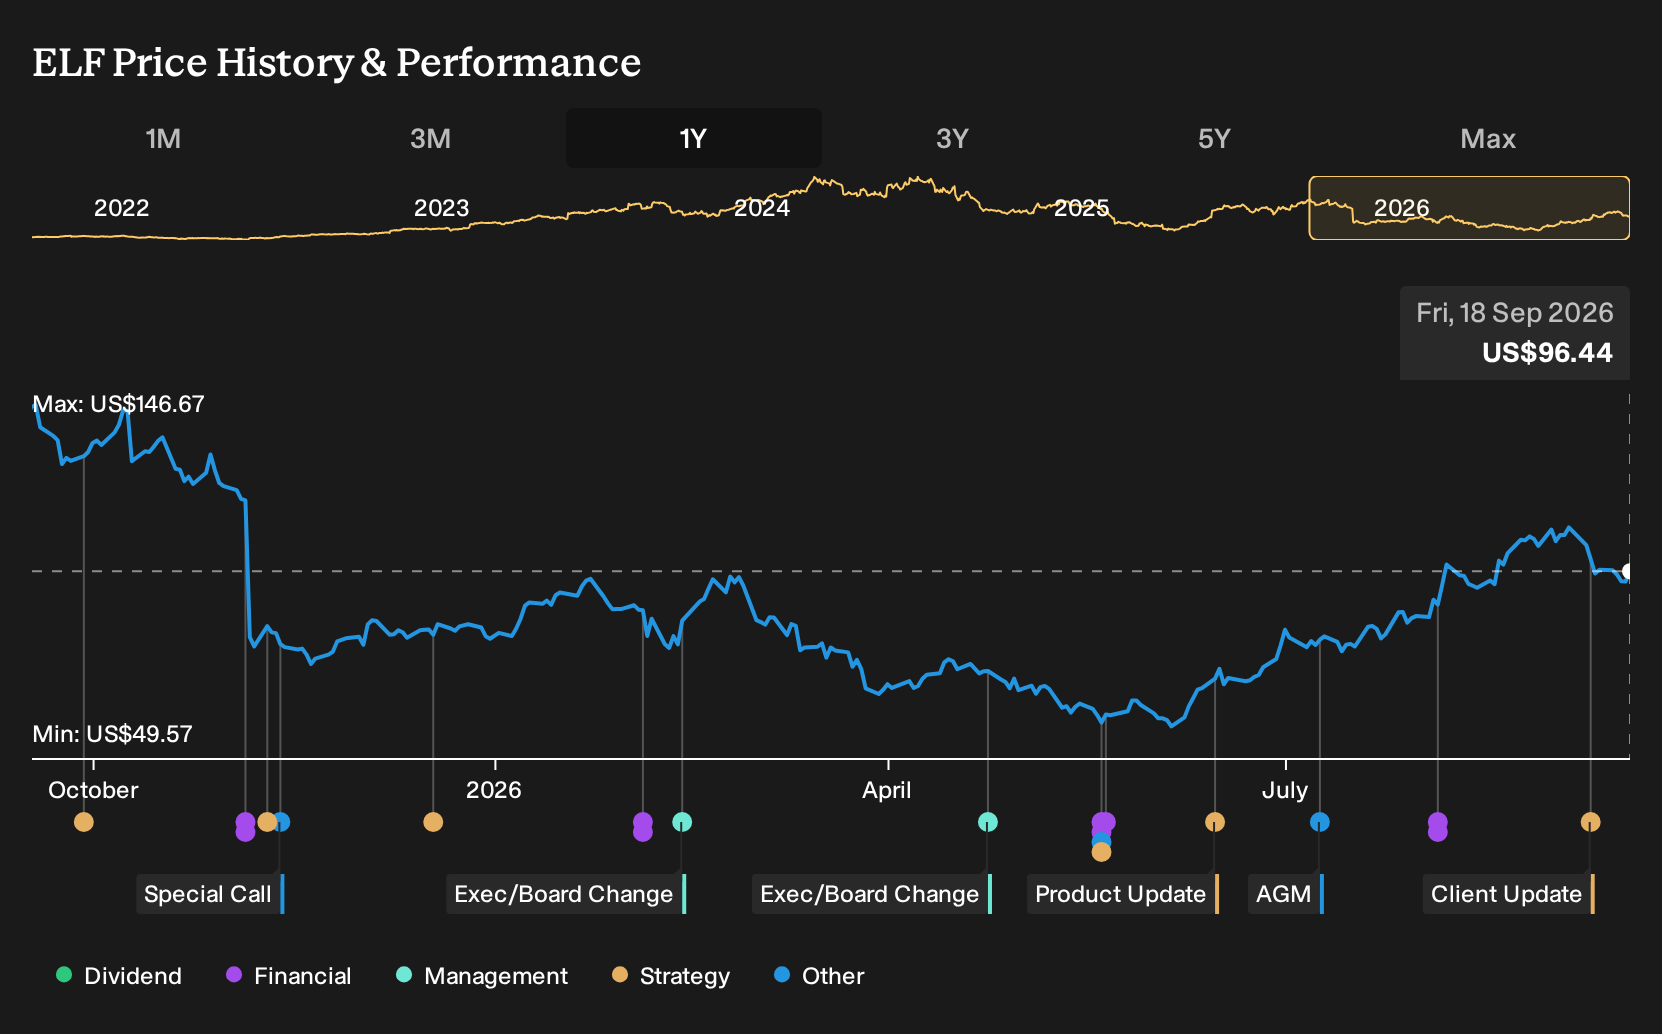
- In September 2026, Naturium announced its rollout with Sephora across Canada and Mexico, while e.l.f. Cosmetics became the first mass color brand in Sephora Brazil, broadening e.l.f. Beauty's reach across North and South America.
- The wider Sephora footprint gives e.l.f. Beauty and Rhode a larger physical and online shelf presence, which can test pricing power, marketing efficiency, and operational execution across multiple regions and retail formats.
- We will now look at how e.l.f. Beauty's broader Sephora footprint shapes the existing investment narrative around international expansion.
e.l.f. Beauty Investment Narrative Recap
For an investor to stay with e.l.f. Beauty, the core belief is that international expansion and brand layering can justify heavy investment while margins recover from recent compression. The Sephora rollout gives the group more levers for revenue, but it does not directly change the near term focus on rebuilding profitability from a 3.4% net margin and managing tariff exposure.
The key near term catalyst remains execution on global distribution and digital efficiency that can support the forecast 28.3% annual earnings growth without stretching the balance sheet further. The biggest risk continues to be rising costs from China centered sourcing and elevated SG&A that could limit the benefit of new shelf space.
The Rhode acquisition sits closest to this latest Sephora news. Rhode's planned reach into 19 European countries and about 500 Sephora stores runs in parallel with Naturium's rollout in Canada and Mexico and e.l.f. Cosmetics' entry into Sephora Brazil. Together, these steps concentrate a lot of the growth story in one retail partner.
For you, the question is whether e.l.f. Beauty can turn that broader Sephora exposure into sustainable earnings without letting tariffs, marketing spend, or competition erode returns. Execution risk is real, especially with current profit margins lower than last year, but the international footprint now gives management more operational levers to work with.
e.l.f. Beauty's current analyst narrative points to forecast revenues of US$2.3b and earnings of US$191.4 million by 2029, based on an assumed 9.8% yearly revenue growth rate and an earnings increase of about 3.2x from US$59.6 million today.
Uncover why e.l.f. Beauty's fair value indicates a 6% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate view leans hard into international upside. Those bullish analysts were already modeling US$2.5b of revenue and US$220.2 million of earnings by 2029, before this Sephora news. You might see this rollout and wonder if their more optimistic global mix and higher margin path start to look less extreme.
Explore 3 other e.l.f. Beauty fair value estimates, including one that suggests as much as 28% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your e.l.f. Beauty research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for e.l.f. Beauty. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate e.l.f. Beauty's overall financial health at a glance.
Looking For More Investment Ideas Beyond e.l.f. Beauty?
If this e.l.f. Beauty story has sharpened your thinking on brand scale, margins, and balance sheet strength, it can be useful to compare it with other businesses that share similar financial traits or offer very different risk and reward profiles.
- For investors who want potential mispricing with underlying quality, scan through 16 high quality undiscovered gems that pair solid fundamentals with lower market attention.
- If capital preservation sits high on your priority list, focus on resilience first by reviewing 30 resilient stocks with low risk scores that score well on financial stability and risk measures.
- Income focused portfolios can look beyond headline yield and study 6 dividend fortresses that combine higher payouts with balance sheets and cash flows that help support those distributions.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com