
Affordability Pressures Might Change The Case For Investing In D.R. Horton (DHI)
- D.R. Horton recently opened sales at Summervale in Frederick, Maryland, a master-planned community with around 296 homesites and a mix of townhomes and single family layouts that include its Smart Home Technology package.
- Alongside this expansion, the builder faces sector pressures such as affordability issues and softer demand signals, with backlog contraction and earnings per share declining 16% annually over the last two years.
- The focus now turns to how D.R. Horton’s investment narrative holds up against affordability pressures highlighted by Lennar and D.R. Horton’s backlog contraction.
D.R. Horton Investment Narrative Recap
D.R. Horton appeals to shareholders who think the structural U.S. housing shortage and demand for entry level product can offset near term softness. To stay comfortable, you need to believe the firm can work through backlog contraction, softer orders and a 16% annual EPS decline over the last two years without letting profitability deteriorate sharply.
The key near term swing factor is affordability pressure, which is already hitting peers like Lennar and pushing D.R. Horton to lean on incentives. The biggest risk is that incentives, higher land costs and competition squeeze margins faster than any benefit from scale, operational efficiency or product mix can help.
The Summervale opening in Frederick looks most relevant right now. It shows D.R. Horton is still rolling out communities that target a mix of townhomes and single family buyers, which aligns with its focus on affordable and first time households that made up a large share of recent mortgage closings.
For you, the question is whether communities like Summervale offset backlog declines and demand headwinds or simply maintain volume. Execution on absorption, pricing and incentives at these new projects will help indicate if the current housing cycle is pressuring margins more quickly than the business can respond.
D.R. Horton’s current earnings are described at about $3.1b, with analysts expecting earnings of $4.4b by 2029, which implies an increase of roughly $1.3b in profit. Consensus forecasts point to revenue of $42.2b by 2029, based on an assumed 8.2% yearly revenue growth rate from today’s levels.
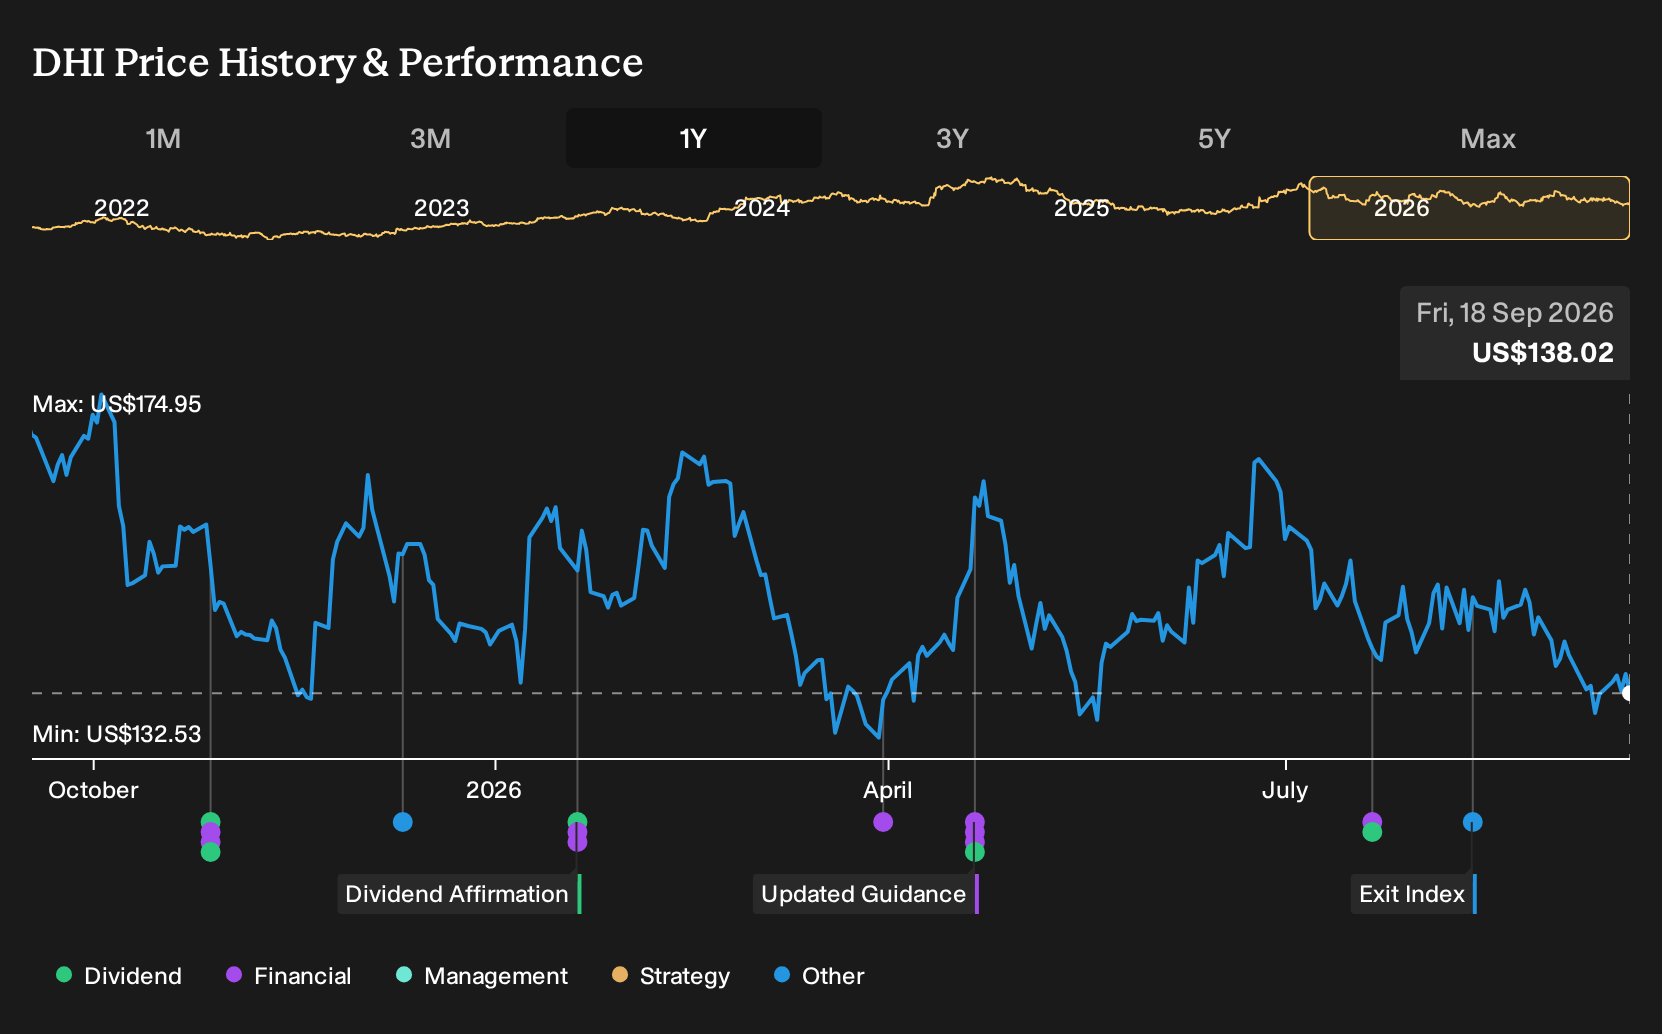
Uncover why D.R. Horton's fair value indicates a 17% potential upside to its current price, a gap that could narrow quickly for patient investors.
Exploring Other Perspectives
One alternative view leans hard into affordability risk. The most pessimistic analysts expect D.R. Horton to reach only about $38.2b of revenue and $3.6b of earnings by 2029, compared with consensus at $42.2b and $4.4b. These forecasts were set before the Summervale news, so you should treat them as living rather than fixed narratives.
Explore 3 other D.R. Horton fair value estimates, including one that suggests as much as 9% downside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your D.R. Horton research is our analysis highlighting 2 key rewards that could impact your investment decision.
- See our latest analysis for D.R. Horton. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate D.R. Horton's overall financial health at a glance.
Looking for more D.R. Horton style investment ideas?
Once you understand where D.R. Horton fits in your portfolio, it often helps to scan a wider set of opportunities that share similar financial strengths or risk profiles. The Simply Wall St Screener makes it easier to filter for traits that matter to you instead of chasing every headline.
- If you care most about valuation combined with quality, review a curated set of 33 high quality undervalued stocks that pair solid fundamentals with potentially attractive pricing.
- For investors who want balance sheet strength to be the first line of defense, filter for a list of solid balance sheet and fundamentals (23 results) that can better withstand pressure when conditions get tougher.
- Those hunting for stability with income potential can scan a selection of 6 dividend fortresses that combine higher yields with supporting fundamentals.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com