
3 Fuel Logistics Stocks Worth Watching As Energy Market Stress Builds
War-driven energy shocks, warnings about structural stress in the US economy, and questions around the Strategic Petroleum Reserve have pushed fuel markets back to center stage. That mix can punish broad equities while creating pockets of potential in less obvious corners. This piece looks at how those risks intersect with oil refiners and fuel logistics operators and highlights three stocks exposed to this news that investors may want to keep on their radar.
The stocks covered below are just a starting sample, and the full screen surfaced 24 more companies with equally compelling fuel refining and logistics narratives that are not covered in this article.
To go deeper into this theme, head straight into the Oil Refiners and Fuel Logistics Operators screener to identify potential opportunities, compare fundamentals, and analyze which refiners and fuel logistics operators best fit your own highest conviction ideas.
Verbio (XTRA:VBK)
Overview: Verbio produces and distributes bio-based fuels and related products worldwide, giving investors direct exposure to refined fuel markets.
Operations: Verbio generates most of its revenue from biodiesel at €918.9 million and bioethanol including biomethane at €845.2 million, plus €35.9 million from other activities.
Market Cap: €1.9b
Verbio plugs straight into the screener theme because it sells low carbon fuels into the same refuelling networks that move diesel and gasoline, so its fortunes are closely tied to fuel pricing, policy and logistics, not just pure energy sentiment.
"The anticipated tightening of biofuel supply as higher-cost competitors reduce output, combined with gradual policy improvements, such as stricter fraud controls and quota increases, across Europe is likely to support a material recovery in greenhouse gas (GHG) quota prices, directly impacting Verbio’s revenue and EBITDA as each €1 rise in quota price increases annual EBITDA by €1 million."
What happens to Verbio’s margins if a single key assumption in that policy and pricing backdrop bends rather than breaks?
If that policy cushion gives way, read the full narrative for Verbio to see how Verbio’s earnings profile could still accelerate or stall under different quota and pricing paths.

Sable Offshore (SOC)
Overview: Sable Offshore runs offshore oil and gas platforms and subsea pipelines off California, linking offshore production into onshore processing facilities.
Market Cap: US$835 million
Sable Offshore gives you upstream hydrocarbon exposure that feeds the same fuel system refiners and logistics operators depend on. The recent court-backed green light for its California pipeline operations highlights how a single regulatory decision can shift how much production volume actually flows into that system if one unseen pressure moves again.
If that regulatory pivot is what interests you, review the 3 key rewards and 2 important warning signs (2 are major!) to see how courts, volumes and valuation could be decoupling for Sable Offshore.

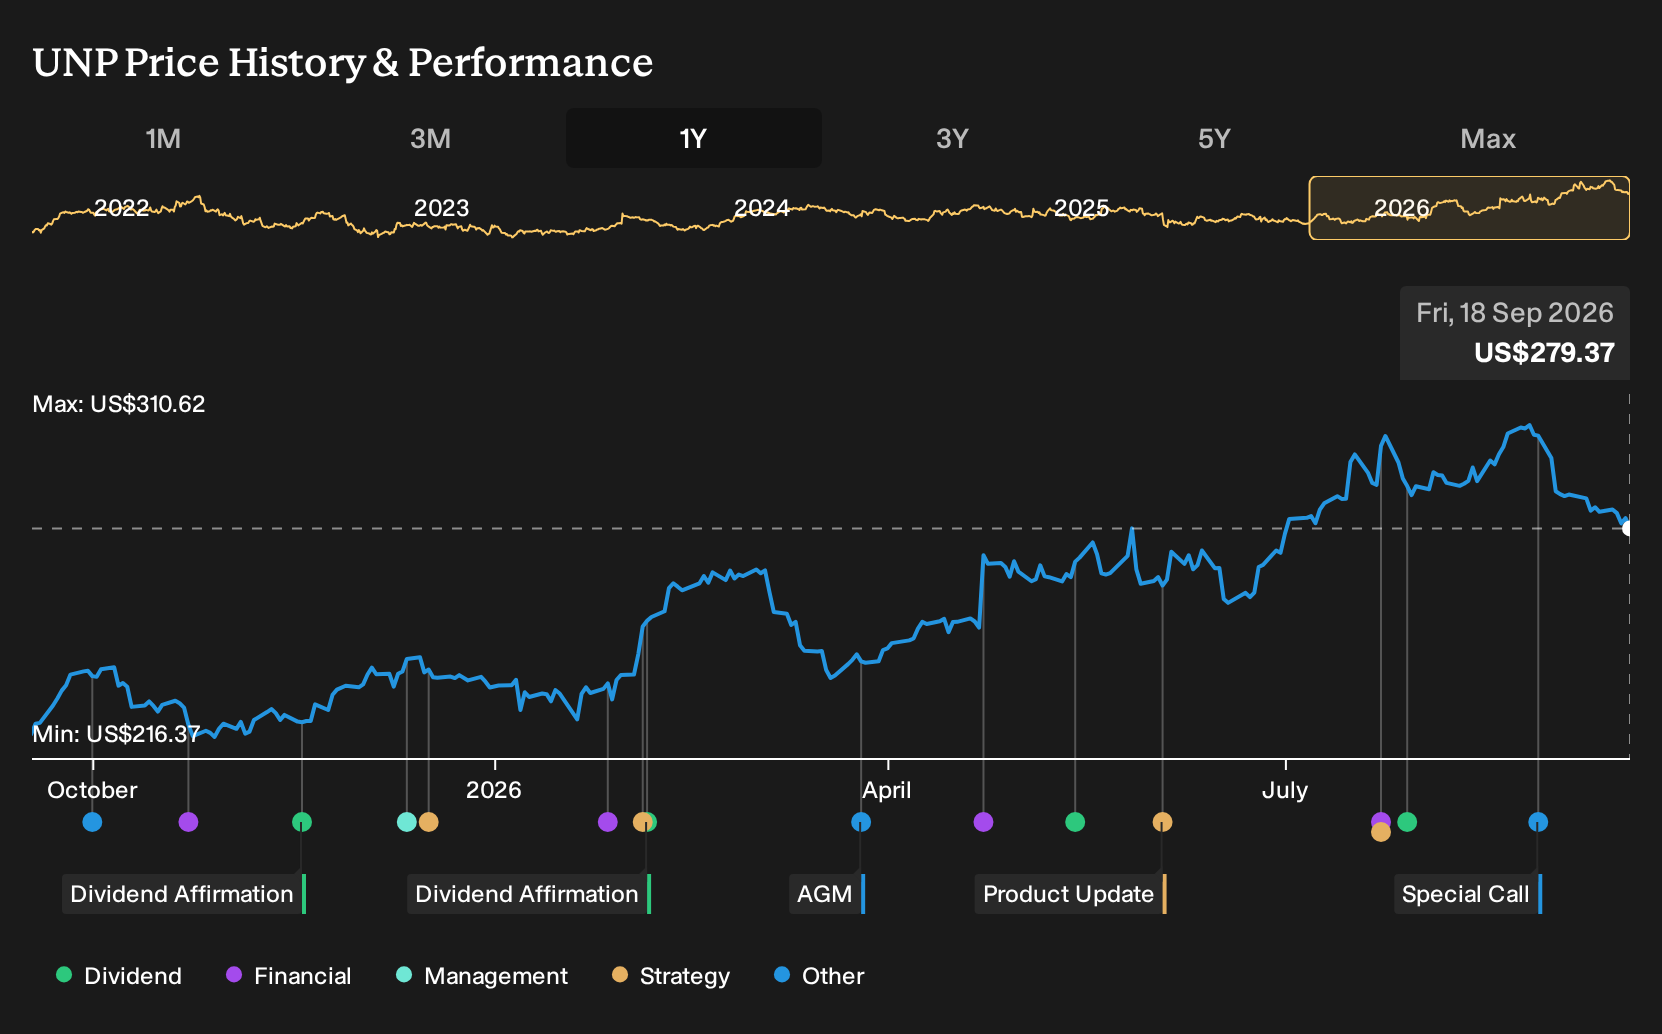
Union Pacific (UNP)
Overview: Union Pacific runs one of the largest US freight rail networks, moving fuel, industrial goods, and consumer products across key trade corridors.
Operations: Union Pacific generates all its US$25.41b revenue from railroad services, with about US$22.41b in the United States and US$3b in Mexico.
Market Cap: US$167.81b
Union Pacific matters in this fuel-focused screen because its rail network hauls refined products and petroleum-related freight that still need to move even when energy shocks make trucking more expensive.
"Union Pacific is implementing multiple efficiency enhancements, such as energy management systems for locomotives and optimization tools, which are expected to improve operational efficiency and net margins."
The real swing factor is how one unresolved regulatory decision shapes the economics of hauling more high value, energy-linked volumes across that network.
That hinge point on higher value energy freight is exactly what the full narrative for Union Pacific unpacks, including how efficiency gains could be masking a bigger upside swing.
Seeking Fresh Alternatives Beyond Fuel?
Fresh breakout themes get spotted, momentum builds, then the best entry points vanish as prices start flying. Scan these curated ideas before the crowd catches up and consider them while they may still fit your strategy.
- Target reliable income streams by scanning a curated pool of resilient payers through the 155 dividend fortresses while yields still look appealing and risk scores remain in focus.
- Hunt for growth with guardrails by checking the list of solid balance sheet and fundamentals (198 results) so you focus only on businesses with sturdy finances while they are still under the radar.
- Ride structural technology momentum by reviewing the 88 AI infrastructure stocks before capital increases and potential entry prices move away from your ideal range.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com