
AtriCure (ATRC) Stock Looks Pricey Against Its Sales Base
AtriCure shares have enjoyed a strong run over the past year, which naturally raises a question for anyone looking at the chart. Is the current price level adequately supported by what the business is actually generating in sales?
- The stock has returned 59.5% over the past year, which puts real weight on whether recent enthusiasm lines up with the revenue base behind it.
- The company’s focus on treating cardiac arrhythmias means future sales can depend heavily on how effectively it converts clinical adoption into consistent, recurring procedure volume.
- There is a second opinion on AtriCure worth weighing. See what analysts think AtriCure's shares could be worth.
The issue now is whether AtriCure’s current share price is well supported by its sales when set against the Fair Ratio benchmark.
If you are weighing whether AtriCure’s 59.5% 1 year return aligns with its sales, it can help to compare that question with other companies in the 33 high quality undervalued stocks
Has AtriCure Run Too Far on Sales?
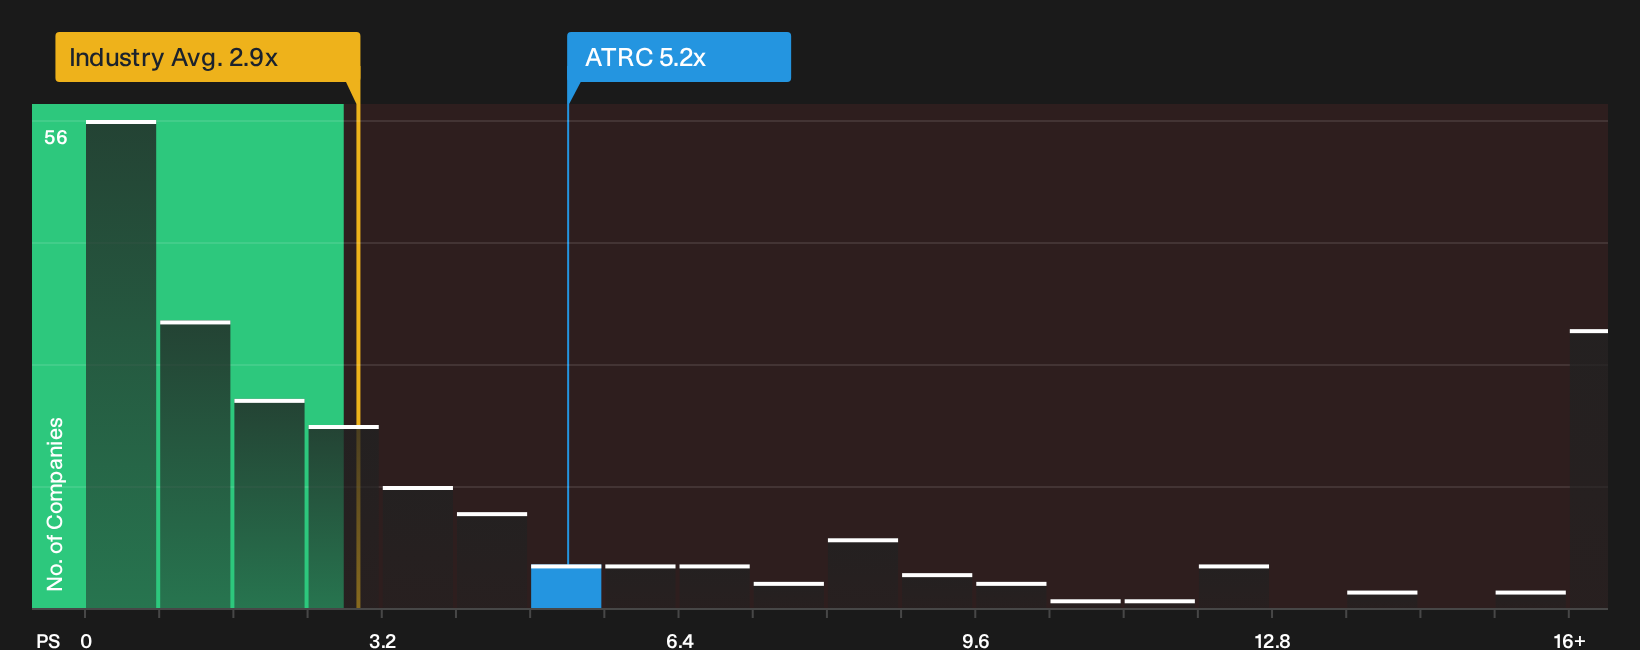
P/S is a useful cross check for AtriCure because the business is still primarily being weighed on its ability to turn procedure demand into revenue rather than earnings. The stock trades on a P/S of 5.2x, which is well above the Medical Equipment industry average of 2.9x and also higher than the peer group on 9.0x.
The Fair Ratio framework, which ties the multiple back to factors like growth profile, profitability, competitive position and risk, points to a lower P/S level than where AtriCure currently trades. That gap indicates the market is paying a premium for each dollar of sales. Any investor considering the recent share price move needs to judge whether the company’s commercial execution and product adoption justify that higher revenue multiple. Explore the numbers behind AtriCure's P/S valuation.
The AtriCure Narrative: What Would Justify Today's Price?
Narratives on Simply Wall St pick up where the AtriCure valuation puzzle leaves off. They spell out which future paths for growth, margins and earnings would need to play out for the current share price to look stretched or conservative. Instead of one static ratio or model output, these scenarios describe the future that number rests on so you can watch how AtriCure's actual progress lines up with those assumptions over time.
Community views on AtriCure split between those who see underappreciated upside and those who think expectations now run a bit hot.
Bull case: 9% undervalued
"Bullish analysts see the new STS Quality Metric as a key support for higher EnCompass Clamp use in cardiac surgery, which they link to a larger addressable opportunity for AtriCure within U.S. atrial fibrillation procedures…"
Discover why this Narrative puts AtriCure at 9% undervalued.
Bear case: 12% overvalued
"More cautious analysts focus on competitive risk after the FDA clearance of Edwards Lifesciences’ ECLIPTIS left atrial appendage exclusion system, which is positioned to compete directly with AtriCure’s open AtriClip platform…"
Explore why this Narrative puts AtriCure at 12% overvalued.
One More AtriCure Angle That Could Change Your View
AtriCure’s valuation story only goes so far without weighing the specific risk checks that recent research has flagged for the business, and those are worth understanding before you decide what the current price really implies. Take a closer look at 1 warning sign before settling on a valuation.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com