
Macerich (MAC) Sees Fresh Leasing Momentum, Is The Stock Cheap?
Macerich (MAC) is back in focus after management appeared at the BofA NY Global Real Estate Conference, outlining fresh leasing momentum, consumer traffic trends, and plans for new store commitments across its mall portfolio.
Recent action around Macerich reflects this story playing out in real time. The share price has risen 22.19% year to date and the 1-year total shareholder return is 34.05%, while a 30-day share price return of down 9.12% suggests enthusiasm has cooled even as the 3-year total shareholder return of 125.09% and 5-year total shareholder return of 58.32% keep the longer record firmly positive.
Scan for other real estate stocks showing similar traffic and leasing momentum to Macerich by checking our hand picked list of solid balance sheet and fundamentals (23 results)
Macerich now trades below both analyst targets and an estimated intrinsic value, while the share price has cooled after a strong multiyear run. Is that a margin of safety or a warning sign?
Most Popular Narrative: 15% Undervalued
Macerich last closed at $22.63, while the most followed narrative pegs fair value at $26.63, which frames the stock as trading at a discount and puts more weight on execution than on current earnings.
Accelerated leasing activity, including a record pace of new deal signings and strong LOI pipeline, is driving higher leasing spreads and sustained tenant demand; this supports significant NOI and revenue growth as new tenants open and backfilled spaces (especially former Forever 21) achieve higher rental rates. The focus on experiential and destination-oriented retail (e.g., DICK'S House of Sport, Cheesecake Factory, entertainment concepts) is revitalizing consumer engagement and increasing traffic, positioning the portfolio to benefit from experience-driven spending and capturing higher net margins over time.
See why 1 investors see Macerich as 15% undervalued.
Result: Fair Value of $26.63 (UNDERVALUED)
Still, the narrative around Macerich depends on heavy leverage and concentrated exposure to challenged retail markets not turning refinancing or tenant stress into a drag.
Find out about the key risks to this Macerich narrative.
Another View on Macerich’s Valuation
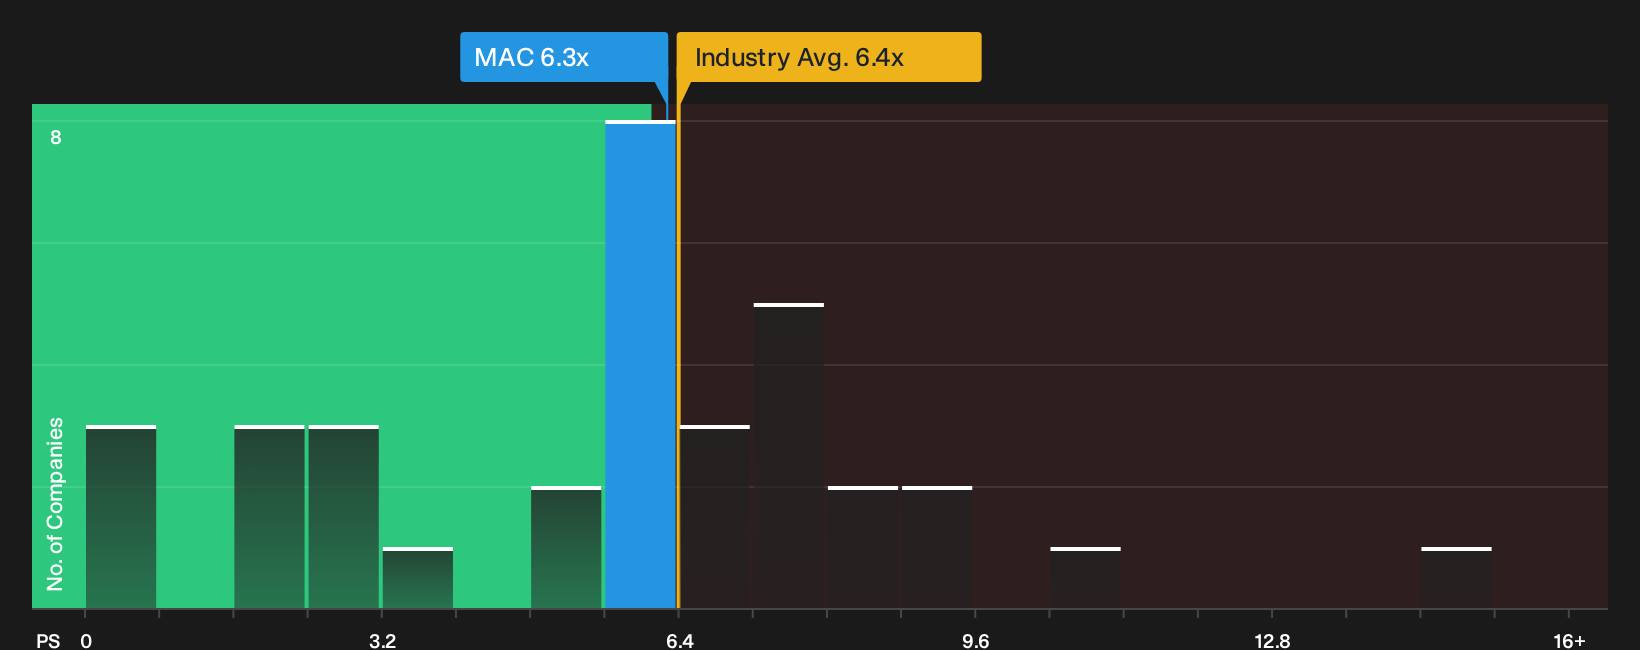
The fair value narrative and analyst targets lean on long term earnings and cash flow improvements. The current P/S of 6.3x tells a different story. It screens cheaper than Retail REIT peers at 7.9x, yet richer than a 4.2x fair ratio that the market could move toward over time.
That gap suggests investors are paying a premium to the fair ratio while still getting a discount to the peer group. This raises a simple question: Is Macerich priced for balanced outcomes, or is there more downside risk if sentiment turns?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages around Macerich can be confusing. Check the data, weigh the trade offs, and then ground your own view with 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Macerich?
If Macerich has sharpened your thesis, do not stop here. Use the Simply Wall Street Screener to line up your next set of potential opportunities.
- Target potential upside by scanning for quality companies that trade below estimated value through our 33 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on companies with dependable balance sheets using the 30 resilient stocks with low risk scores.
- Hunt for lesser known opportunities with strong fundamentals by checking the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com