
Axsome Therapeutics (AXSM) Presents Fresh Psych Congress Data, Is The Stock Cheap?
Psych Congress data puts Axsome Therapeutics (AXSM) pipeline in focus
Axsome Therapeutics (AXSM) drew fresh attention after presenting new data in major depressive disorder and Alzheimer’s disease agitation at Psych Congress 2026, alongside multiple encore posters across its psychiatry and neurology programs.
Recent trading has been choppy for Axsome Therapeutics, with the share price down 3.03% over the past day and 17.05% over 90 days. However, the year-to-date share price return of 16.28% and a 1-year total shareholder return of 79.20% indicate that longer-term momentum has been strong despite short-term weakness, as investors weigh Psych Congress 2026 data against earlier earnings misses and widening losses.
Scan beyond Axsome Therapeutics to find other CNS focused biopharma stocks that screen strongly on fundamentals in our curated 16 high quality undiscovered gems
Axsome Therapeutics now trades at a steep discount to both intrinsic value estimates and analyst targets after the recent pullback. Is that gap a mispricing, or a fair reflection of execution and earnings risk?
Most Popular Narrative: 26% Undervalued
Axsome Therapeutics last closed at $207.78, while the most followed narrative anchors fair value at $282.51. This frames a sizable valuation gap that investors are using Psych Congress data to reassess.
The company is advancing multiple late-stage clinical programs (AXS-05, AXS-12, AXS-14, and several solriamfetol indications), which positions Axsome to benefit from the aging population and rising prevalence of CNS disorders, potentially resulting in a diversified revenue base, higher earnings, and reduced risk of overreliance on a single product.
See why 39 investors see Axsome Therapeutics as 26% undervalued.
Result: Fair Value of $282.51 (UNDERVALUED)
Still, the bullish Axsome Therapeutics story can crack if payer pressure keeps gross to net discounts high or if multi-product launches keep losses and cash burn elevated.
Find out about the key risks to this Axsome Therapeutics narrative.
Another View: What Axsome Therapeutics’ P/S Ratio Might Be Telling You
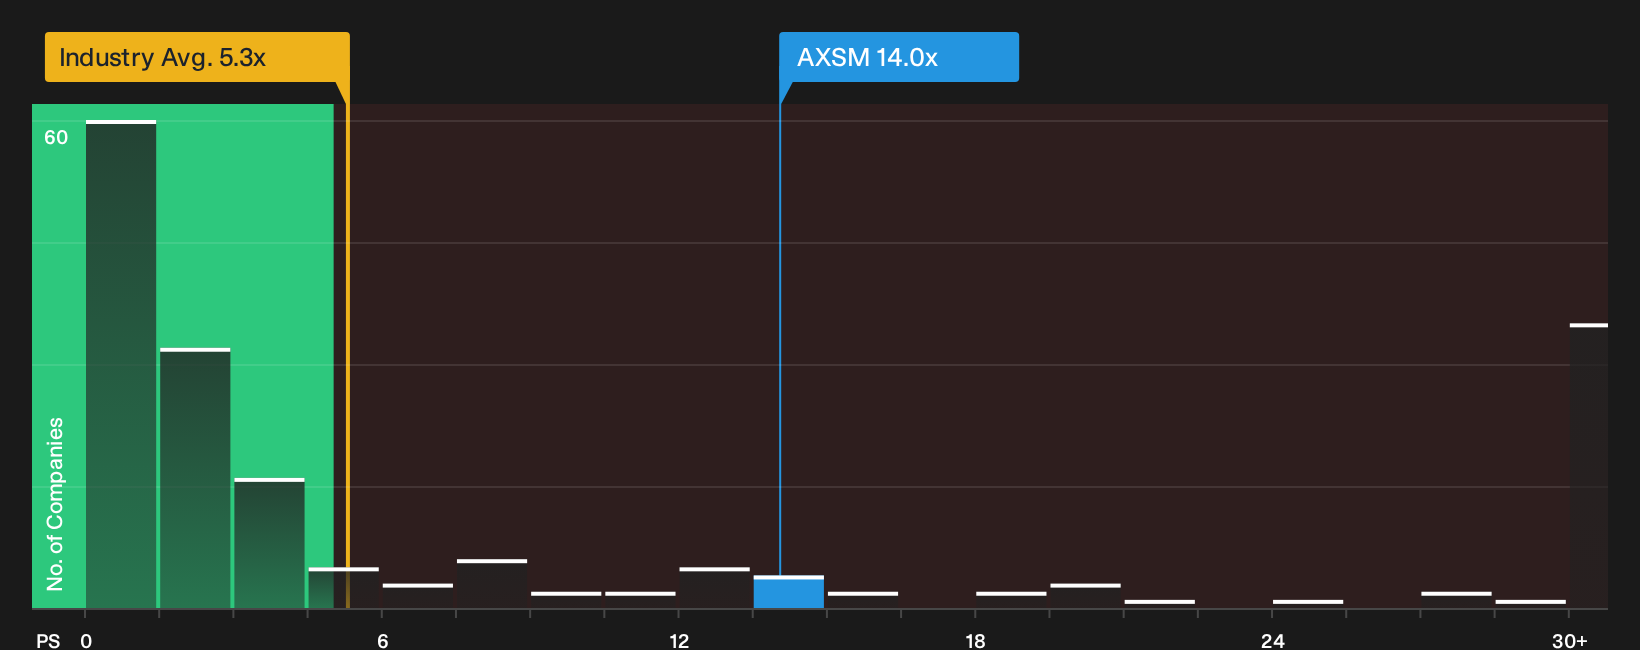
The earlier fair value work points to Axsome Therapeutics trading at a steep discount to intrinsic value, yet the market is still paying a rich P/S of 14x. That is far above the US Pharmaceuticals average of 5.3x and ahead of the peer average of 9.9x.
The fair ratio is 16.6x, which sits higher than the current multiple and frames the premium differently. The gap suggests investors are already pricing in strong growth, but not the most optimistic scenario. The real question is whether you see that as valuation risk or room for sentiment to shift.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Big claims about Axsome Therapeutics can sound compelling on paper, but your judgment matters more than any single model or metric. To pressure test the optimism and see which potential reward pillars matter most to you, review the 3 key rewards.
Looking for more Axsome Therapeutics sized ideas?
If Axsome Therapeutics has your attention, do not stop here. Put the same disciplined lens on other opportunities so your watchlist keeps working for you.
- Target resilient income by scanning for companies that have paid out reliable cash returns in our 6 dividend fortresses.
- Hunt for quality at a discount by reviewing companies that combine strong fundamentals with marked-down valuations through the 33 high quality undervalued stocks.
- Protect your downside by focusing on businesses screened for sturdier finances and dependable balance sheets using the list of solid balance sheet and fundamentals (23 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com