
Round One And 2 Other Japanese Insider Growth Stocks
The Federal Reserve has just lifted interest rates again, reminding everyone that money is no longer cheap and growth stories face a higher hurdle. In that kind of backdrop, Japanese companies where insiders already have serious skin in the game and are publicly optimistic about the road ahead can stand out. This article highlights three fast growing Japanese stocks with meaningful insider ownership that may deserve a closer look.
The three Japanese stocks that follow are only a small sample, and the full screen surfaced around 100 more companies with similarly strong insider backing and upbeat outlooks that this article does not cover. To move beyond the shortlist and start sorting for your own highest conviction ideas, head straight to the Fast Growing Stocks With High Insider Ownership screener
Round One (TSE:4680)
Overview: Round One operates multi entertainment centers that bundle bowling, arcade games, karaoke, billiards, and Spo Cha into large indoor leisure complexes.
Market Cap: ¥310.8 billion
Round One fits clearly in the screener theme because growth focuses on opening more multi entertainment centers in Japan and overseas, while analysts and management remain upbeat and earnings expectations sit in the mid-teens. Investors get a growth plan that is easy to track, yet outcomes for profitability still depend on how one unseen pressure shapes store level economics.
That invisible pressure is where serious work begins, so scan the 5 key rewards and 1 important warning sign to see how Round One’s expansion story lines up against store level risk.

JX Advanced Metals (TSE:5016)
Overview: JX Advanced Metals supplies semiconductor materials and high purity metals alongside copper and rare metal products for electronics, chemicals, and recycling markets.
Market Cap: ¥3.4 trillion
JX Advanced Metals plugs directly into the screener theme through its Semiconductor Materials unit, where sputtering targets, compound semiconductors, and high purity metals are used in chip and electronics demand. Earnings growth of 91.8% over the past year and 14.6% net margins show that growth is currently pairing with solid profitability. This will depend in part on how one unresolved cycle in semiconductor materials and pricing develops.
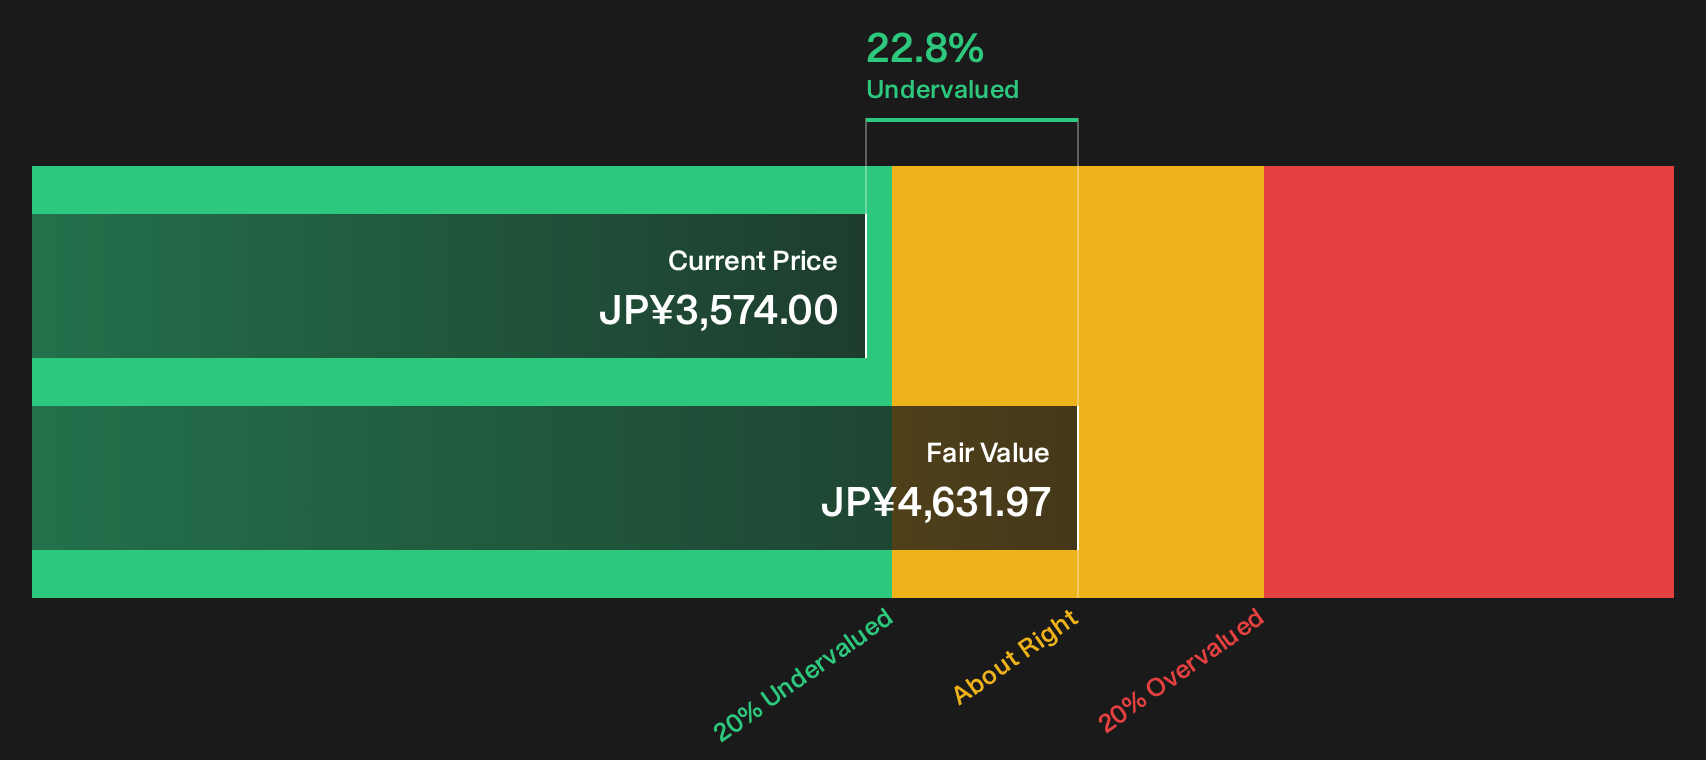
That unresolved cycle is exactly what the DCF valuation analysis for JX Advanced Metals measures, helping you see whether current expectations already factor in the next swing.
Rakuten Group (TSE:4755)
Overview: Rakuten Group runs an integrated ecosystem of online shopping, fintech services, digital content, and mobile communications for consumers and businesses worldwide.
Operations: Rakuten Group generates about ¥1.4t from Internet Services, ¥1.1t from Fintech, and ¥513b from Mobile, offset by internal transactions.
Market Cap: ¥1.5t
Rakuten Group lands in this screener because management is leaning hard into the high growth Mobile segment while tying it tightly into its broader e-commerce and fintech ecosystem.
"AI-driven operational efficiencies, targeting a 31% reduction in customer support costs, are anticipated to improve net margins by boosting profitability across Rakuten's operational segments."
What really moves the needle is how one unresolved inflection in the mobile and fintech push eventually filters through to group-level margins.
That turning point in margins is exactly where the full narrative for Rakuten Group shows how Rakuten Group’s ecosystem bets could accelerate or stall that shift.

Seeking Fresh Alternatives Before They Fly
Markets move fast and the strongest stories often build momentum quietly before a breakout. Scan these fresh ideas while they are still under the radar for now and act now.
- Spot resilient cash generators that can shoulder tougher conditions by working through the curated list of solid balance sheet and fundamentals (20 results) before the crowd starts paying closer attention.
- Target income opportunities that could help stabilise your portfolio’s cash flow using a focused group of 14 dividend fortresses while yields still look appealing.
- Hunt for overlooked growth stories where the underlying technology case is still building by screening a tight set of 89 AI infrastructure stocks before momentum really builds.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com