
Radware (RDWR) Draws Fresh Valuation Focus, Is The Stock Overvalued?
Radware (RDWR) has drawn fresh attention after its shares last closed at US$29.13, with recent trading performance and underlying financial metrics prompting investors to reassess how the cyber security specialist fits into their portfolios.
Recent trading paints a mixed picture for Radware. The 1-day share price return declined 4.65%, yet the 30-day share price return of 7.69% and year-to-date share price gain of 22.50% suggest momentum has been building, while a 3-year total shareholder return of 78.49% contrasts with a 5-year total shareholder return, which is down 18.99%.
Scan how Radware compares with other cyber security and software names showing momentum and fresh interest through our curated 16 high quality undiscovered gems.
After Radware’s strong recent run, the share price now sits only slightly below the average analyst target, while one intrinsic estimate implies a much higher figure. Is this just momentum, or a genuine valuation gap?
Price-to-Earnings of 71x: Is it justified?
Valuation is no longer a sideshow for Radware. A P/E of 71x at a last close of $29.13, against peers closer to the high 20s, suggests investors are paying a premium for each dollar of current earnings.
The P/E multiple measures how much the market is willing to pay today for the company’s trailing profits. For a cyber security and software-focused business like Radware, a higher P/E typically reflects expectations for stronger profit expansion or a perceived quality premium in its earnings profile.
Here, the picture is mixed. Earnings have grown 16% per year over the past 5 years and 21.9% over the last year, which helps explain some enthusiasm. At the same time, revenue is forecast to grow 7.9% annually, slower than the wider US market at 13.4%. Radware’s Return on Equity of 4.8% is described as low. That combination means the market is paying up for a profit story that has improved historically, while key efficiency and growth metrics remain more muted.
Compared to the US Software industry average P/E of 29.8x, Radware’s 71x multiple is described as expensive. The gap is wide, so the stock is priced well above peers based on current earnings, with no fair ratio guide available to suggest a different anchor level for the valuation.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 71x (OVERVALUED).
Still, a revenue growth rate of 7.9% and Return on Equity of 4.8% leave Radware exposed if investor expectations for earnings quality or acceleration cool.
Find out about the key risks to this Radware narrative.
Another View on Radware’s Value
The P/E premium is only one lens. Our DCF model points in the opposite direction, with Radware trading at $29.13 compared with an estimated future cash flow value of $19.41, which suggests the stock screens as overvalued on this framework. Which signal should carry more weight for you?
Look into how the SWS DCF model arrives at its fair value.
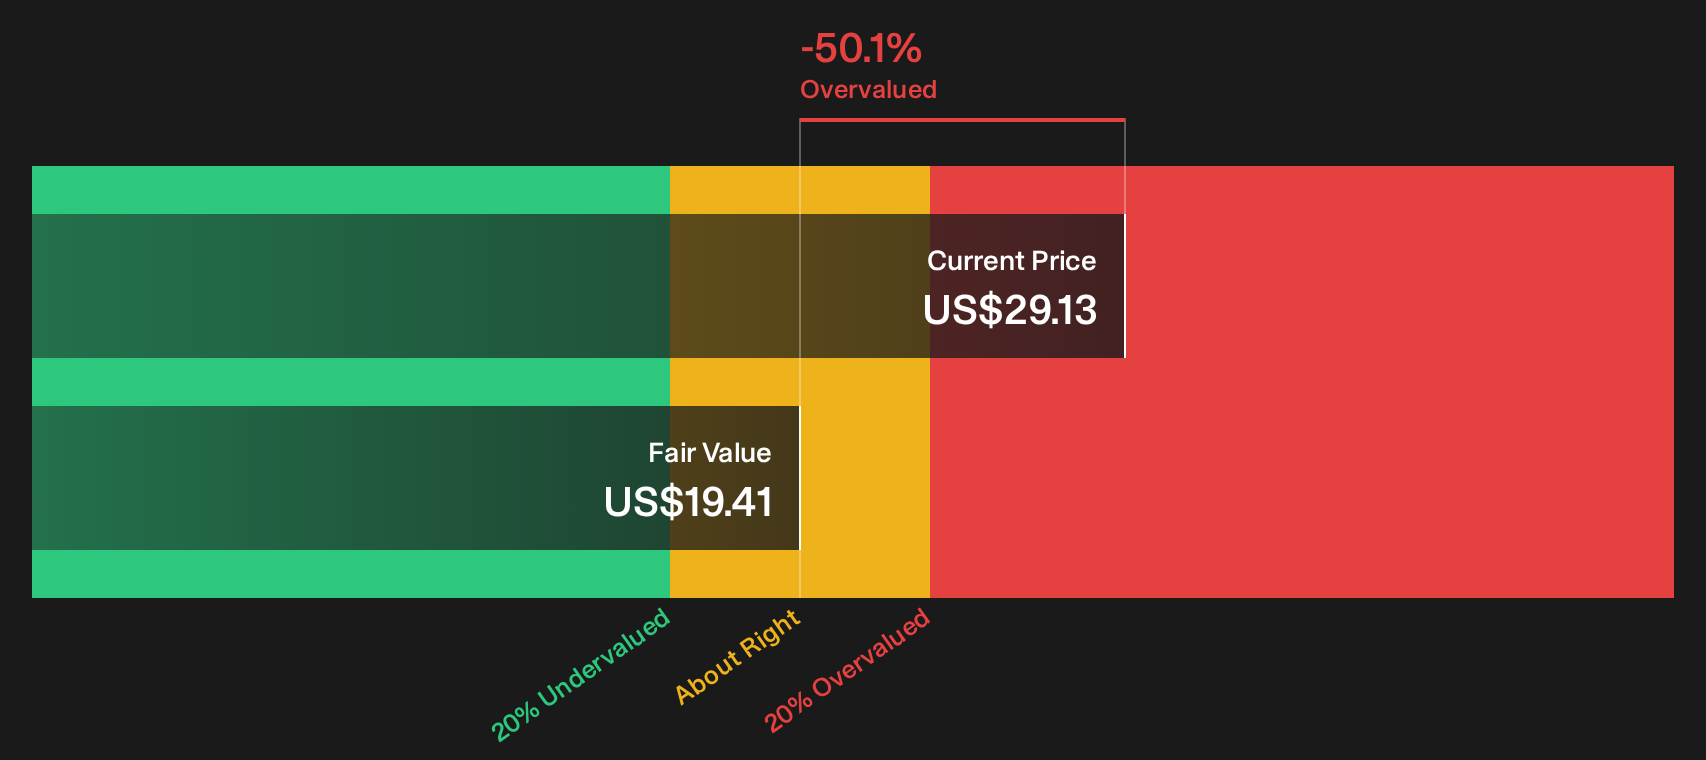
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Radware for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Radware can feel messy, so move quickly, check the numbers yourself, and weigh both the 1 key reward and 2 important warning signs in the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Radware?
If Radware has you thinking harder about where to put fresh capital, do not stop at a single ticker. Use targeted screeners to uncover ideas you might otherwise miss.
- Target steadier potential by reviewing companies with strong balance sheets and consistent fundamentals in the list of solid balance sheet and fundamentals (23 results).
- Chase value opportunities by checking which stocks combine quality metrics with lower valuations in the 33 high quality undervalued stocks.
- Prioritize resilience by focusing on businesses that score well on risk across sectors through the 30 resilient stocks with low risk scores.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com