
Learn Why The Bull Case For Jack Henry Stock Could Change Following Earnings Beat
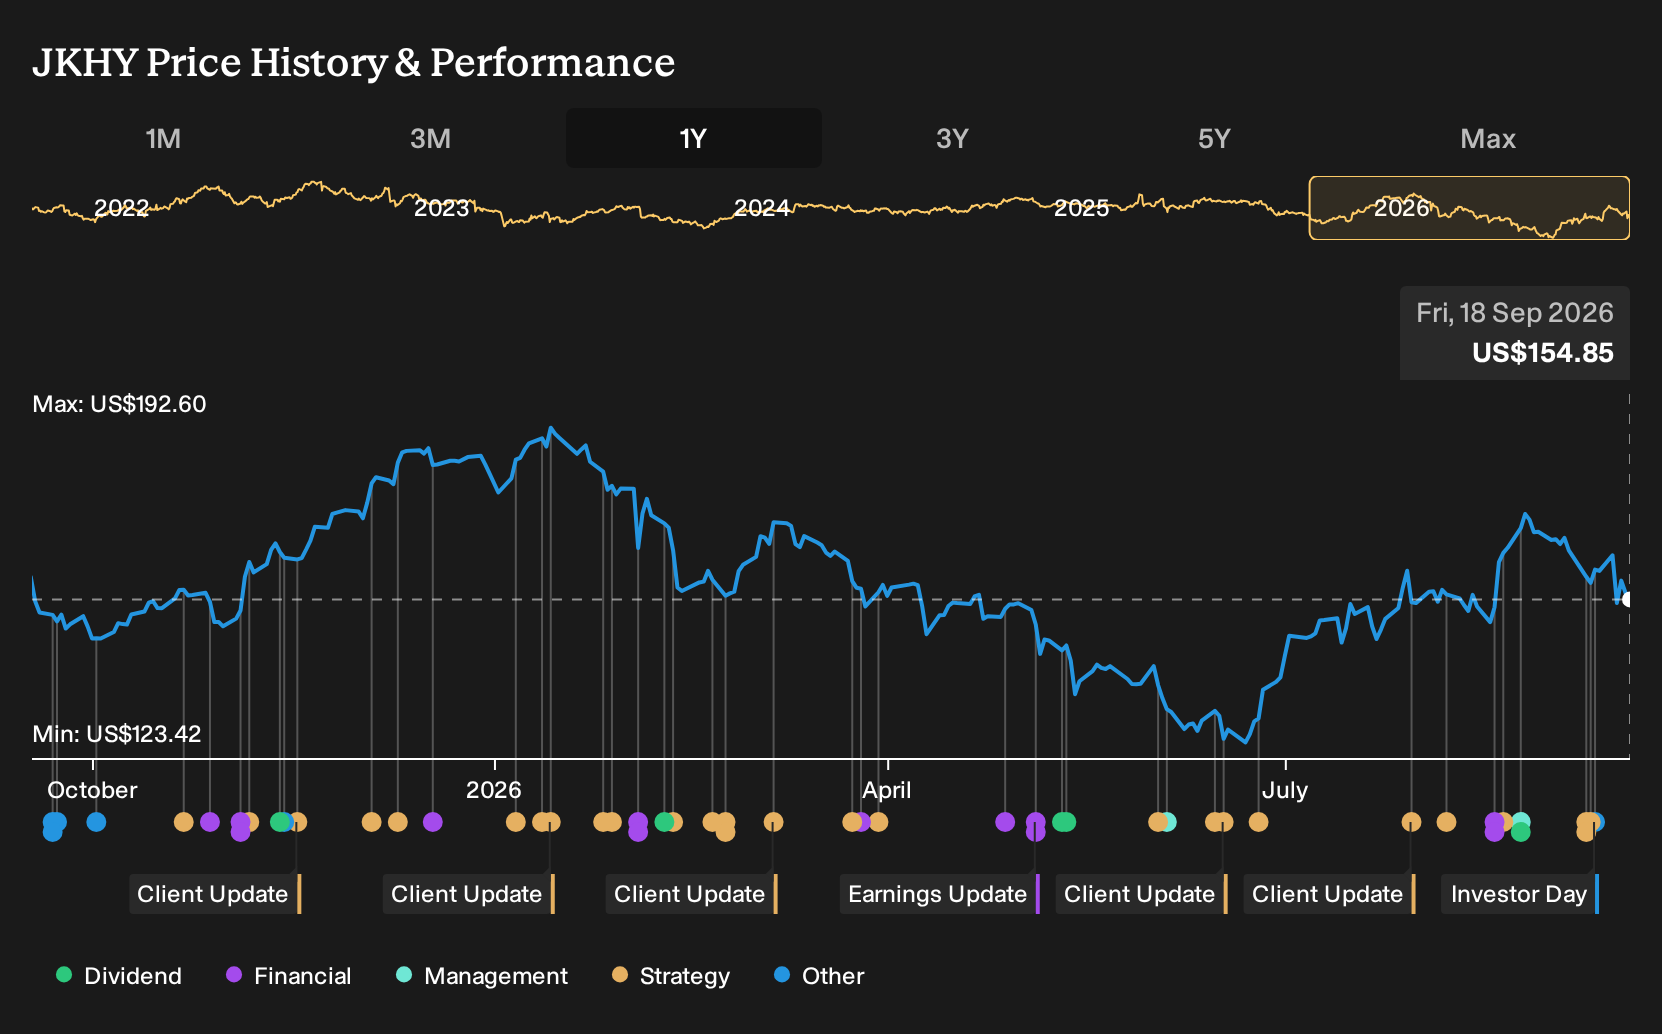
- Jack Henry & Associates recently reported fourth quarter fiscal 2026 results that exceeded earnings expectations, with revenue higher year over year and support from processing, cloud-related data processing, digital transactions, and faster payments. The company also issued guidance for fiscal 2027 that points to revenue growth of about 5.5-7.3% and GAAP earnings growth of 5-5.7% per share.
- Recent integrations with Splitit and Trust Stamp, plus Celtic Bank adopting Jack Henry solutions, point to active demand for its core, cloud, and digital platforms, which ties directly into processing volumes and recurring service revenue.
- We will now look at how Jack Henry & Associates' better than expected quarterly earnings and guidance affect its broader investment narrative.
Jack Henry & Associates Investment Narrative Recap
An investor in Jack Henry & Associates needs to believe the shift toward cloud based core processing, digital banking, and payments continues to support recurring software and processing revenue. The recent quarter and fiscal 2027 guidance point to steady, though not rapid, growth expectations. The main near term catalyst remains execution on cloud and digital adoption across existing bank and credit union clients.
The biggest current risk is that bank consolidation, pricing pressure, and fintech competition slow that adoption or compress contract economics. The new integrations and client wins help, but they do not fully offset the structural risk of a shrinking U.S. regional banking customer pool if that trend accelerates.
The Splitit integration into Jack Henry & Associates’ SilverLake and Banno platforms looks especially relevant. It speaks directly to the thesis that payment and digital capabilities can deepen the firm’s role inside clients’ customer relationships. This, in turn, can feed processing volumes and support higher value software contracts over time if execution stays on track.
For you as a shareholder, this type of partnership is a near term proof point for the open ecosystem story highlighted at Analyst Day. It also touches the core risk. If banks do not lean into tools like embedded debit installments, or if competing platforms secure more of these integrations instead, the catalyst of recurring digital payment flows could soften and slow the revenue mix shift management is targeting.
Jack Henry & Associates' current analyst narrative points to about US$3.0b in revenue and US$593.4m in earnings by 2029. That profile lines up with assumed revenue growth of 6.4% per year and an earnings increase of roughly US$74.2m from earnings today of US$519.2m.
Uncover why Jack Henry & Associates' fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
The Simply Wall St Community currently has three fair value estimates for Jack Henry & Associates, stretching from about US$163.69 up to roughly US$212.03. You see very different conclusions. Set those side by side with the recent Splitit and Trust Stamp integrations, plus the Analyst Day focus on cloud and fraud tools, and you get a wide spectrum of potential outcomes that rewards comparing multiple viewpoints yourself.
Explore 2 other Jack Henry & Associates fair value estimates, including one that suggests as much as 37% upside from the current price.
Decide For Yourself
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Jack Henry & Associates research is our analysis highlighting 5 key rewards that could impact your investment decision.
- See our latest analysis for Jack Henry & Associates. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Jack Henry & Associates' overall financial health at a glance.
Looking For More Investment Ideas Beyond Jack Henry & Associates?
If Jack Henry & Associates has sharpened your focus on recurring revenue and resilient balance sheets, it can be useful to widen the lens and scan for other businesses with similar strengths or different risk and income profiles. The Simply Wall St Screener gives you a straightforward way to filter for the mix of quality, value, and stability that fits your own approach.
- For investors hunting for quality at a sensible entry point, check out 33 high quality undervalued stocks that match strong fundamentals with prices that may not fully reflect them yet.
- If capital preservation and steadier profiles matter more to you, use the 30 resilient stocks with low risk scores to focus on companies with lower risk scores and more resilient financial characteristics.
- When income is your priority and you want potential yield alongside durability, scan through 6 dividend fortresses tailored for investors who care about both payouts and staying power.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com