
How Investors May Respond To Northern Trust Stock Outsourced Trading Win
- Northern Trust secured fresh mandates from J O Hambro Capital Management and Warwickshire Pension Fund, expanded Singapore unit trust servicing with Perpetual, launched a Stablecoin Cash Reserves Portfolio, and created a new Emea private markets leadership role.
- These moves concentrate on higher complexity services such as outsourced trading, private markets and digital asset infrastructure, which can reshape Northern Trust's mix toward more specialized, operationally intensive fee streams.
- We will now examine how Northern Trust's new outsourced trading mandate could influence the broader investment narrative around its fee resilience.
Northern Trust Investment Narrative Recap
For Northern Trust, the core belief as a shareholder is that its mix of asset servicing, wealth management and capital markets can keep generating steady fee income while cost discipline and technology keep margins from backsliding. The recent run of mandates and product launches points to continued demand for complex custody and outsourcing, although the near term share price still leans heavily on sentiment around fee pressure and tech spend.
The key short term swing factor remains whether operating leverage holds up as the firm keeps investing in data, automation and digital asset capabilities. The biggest risk is that higher technology and regulatory costs outpace efficiency gains, especially if clients push harder on pricing or rotate further toward lower fee products.
The J O Hambro outsourced trading mandate is the clearest operational proof point in this news cycle. It extends a long standing asset servicing relationship into higher value trading and middle office work, exactly where Northern Trust aims to deepen wallet share with complex managers that prize global coverage and integrated infrastructure.
This win matters for the catalyst debate because it reinforces the story that growth can come from richer service intensity per client, not just new relationships. It also highlights execution risk. Pulling in parts of a client’s trading team, operating 24/6 markets coverage and maintaining measured execution quality all raise the bar on systems resilience and cost control at the very moment investors are focused on margin durability.
Northern Trust’s analyst narrative points to US$10.1b in revenue and US$2.5b in earnings by 2029, built on an assumed 3.6% yearly increase in revenue and an earnings rise of about US$0.3b from US$2.2b today.
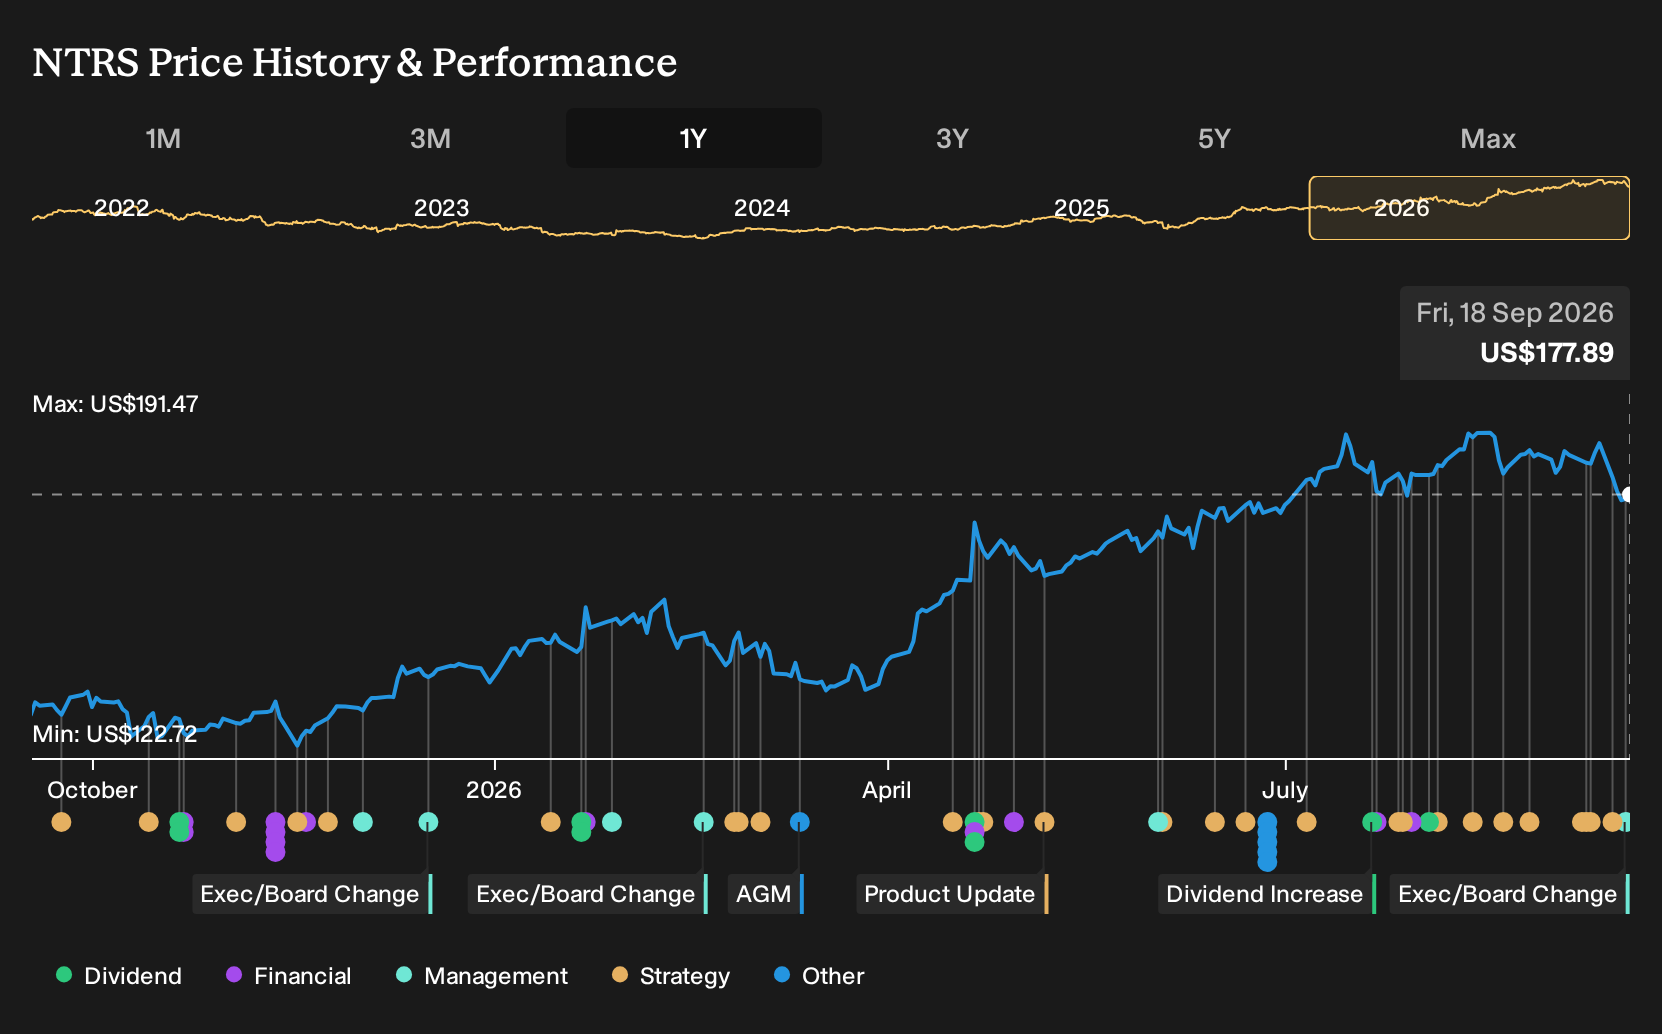
Uncover why Northern Trust's fair value indicates a 3% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
Two fair value inputs from the Simply Wall St Community cluster tightly between about US$179.8 and US$183.8 per share, which shows how closely some retail modellers are currently grouped. Your view might differ once you factor in Northern Trust’s stablecoin cash vehicle, its Emea private markets role, and its expanded outsourcing. Explore several alternative viewpoints before leaning on any single estimate.
Explore another Northern Trust fair value estimate, including one that suggests it could be worth just $179.84.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Northern Trust research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for Northern Trust. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Northern Trust's overall financial health at a glance.
Looking for more Northern Trust style ideas?
If Northern Trust's focus on complex custody, outsourced trading and richer fee pools appeals to you, it can help to widen the search and compare it with other businesses that share some of those qualities.
- For investors who want quality and value in one place, consider using a screener that highlights 33 high quality undervalued stocks with solid fundamentals and clear financial profiles.
- If capital preservation and steadier profiles matter most to you, a tool that narrows the field to 30 resilient stocks with low risk scores can help you focus on companies with more resilient characteristics.
- Those seeking dependable income can use a filter that focuses on 6 dividend fortresses with yields above 5% and an emphasis on stability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com