
Why Calumet (CLMT) Is Getting Attention Today
Calumet (CLMT) just reshaped its financing picture by lifting its asset-based loan facility to US$600 million and securing a final US$34 million draw for Montana Renewables under a U.S. Department of Energy loan guarantee.
That financing backdrop has landed in a market that already had Calumet on a strong run, with the share price at US$59.0 after a 22.2% 1 month share price return and an 80.8% 3 month share price return. This has fed into a 201.8% year to date share price return and a 1 year total shareholder return of 218.8%, which signals strong momentum rather than a short lived spike.
Spot similar balance sheet and financing stories by scanning the hand picked list of solid balance sheet and fundamentals (23 results) that could sit alongside Calumet in your watchlist.Bulls see fresh credit capacity and DOE support turning Calumet into a re-rated renewables platform. Bears point to losses and a stretched chart. Which case does the current valuation lean toward?
Most Popular Narrative: 10% Overvalued
Calumet last closed at $59.0, while the most followed narrative pegs fair value at $53.40 using a 7.25% discount rate. This leaves the stock trading meaningfully above that estimate and puts the focus squarely on whether its renewables pivot can justify the gap.
The MaxSAF 150 project is on track to start up in the first half of 2026, enabling Calumet to produce 120-150 million annual gallons of sustainable aviation fuel (SAF) at relatively low capital costs, capturing premiums of $1-$2/gallon over renewable diesel and tapping into surging mandated and voluntary SAF demand globally. This is likely to drive material step-up in revenues and EBITDA margin expansion once operational.
See why 5 investors see Calumet as 10% overvalued.
Result: Fair Value of $53.40 (OVERVALUED)
Still, if regulatory support for renewable fuels weakens or high leverage constrains Calumet’s flexibility, the current overvaluation narrative could unwind quickly.
Find out about the key risks to this Calumet narrative.
Another View: SWS DCF Signals Deep Undervaluation
Analysts framing Calumet as about 10% overvalued are leaning on a $53.40 fair value. Our SWS DCF model points in the opposite direction. It values the stock at $158.34 based on future cash flows, which is far above the current $59.00 share price and characterizes Calumet as heavily undervalued on that lens.
This kind of gap between a DCF output and an analyst target often comes down to different assumptions on margins, capital intensity, and discount rates. The key question for you is simple: Which version of Calumet’s future cash generation feels closer to reality?
Look into how the SWS DCF model arrives at its fair value.
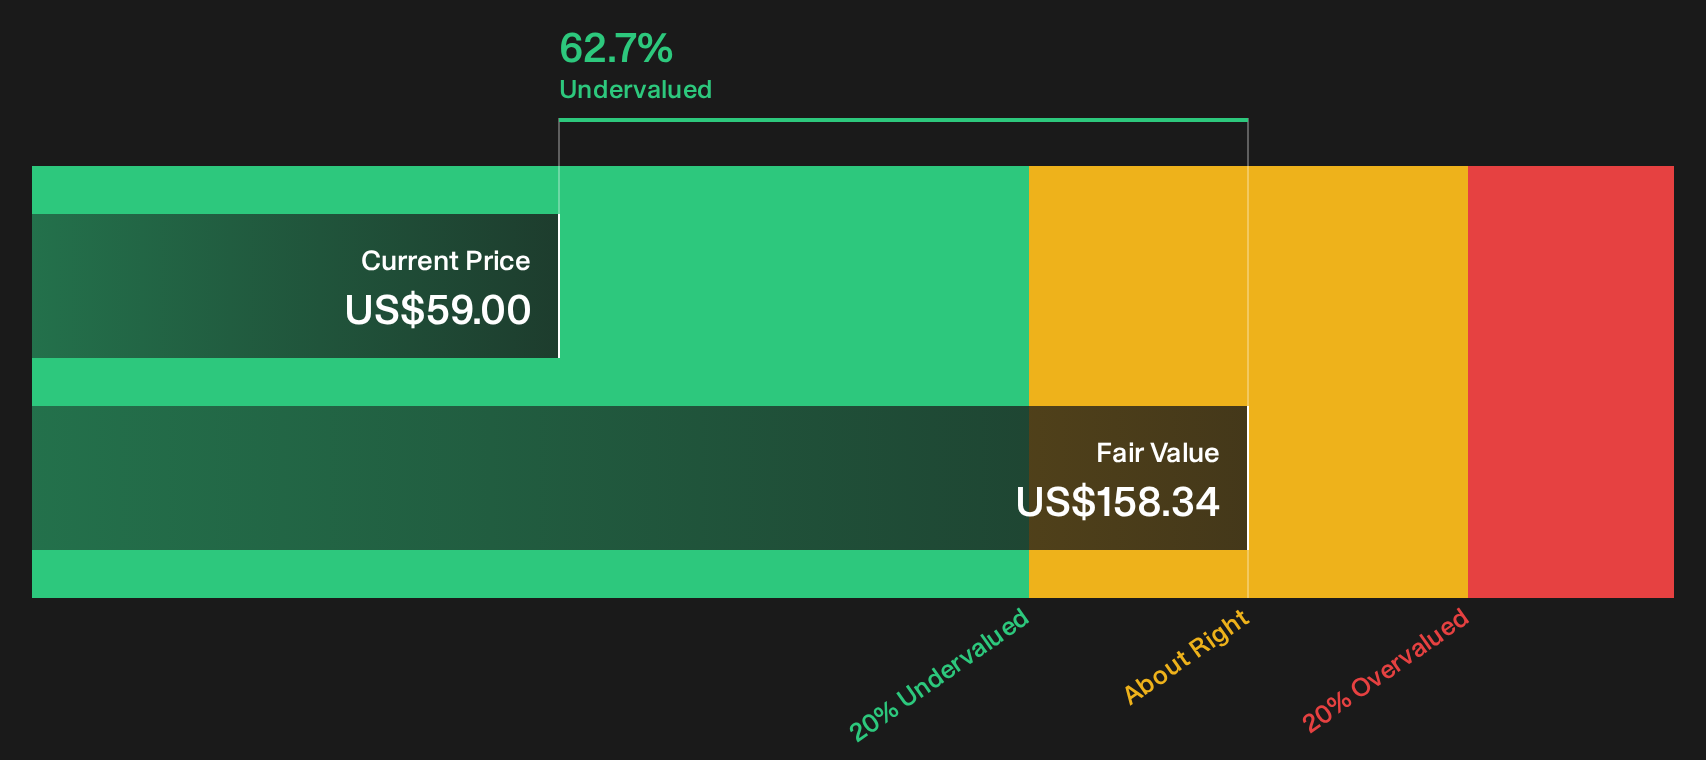
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Calumet for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 33 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Strong views are already forming around Calumet. Move quickly, test the numbers yourself, and weigh both sides using the 3 key rewards and 1 important warning sign.
Looking for more Calumet style investment ideas?
If you stop with Calumet, you only see one angle. Use the Simply Wall Street Screener to line up fresh ideas before the next move passes you by.
- Target steadier portfolios by scanning a curated pool of resilient companies in the 30 resilient stocks with low risk scores.
- Hunt for quality at a fair price by sorting through the 33 high quality undervalued stocks that may align with your return and risk expectations.
- Spot future standouts early by researching the 16 high quality undiscovered gems that have strong fundamentals but limited attention so far.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com