
IREN (IREN) Could Be 35% Undervalued After AI Contract Wins And Nvidia Tie Up
IREN (NasdaqGS:IREN) has been in focus after a wave of upbeat Wall Street research tied to its Nvidia partnership, Mirantis acquisition, AI cloud contract wins, and plan to retire lower margin Bitcoin mining.
IREN’s recent rally, including a 1-day share price return of 7.36% and a 7-day move of 6.50% to US$46.68, comes after a sharp 90-day decline of 22.15%. Short term momentum is picking up even though the 3-year total shareholder return of over 11x reflects a much larger, longer running re-rating linked to its AI pivot.
Scan other AI infrastructure stocks showing similar contract momentum and power optionality through our hand picked 89 AI infrastructure stocks as you assess how IREN fits into your watchlist.
IREN has already gone through a huge AI re-rating, yet the latest contract wins and analyst targets suggest investors are still debating where the real upside sits. Is most of the move already in the rearview mirror, or not?
Most Popular Narrative: 35% Undervalued
IREN last closed at $46.68, while the most followed valuation storyline on Simply Wall St pegs fair value at $71.48 using a 10% discount rate. That gap is driving a very different conversation to the one implied by recent short term volatility.
IREN represents an intriguing yet risky investment opportunity in the evolving landscape of Bitcoin mining and computational services. With its leading efficiency, strategic diversification into HPC and AI, and strong financial footing, IREN is well positioned to capitalise on future growth opportunities. However, given the inherent risks, it''s wise for investors interested in the Bitcoin mining space to diversify with other miners that have different strategies, such as Marathon, Cleanspark, Wulf, and Core Scientific.
See why 261 investors see IREN as 35% undervalued.
Result: Fair Value of $71.48 (UNDERVALUED)
Still, the IREN story can crack if future dilution returns in size or if planned multi billion dollar AI CapEx fails to earn its keep.
Find out about the key risks to this IREN narrative.
Another View On IREN’s Valuation
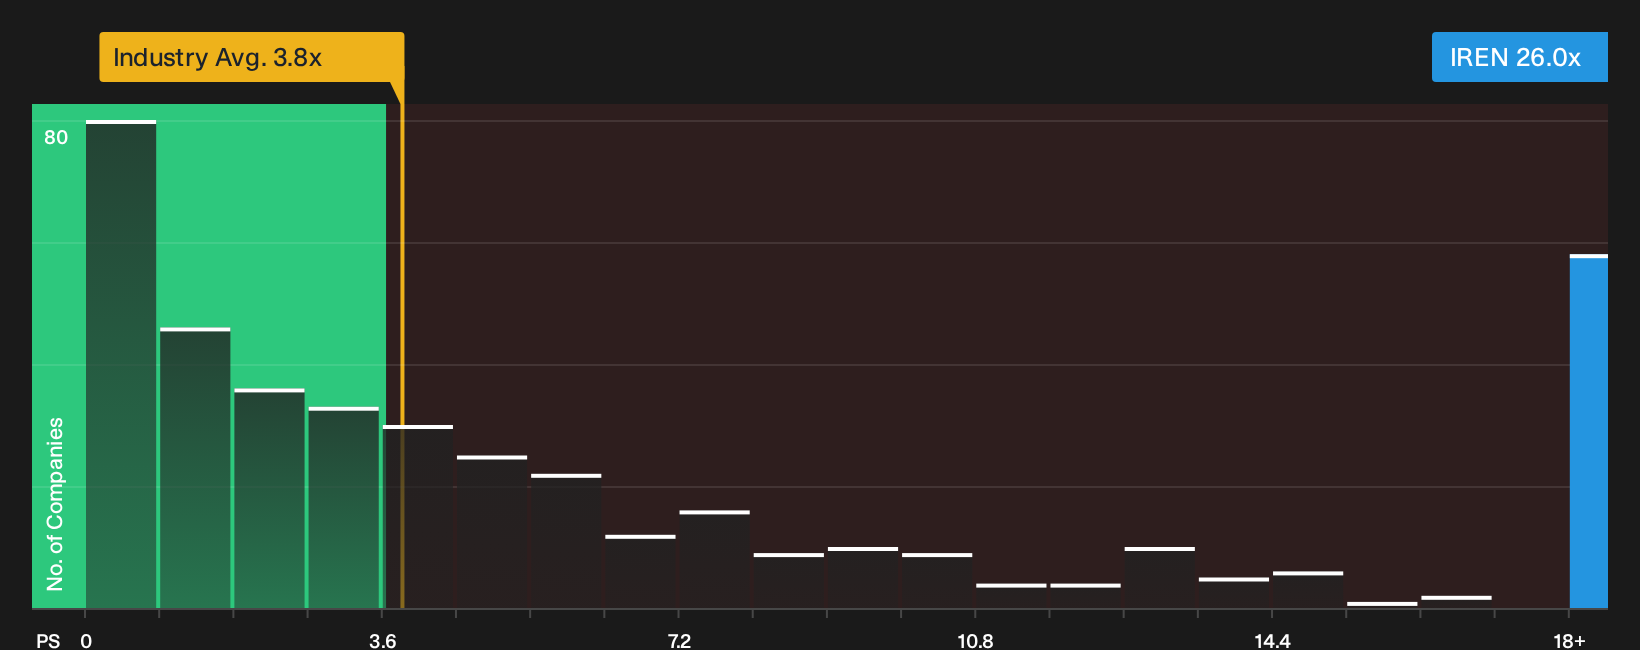
That 35% undervaluation storyline sits awkwardly next to IREN’s current P/S of 26x, compared with 3.8x for the wider US Software sector and a 16.3x peer average. Our fair ratio estimate of 18.2x implies the multiple could compress, which would put more of the burden on future execution. Where does that leave risk tolerance?
Investors who want to see how this pricing gap plays out through the numbers can dig into our full valuation workup, including the fair ratio context, in See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Sentiment on IREN is split, with both optimism and caution running high. Investors may want to move quickly, review the data for themselves, and weigh the 1 key reward and 4 important warning signs.
Looking for more IREN-sized opportunities?
Do not stop your research with IREN. Use targeted screens to surface fresh ideas quickly so you are not chasing stories after the big move.
- Target potential mispricings by scanning a curated set of quality companies trading below estimated value through the 33 high quality undervalued stocks.
- Strengthen your watchlist with businesses that pair healthier balance sheets and fundamentals by using the focused list of solid balance sheet and fundamentals (23 results).
- Gain earlier exposure to lesser known opportunities by reviewing the hand picked 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com