
Advantest (TSE:6857) Shares Jumped, So What Is Driving Attention Now?
Advantest in the Crosswinds of Rates and Currency
The Bank of Japan’s move to lift rates to 1.25%, while the yen remains weak against the dollar, has pushed Advantest (TSE:6857) into a rare mix of higher funding costs and potentially supportive export conditions.
Advantest’s share price has moved sharply around the macro headlines, with a 1-day share price return of 5.99% and year to date share price return of 51.36%. The 1-year total shareholder return of 114.10% and very large 5-year total shareholder return point to strong momentum that has recently cooled, with a 30-day share price return down 8.48%.
Scan how other export-focused chip and hardware players are reacting to the same rate and currency crosswinds by reviewing the hand-picked 89 AI infrastructure stocks alongside Advantest.
After a 114.10% 1-year total return and a recent 8.48% pullback over 30 days, investors may ask whether Advantest still offers a sensible balance of upside potential and downside risk at ¥32,050 a share, or whether the easier opportunities have already passed.
Most Popular Narrative: 16% Undervalued
Advantest’s most followed narrative pegs fair value at ¥38,319 per share, above the recent ¥32,050 close. This frames today’s pullback as a discount relative to those earnings assumptions and risk settings.
The exponential proliferation of AI-driven applications and complexity in next-generation semiconductors continues to fuel unprecedented demand for advanced SoC and memory testers, with sustained double-digit market growth expected into FY2026 and beyond, this cycle directly supports above-industry-average revenue growth for Advantest.
See why 17 investors see Advantest as 16% undervalued.
Result: Fair Value of ¥38,319 (UNDERVALUED)
Still, this Advantest story can break if AI hardware demand cools more sharply than analysts expect, or if rapid capacity buildout leaves the group with underused factories and pressured margins.
Find out about the key risks to this Advantest narrative.
Another View on Advantest’s Valuation
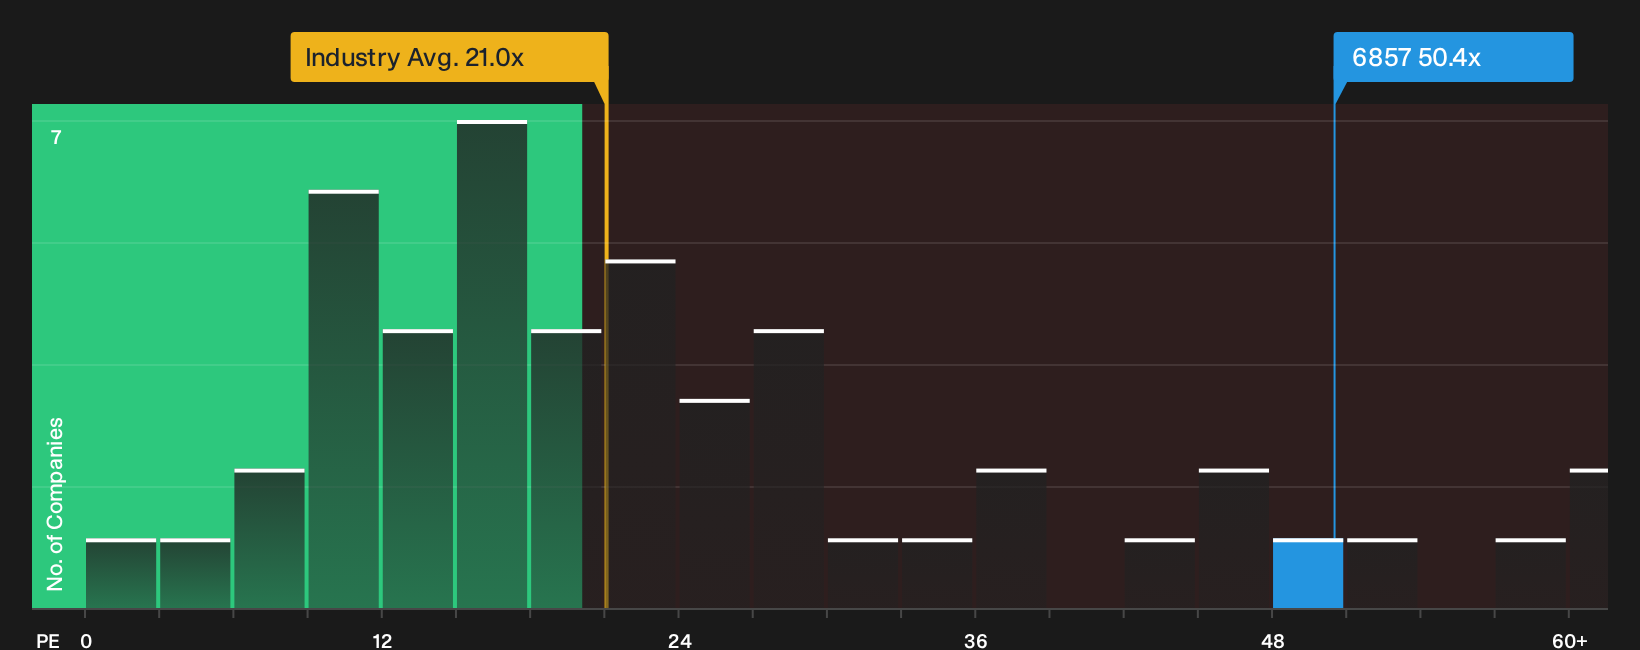
The story looks different when you compare Advantest’s current P/E of 50.4x with the JP Semiconductor industry at 19.8x and a fair ratio of 37.9x. That premium suggests investors are already paying up, so the key question is whether earnings quality and growth can keep justifying that gap.
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
If this mix of enthusiasm and caution around Advantest feels familiar, that is the point. The real edge comes from testing the numbers yourself and pressure testing the story against your own risk tolerance using the 2 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Advantest?
If Advantest has you thinking more critically about price, quality, and risk, then broadening your watchlist with a few targeted screens can sharpen your next move.
- Target potential mispricing by scanning a curated set of companies that combine quality fundamentals with attractive valuations through the 17 high quality undervalued stocks.
- Strengthen portfolio resilience by focusing on businesses with conservative leverage and robust balance sheets using the list of solid balance sheet and fundamentals (20 results).
- Spot early-stage opportunities that the broader market may be overlooking by reviewing the 74 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com