
Energix Renewables Energy (TASE:ENRG) Closes Lithuanian Project Deal, Is The Valuation Already Too Rich?
Energix - Renewable Energies (TASE:ENRG) just closed its Purchase Agreement for a large Lithuanian wind, solar, and storage project, giving investors a fresh data point on the company’s expanding development pipeline.
Recent trading reflects that tension between opportunity and risk. Energix - Renewable Energies has a 1-day share price return of 3.62% and a year-to-date share price return of 21.62%. However, the 90-day share price return declined 13.79%, while the 1-year total shareholder return of 50.77% and 3-year total shareholder return of 89.05% suggest that longer term momentum has been stronger than the shorter term pullback.
Scan beyond Energix - Renewable Energies and pressure test your clean power thesis against a hand picked list of solid balance sheet and fundamentals (197 results) in the renewables and infrastructure space.
Energix - Renewable Energies now has a larger Lithuanian project in motion and a share price that has already moved significantly over one year. Does the current valuation still skew the risk reward toward buyers, or has the easy edge passed?
Preferred P/E of 86.8x for Energix - Renewable Energies: Is it justified?
The market is currently valuing Energix - Renewable Energies at a P/E of 86.8x, with the last close at ₪20.31. This points to a rich price tag relative to both its peers and the wider renewable energy group.
The P/E ratio compares what investors pay for each ₪1 of earnings. For a capital intensive renewables operator that develops, finances, and runs wind, solar, and storage projects across Israel, Poland, Lithuania, and the United States, this measure shows how much optimism is embedded in current profits.
Energix - Renewable Energies has seen earnings decline 37.2% over the past year, net profit margins slip from 23.7% to 16.3%, and a Return on Equity of 5.9% that is described as low. Against that backdrop, such a high earnings multiple indicates that the market is paying a steep premium compared with the peer average P/E of 51.2x. It is also much higher than the Asian Renewable Energy industry average of 14.9x, which sets a far lower reference point.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 86.8x (OVERVALUED)
Still, Energix - Renewable Energies faces real pressure if project execution in Lithuania or other markets slips, or if higher financing costs squeeze margins that are already thinner.
Find out about the key risks to this Energix - Renewable Energies narrative.
Another view on Energix - Renewable Energies using our DCF model
A second yardstick tells a very different story. Our DCF model estimates Energix - Renewable Energies future cash flow value at ₪3.85 per share, compared with the recent price of ₪20.31. That gap points to a stock that our DCF work treats as heavily overvalued. Which signal do you trust more when real cash generation is the focus?
Look into how the SWS DCF model arrives at its fair value.
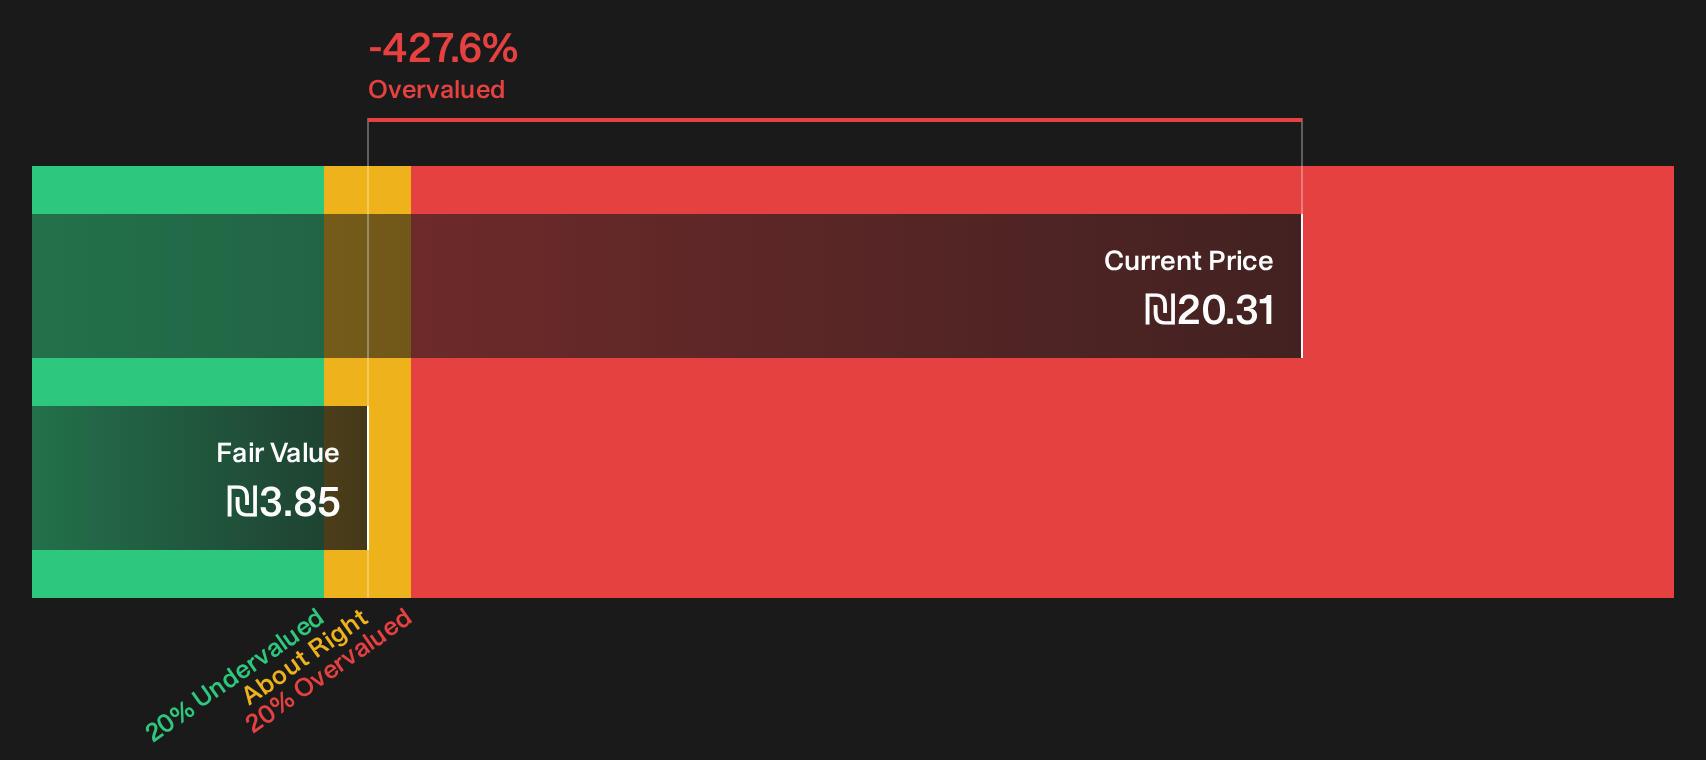
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Energix - Renewable Energies for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 179 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this Energix - Renewable Energies snapshot feels mixed, treat it as a prompt to check the numbers yourself, weigh the risks, and then review the 3 important warning signs.
Looking for more Energix - Renewable Energies investment ideas?
If Energix - Renewable Energies has your attention, broaden your watchlist with a few focused screens that could surface stronger balance sheets, income potential, or mispriced opportunities.
- Target sturdier portfolios and stress test your risk tolerance by scanning a 227 resilient stocks with low risk scores that filters for resilience when markets get choppy.
- Hunt for mispriced opportunities by reviewing a 179 high quality undervalued stocks that blends quality fundamentals with pricing that still looks restrained.
- Lock in potential income streams by focusing on a 155 dividend fortresses that screens for higher yields supported by underlying financial strength.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com