
Warehouse Robot Rollout Could Be A Big Test For GXO Logistics Stock
- GXO Logistics announced that it has successfully deployed the Exotec Skypod System at its Venlo site in the Netherlands, using 127 robots and 60,000 rack locations to support Guess with goods to person picking, quality control and outbound distribution across EMEA and Asia.
- The tailored setup for Guess, with capacity to handle between 40,000 and 70,000 pieces a day and up to 2,200 order lines an hour, shows how GXO Logistics is integrating automation directly into complex fashion logistics, where high SKU counts and sharp seasonal swings can strain manual operations.
- We will look at how GXO Logistics' investment narrative is affected by this high throughput Skypod automation deployment for Guess.
GXO Logistics Investment Narrative Recap
For an investor in GXO Logistics, the core belief is that outsourced warehousing, complex omnichannel contracts and heavy use of automation can support steadier cash generation over time. The Venlo Skypod rollout fits that view, since it shows automation working inside a high SKU, seasonal fashion operation, although on its own it does not materially shift the short term story.
The nearer term upside still leans on execution in e-commerce, new business wins and extracting efficiency from automation and software. The biggest live risk remains execution strain, with Wincanton integration, new leadership and investment heavy projects all happening while interest coverage is flagged as tight and one off items cloud recent financials.
The Exotec Skypod deployment for Guess is the announcement that most clearly ties back to the automation catalyst already in the GXO Logistics narrative. This is a concrete example of the company applying robotics and software at scale, with 127 robots, 60,000 rack locations and goods to person stations working together to handle high order complexity.
For you as a shareholder, the operational question is whether rollouts like Venlo become repeatable across more sites without cost overruns or disruption. If GXO can keep similar systems reliable at peak volumes, it may support the margin story analysts are modelling, while any delays, downtime or customer pushback would amplify the existing execution and earnings quality risks.
GXO Logistics Forecasts Behind the Automation Story
GXO Logistics is being modelled by analysts as a business that keeps layering projects like Venlo on top of a growing earnings base. The consensus view links warehouse robotics and complex contracts to higher profits over time, and the numbers behind that view are important if you are weighing how much automation risk you are comfortable holding.
GXO Logistics' narrative projects US$15.7b revenue and US$415.7m earnings by 2029. This implies 5.2% yearly revenue growth and an earnings increase of about US$283.7m from earnings today of US$132.0m.
Uncover why GXO Logistics' fair value indicates a 54% potential upside to its current price before that gap starts to close.
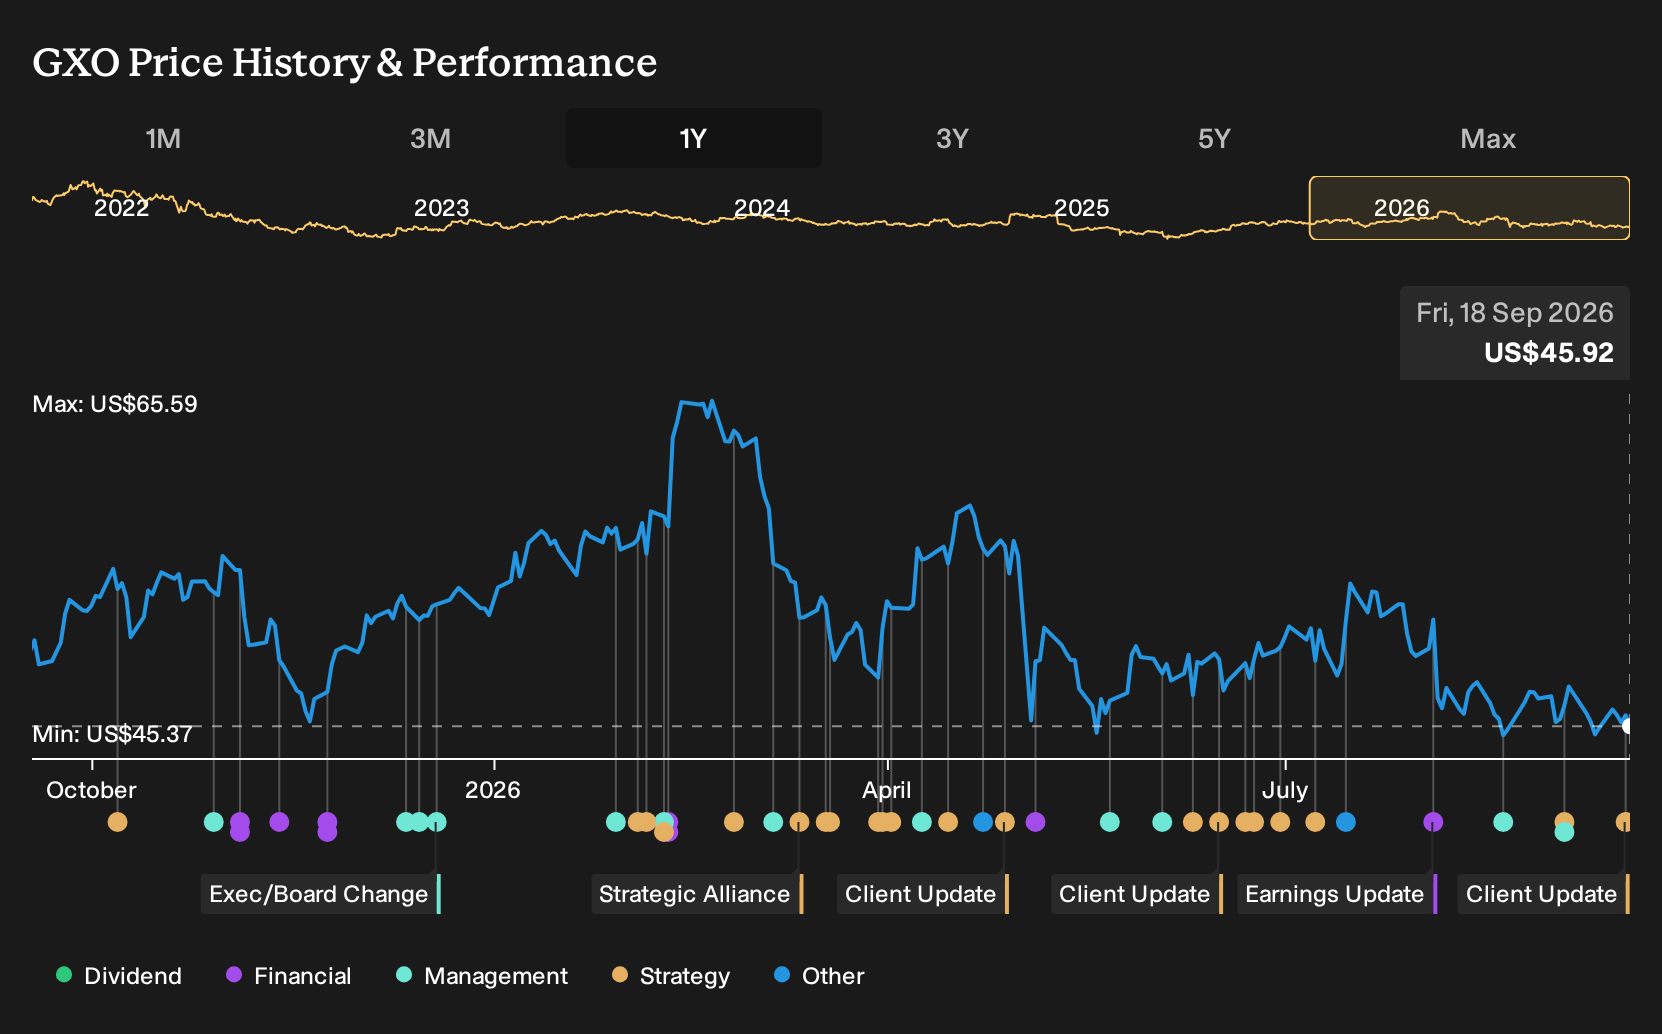
Exploring Other Perspectives
One alternative view focuses on contract risk. The most optimistic analysts, who were already assuming revenue of about US$16.3b and earnings near US$390.8m by 2029, worry that big customers could still insource logistics or shrink volumes. That pessimistic twist might look different once the GXO Logistics Venlo automation news is fully baked into their models.
Explore 3 other GXO Logistics fair value estimates, including one that suggests potential upside of as much as 121% from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your GXO Logistics research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for GXO Logistics. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate GXO Logistics' overall financial health at a glance.
Looking for more investment ideas beyond GXO Logistics?
If the GXO Logistics story has sharpened how you think about automation, contracts and cash flow, it can be useful to cast a wider net and compare it with other businesses that share traits you care about. The Simply Wall St Screener helps you do that quickly by filtering for fundamentals that match your own risk and return preferences.
- If you want potential mispricing with quality fundamentals, start with a focused set of 33 high quality undervalued stocks that pair strong balance sheets and cash flows with a price that may not fully reflect those traits.
- For investors who care most about capital preservation, narrow your search to 30 resilient stocks with low risk scores that score well on volatility and financial strength so you can keep surprises to a minimum.
- If you like the idea of finding tomorrow's GXO Logistics before the crowd, filter for 16 high quality undiscovered gems that already show solid operating metrics despite limited market attention.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com