
Learn Why The Bull Case For First Solar Stock Could Change Following 2026 Guidance Reaffirmation
- First Solar recently reaffirmed its 2026 guidance and continued expanding U.S. manufacturing capacity, supported by domestic policy incentives and a sizeable long term contracted backlog.
- This combination of firm medium term targets and policy backed capacity growth increases the focus on how efficiently First Solar can convert its project pipeline into cash.
- The discussion now turns to how First Solar's reaffirmed 2026 guidance might reshape the investment narrative around cash generation and risk.
First Solar Investment Narrative Recap
To own First Solar, you need to be comfortable with a story built around U.S. focused manufacturing, policy support and a long contracted backlog that stretches through 2030. The key near term catalyst is how efficiently those 45.1 GW of contracted sales and expanding plants translate into cash, not just reported earnings.
The sharp share pullback and reaffirmed 2026 guidance do not materially change the main risk. Policy and demand uncertainty around U.S. utility scale solar and data center projects still loom largest. If project timelines slip or customers push back on pricing, cash conversion from that backlog could prove slower and lumpier than expected.
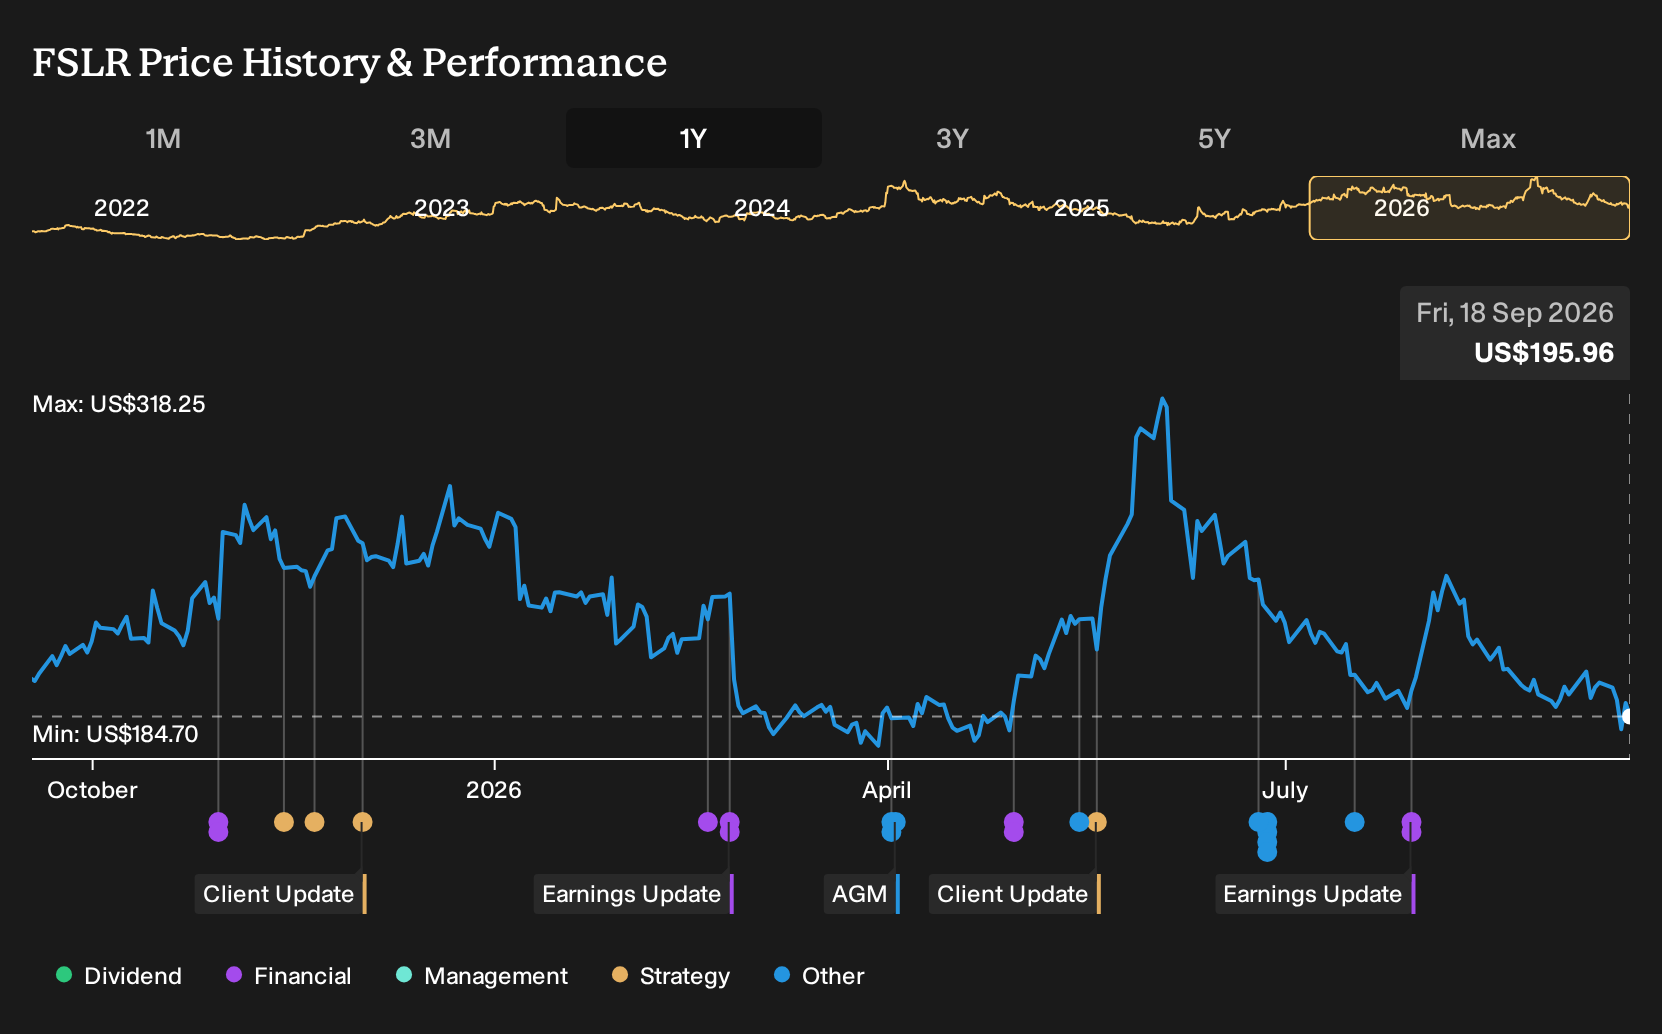
The reaffirmation of First Solar's 2026 guidance alongside ongoing U.S. capacity expansion is the announcement that really matters here. It tells you management is still planning production and spending around the same medium term targets, even as the stock has lagged the Nasdaq and near term revenue expectations look softer.
For you, the link to catalysts is direct. Execution on those new Alabama and Louisiana style facilities, plus existing lines, needs to support volume for that contracted 45.1 GW while keeping unit costs in check. Any signs of construction delays, tariff changes or weaker large scale solar demand would quickly move from background worry to front line risk.
First Solar's narrative projects US$6.8b revenue and US$3.0b earnings by 2029. This implies 8.2% yearly revenue growth and an earnings increase of about US$1.3b from US$1.7b today.
Discover how First Solar's fair value points to a 40% potential upside to its current price before the market closes the gap.
Exploring Other Perspectives
One alternative view focuses on earnings power rather than policy risk. The most optimistic analysts were expecting about US$7.8b of revenue and US$4.3b of earnings by 2029 for First Solar, compared with the consensus of US$6.8b and US$3.0b. That is a much brighter story, and this latest guidance update may prompt those narratives to adjust.
Explore 4 other First Solar fair value estimates, including one that suggests as much as 90% upside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your First Solar research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for First Solar. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate First Solar's overall financial health at a glance.
Looking For More Ideas Beyond First Solar?
If the First Solar story has sharpened your focus on cash generation, balance sheets and contract quality, the next step is to widen your opportunity set using the Simply Wall St screener.
- For investors who want quality at a reasonable price, start with a curated set of 33 high quality undervalued stocks that pair solid fundamentals with room for sentiment to catch up.
- If resilience matters most to you, filter for steadier profiles by scanning a focused 30 resilient stocks with low risk scores that aims to limit unpleasant surprises.
- For those hunting earlier stage potential with financial guardrails, consider a 8 elite penny stocks with strong financials that concentrates on smaller companies with relatively stronger balance sheets.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com