
Adient (ADNT) Names A Board Member CFO, Is The 44% Undervaluation Case Convincing?
Why Adient Stock Is Back In Focus After A Boardroom Shake-Up
Adient (NYSE:ADNT) is back on investors radar after board member Peter Carlin agreed to step down and move into management as chief financial officer, while the board trims its size.
Recent trading tells a different story to the boardroom headlines. Adient’s share price is down 4.3% on the day to US$17.68 and has retreated 9.9% over the past month, with a 1-year total shareholder return that has declined 28.1% and a 5-year total shareholder return that has fallen 56.6%. This points to fading momentum even as management reshapes leadership and governance.
Spot opportunities where boardroom shifts and price pressure intersect by reviewing the hand-picked 33 high quality undervalued stocks that share some of Adient’s characteristics.Bulls see Adient as a beaten up auto supplier with internal change and analyst targets indicating a gap to intrinsic value. Bears point to weak multi year returns and soft momentum. Which case does the current valuation lean toward?
Most Popular Narrative: 44% Undervalued
Adient’s most followed valuation story pegs fair value at about $31.42 per share, well above the last close at $17.68. This puts the current boardroom changes against a backdrop of a stock already framed as discounted by that narrative.
Adient's strategic focus on U.S. onshoring, underpinned by its production footprint (75% of North American capacity in the U.S. versus 55% for its nearest competitor), is associated with net new business wins with Asia-based and domestic OEMs. Minimal incremental capital needs are expected to support incremental revenue and margin improvement as volumes ramp into FY2026-27.
See why 5 investors see Adient as 44% undervalued.
Result: Fair Value of $31.42 (UNDERVALUED)
Still, that upside story can crack if Adient’s restructuring in Europe drags on cash flow, or if OEM sourcing shifts away from its seating programs faster than expected.
Find out about the key risks to this Adient narrative.
Another View On Adient’s Valuation
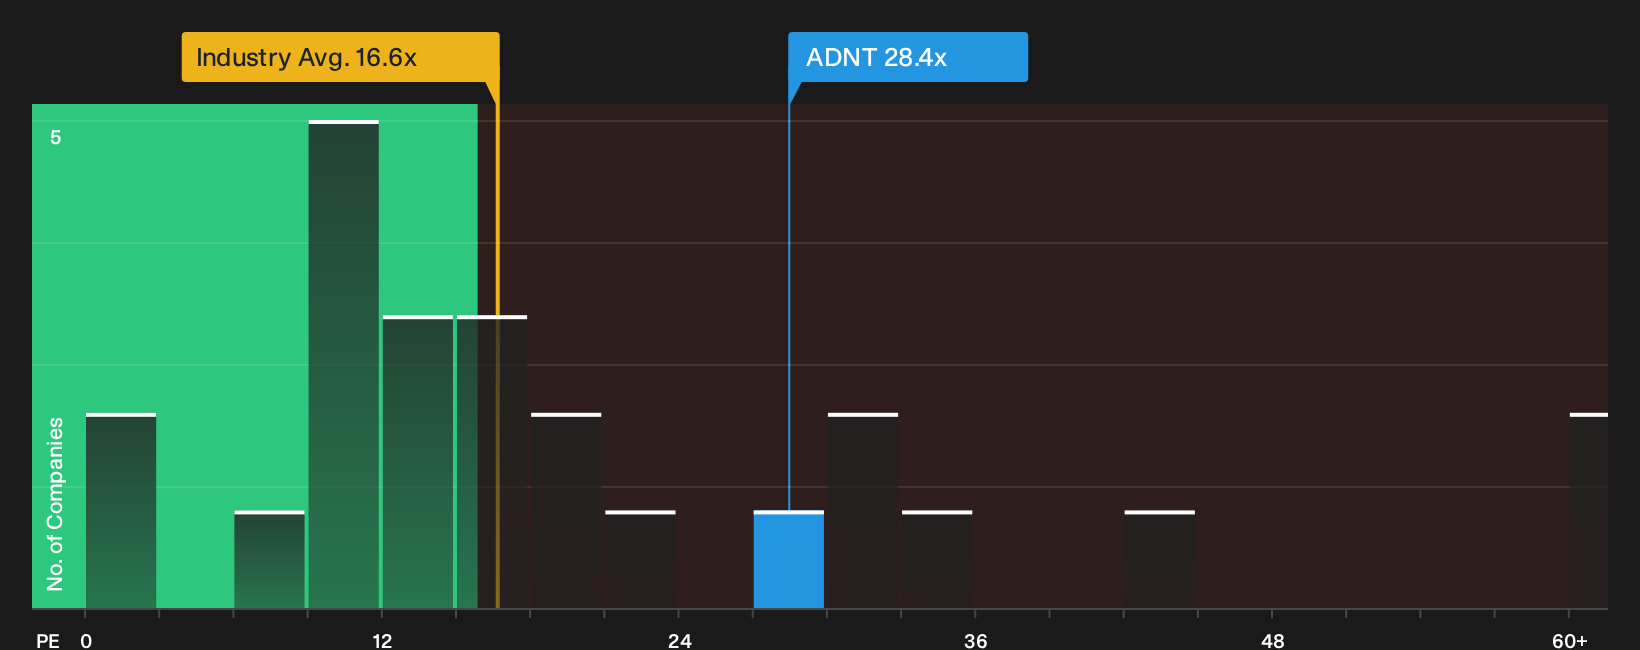
The first story paints Adient as 44% undervalued, yet the P/E tells a different tale. At 28.4x earnings, the shares trade above the US Auto Components average of 16.7x, the peer group on 22.8x, and even the 27.9x fair ratio estimate. Is that a margin of safety or a valuation trap?
For a closer look at how those earnings multiples stack up against the underlying numbers, and what that gap might mean for upside or downside risk, See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
If the split sentiment on Adient has you torn, move quickly from headline impressions to hard numbers and pressure test both sides for yourself with 3 key rewards and 2 important warning signs.
Looking for more ideas beyond Adient?
If Adient has sharpened your focus on pricing and risk, do not stop here. Put a few more quality candidates on your radar before the next move.
- Explore stocks with notable price targets by scanning a curated pool of quality candidates through the 16 high quality undiscovered gems.
- Prioritize resilience by filtering for companies with durable finances using the list of solid balance sheet and fundamentals (23 results).
- Raise your income focus by zeroing in on consistent dividend payers with the 6 dividend fortresses.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com