
How $1.1b Debt Placement Will Impact TMX Group Stock Investors
- TMX Group completed a private placement of $1.1b in senior unsecured debentures to institutional investors, with proceeds earmarked for refinancing existing debt and for general corporate purposes.
- This move reshapes TMX Group's funding mix by relying on unsecured debt at the top of the capital stack, which could affect flexibility for future investments and balance sheet resilience.
- We will now look at how TMX Group's investment narrative could be influenced by this $1.1b senior unsecured debenture placement.
Compare TMX Group's funding shift with other balance-sheet focused stories by scanning a handpicked 8 resilient stocks with low risk scores that may appeal if you care about resilience as much as returns.
TMX Group Investment Narrative Recap
To own TMX Group, you need to be comfortable with an exchange operator that leans heavily on trading, listings, and data, and is also investing in derivatives and analytics for future revenue streams. The new CA$1.1b senior unsecured debenture issue mainly looks like balance sheet housekeeping, so it may not change the near term focus on derivatives growth and data driven recurring income.
The near term swing factor is how consistently TMX Group can translate higher trading and clearing activity into earnings, while keeping recent cost pressure in check. The key risk remains competition from alternative funding channels and global exchanges, which could soften listing momentum and reduce operating leverage if volumes cool.
With no other recent announcements flagged alongside this debenture placement, the bond deal itself becomes the most relevant update for the current TMX Group story. It refines the funding stack with more unsecured obligations, which matters because the group already relies fully on external borrowing rather than lower risk customer deposits.
For you, the question is whether this capital structure fits an exchange that is pushing derivatives, data analytics and digital platforms as its main catalysts. Execution risk on technology programs, combined with higher risk funding and potential margin pressure from IT and regulatory spend, gives this debt raise real operational context even if it mostly refinances older obligations.
TMX Group's current analyst story points to CA$2.3b in revenue and CA$752.4m in earnings by 2029, built on an assumed 9.1% yearly revenue growth rate and an earnings increase of about CA$218m from CA$534.4m today.
Uncover how TMX Group's fair value indicates a 21% potential upside to its current price. This opportunity could narrow quickly if TMX Group's story gains broader attention.
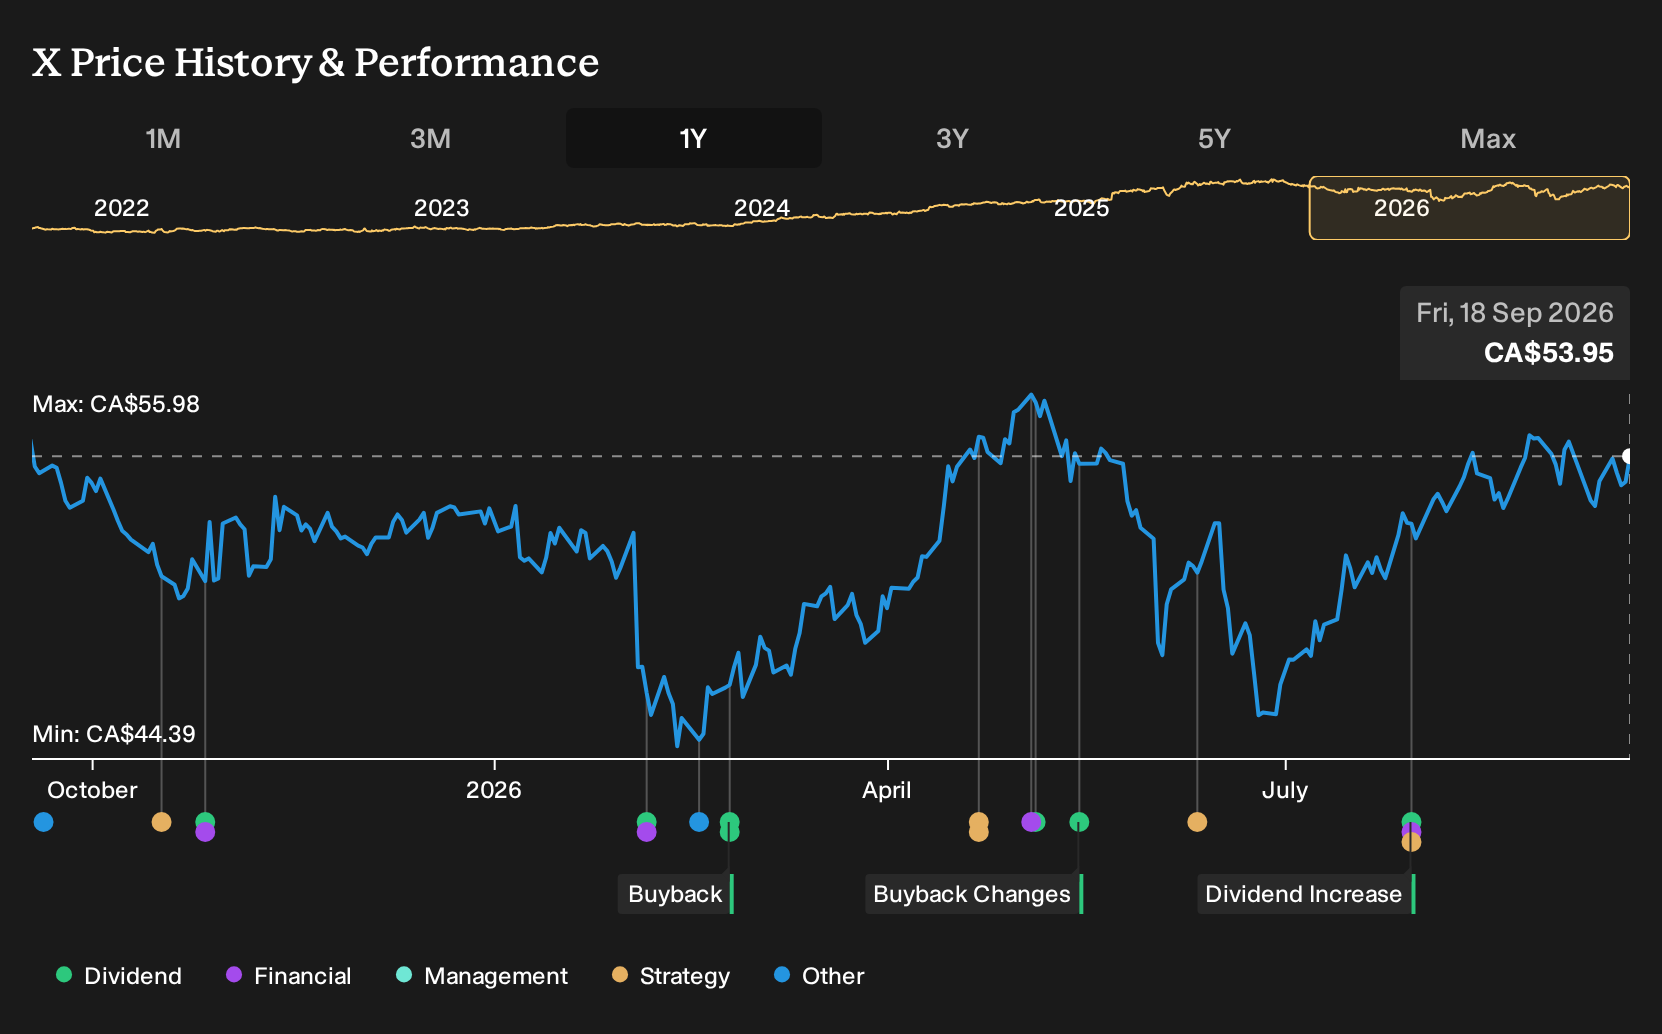
Exploring Other Perspectives
Across four fair value views from the Simply Wall St Community, TMX Group sits in a wide band from CA$30.87 to CA$65.43, which shows retail investors are far from aligned on upside. When this is considered alongside risks from private markets, global exchange competition, and blockchain, the case for checking multiple viewpoints becomes clear.
Explore 3 other TMX Group fair value estimates, including one that suggests as much as 43% downside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your TMX Group research is our analysis highlighting 4 key rewards that could impact your investment decision.
- See our latest analysis for TMX Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate TMX Group's overall financial health at a glance.
Looking For More TMX Group Style Investment Ideas?
If TMX Group has you thinking about balance sheet strength, income potential, and finding opportunities at sensible prices, it makes sense to widen the search using a broader stock screener.
- For investors who focus on quality at a reasonable entry point, consider a curated set of companies trading below estimated value using the Simply Wall St screener with 4 high quality undervalued stocks.
- If steady income matters to you, use the income focused screener on Simply Wall St to review 1 dividend fortresses that might suit a yield oriented watchlist.
- When capital preservation and financial strength come first, filter for resilient businesses through the Simply Wall St screener and review a list of solid balance sheet and fundamentals (7 results).
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com