
Should Dividend Cut Require Action From Conagra Brands (CAG) Investors?
- Conagra Brands has reset its playbook after several difficult years by taking a large impairment that drove a reported loss, halving its dividend, and committing more cash to brand support and supply chain upgrades, while rolling out new "GLP-1 friendly" labels across parts of the portfolio.
- The push into "GLP-1 friendly" labeling hints at Conagra Brands trying to align packaged foods with weight loss drug users, which could reshape how its core categories are perceived on health and portion control.
- We will now see how Conagra Brands' refreshed priorities, especially the 50% dividend cut, could reshape its longer term investment narrative.
Conagra Brands Investment Narrative Recap
To stay invested in Conagra Brands, you need to believe the reset eventually turns flat revenues into cleaner, higher quality earnings. The thesis leans on supply chain upgrades, steady demand for packaged food and the ability to support brands without eroding already pressured margins. The short term swing factor is simple: can management convert higher operating spend into visible profit traction rather than just higher costs?
The biggest near term risk sits on the other side of that same coin. Inflation, lingering logistics costs and any slowdown in key channels could keep gross margin under strain at the very moment Conagra Brands is leaning into more brand and productivity investment.
The 50% dividend cut is the clearest operational signal in this reset. Cash that previously went to shareholders is now being earmarked for brand support and supply chain projects, which directly connects to the margin and earnings recovery narrative. That shift also intersects with concerns that debt is not yet well covered by operating cash flow.
For you, the question is whether this reallocation improves resilience or simply reduces income without enough payback. If supply chain spending shortens disruptions and product refreshes like GLP 1 friendly labels keep volumes steady, the dividend change could support the main catalyst. If not, it adds another layer of risk to Conagra Brands at a time when revenue is expected to remain flat.
Conagra Brands' story centers on analysts expecting revenue of US$11.3b and earnings of US$834.3m by 2029, based on flat top line assumptions and a move from a reported loss of US$43.3m today to positive profits. That shift implies an earnings change of about US$877.6m between current results and the 2029 consensus target.
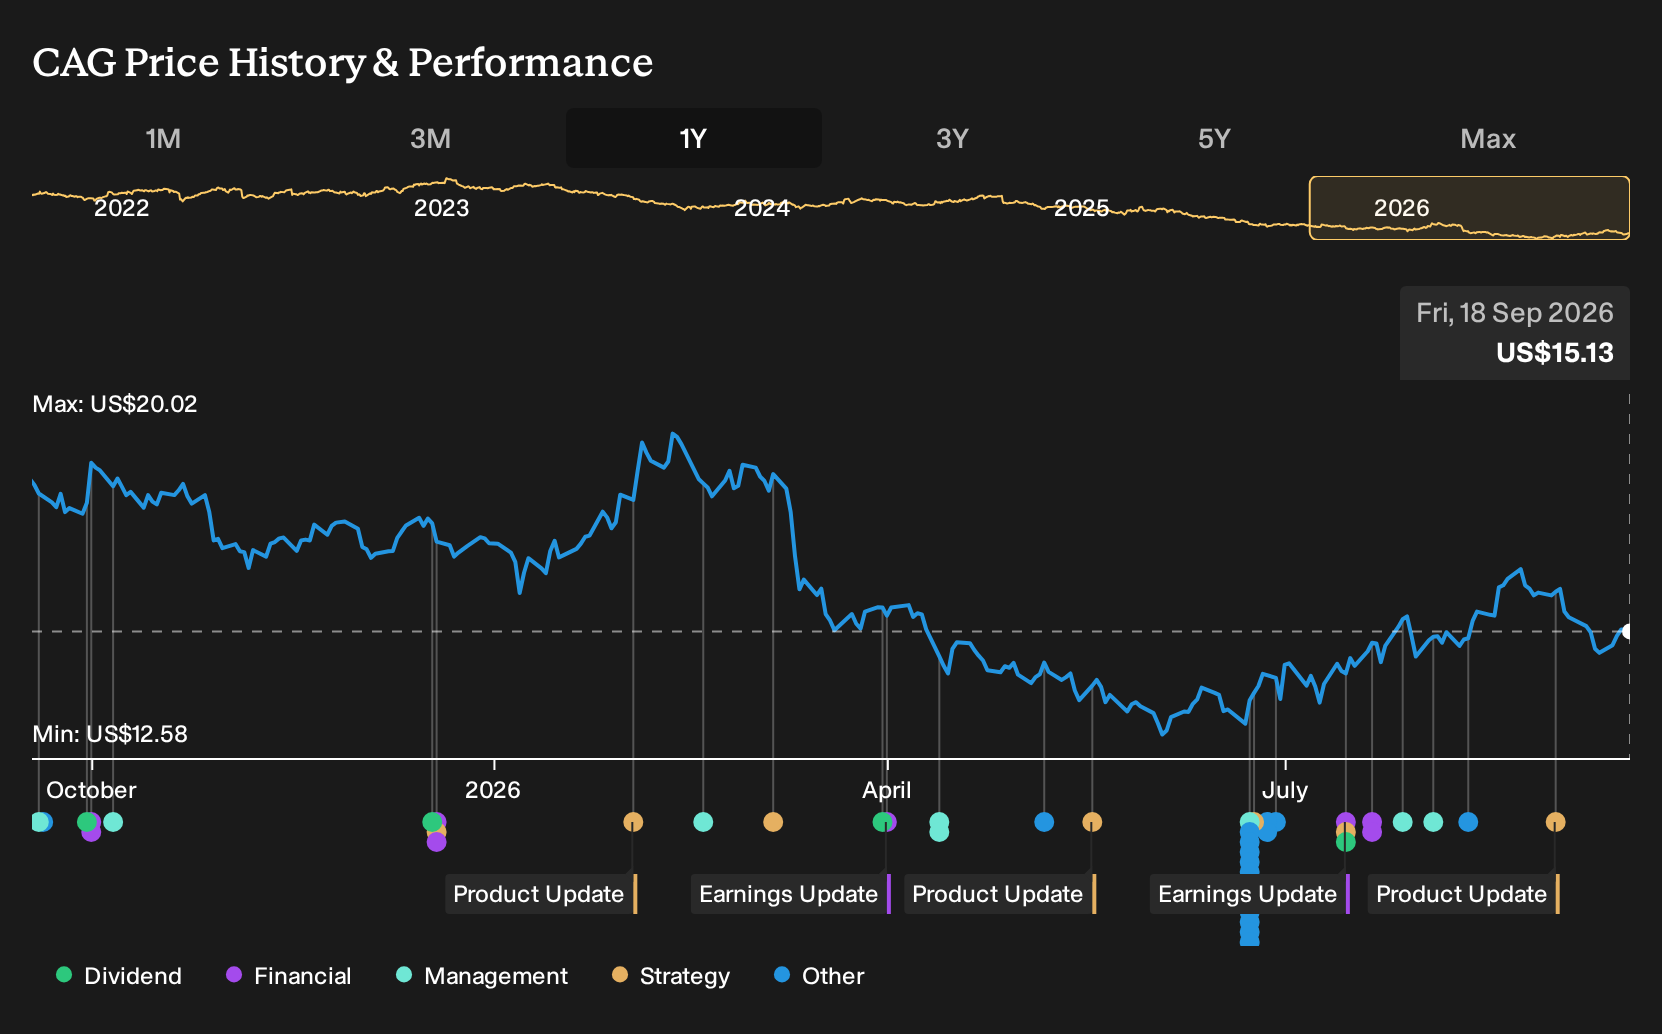
Uncover why Conagra Brands' fair value indicates a 4% potential downside to its current price, which leaves little room for error.
Exploring Other Perspectives
For a different angle on Conagra Brands, focus on the bullish catalyst around supply chain modernization and digital upgrades. The most optimistic analysts were penciling in about US$11.5b of revenue and US$979.7m of earnings by 2029, far above the most cautious US$742.9m view. That gap shows how widely opinions can differ. Use this reset, including the dividend cut and GLP 1 friendly push, as a reason to compare several narratives rather than rely on just one.
Explore 8 other Conagra Brands fair value estimates, including one that suggests potential upside of as much as 211% from the current price!
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Conagra Brands research is our analysis highlighting 2 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Conagra Brands. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Conagra Brands' overall financial health at a glance.
Looking For More Investment Ideas Beyond Conagra Brands?
If the Conagra Brands reset has you rethinking where capital might work harder, you can broaden the search using the Simply Wall St Screener to line up other opportunities side by side and pressure test your thesis before committing new money.
- Prioritize financial strength first by scanning a list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses with sturdier fundamentals.
- Reduce the focus on volatility and filter for steadier candidates through a 30 resilient stocks with low risk scores tailored to resilience.
- Hunt for underappreciated potential by checking a 16 high quality undiscovered gems that surfaces quieter stories with robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com