
Wall Street’s Favorite Safe Haven Could Be In Trouble. How Investors Should Play Gold Here.
Is there any investment market segment more debated than gold (XAUUSD)? I’m not sure there is. We have “gold bugs,” including those who see the yellow metal as the asset to own when the world goes haywire.
Then, there are the “we’re going back on the gold standard” types. The ones that preceded crypto bros in believing fiat currencies weren't for this world. It follows that gold would return to its former role as the reserve currency.
Of course, there are also plenty of investors who don’t really think about gold investing very much, and who will simply trade it when there’s a good opportunity. I’m in this camp.
Financial media pundits routinely tout gold as some sort of bulletproof allocation. Inflation worries? Own gold. Currency debasement? Own gold. Want your kitchen to be decorated like the Oval Office? You’ll need a lot of gold.
Yet despite the relentless cheerleading, holding gold, whether via physical bullion or popular proxies like the SPDR Gold Shares ETF (GLD), looks increasingly to be something other than a sure thing.
What's Going On With Gold?
To me, gold, and investing in it via exchange-traded funds (ETFs) like GLD and the iShares Gold Trust (IAU), is often a solution in search of a problem. Oh, it trades well at times. And there are 2x inverse ETFs, like Ultrashort Gold -2X ETF (GLL) and the Ultra Gold 2X ETF (UGL), that can be used to profit from short-term drops in the price of gold. But I have never personally seen the long-term argument hold up.
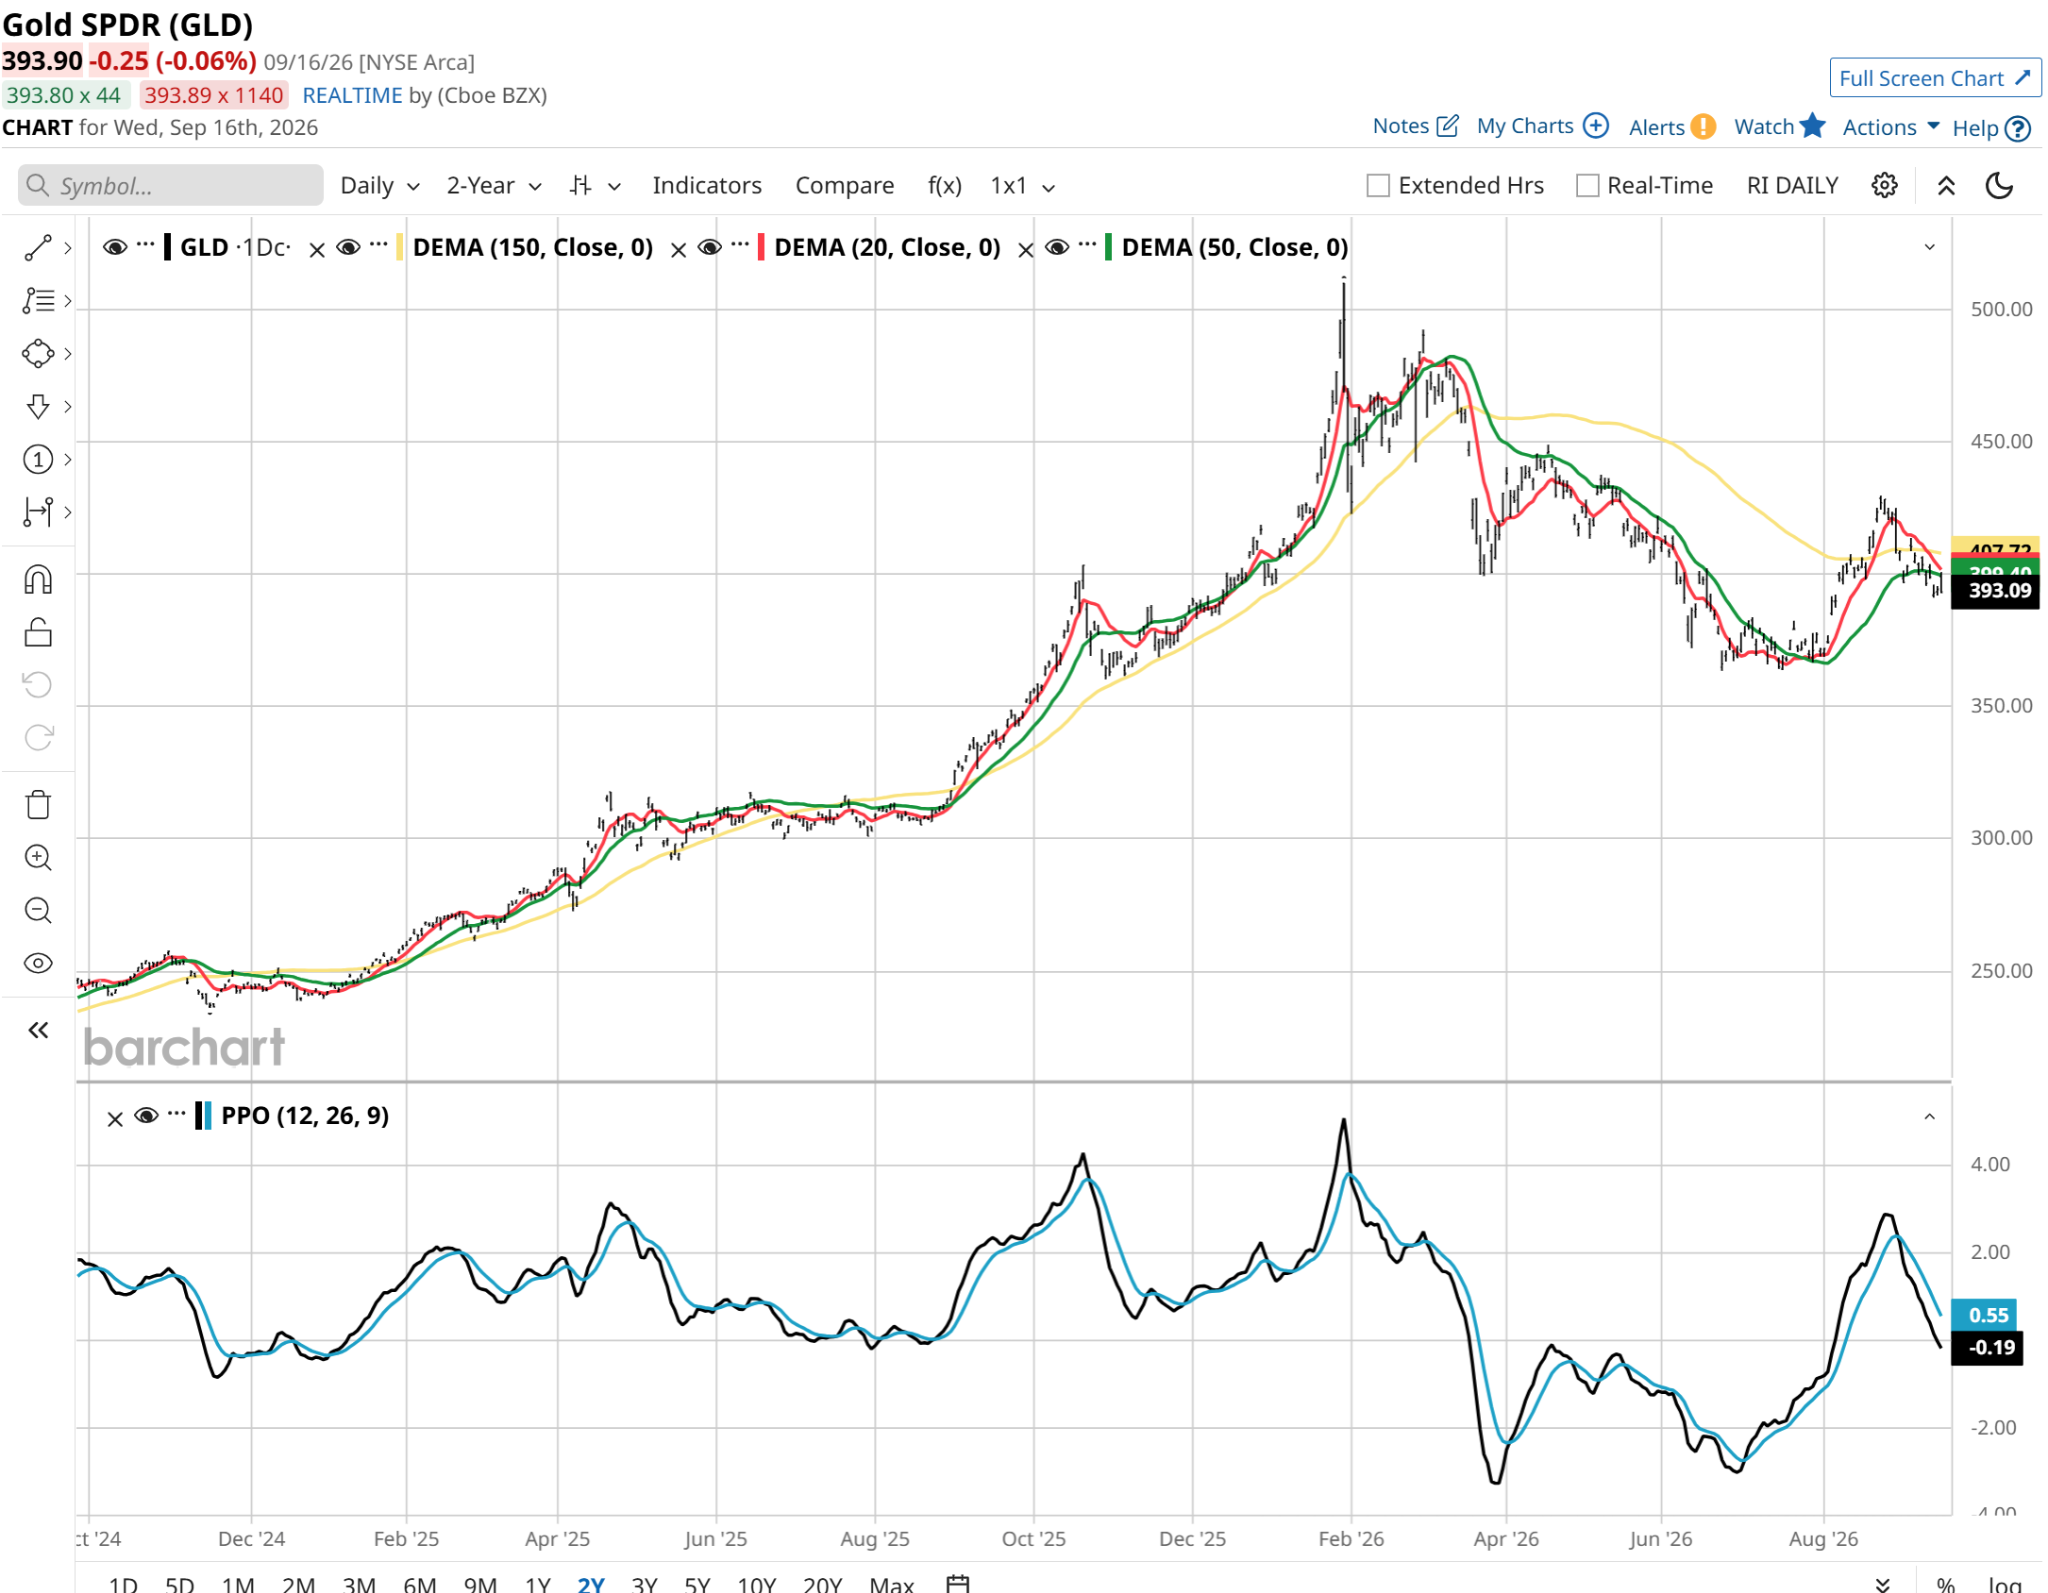
Here’s a daily price chart. Nothing special going on here, other than a hint of more downside coming. And given the spike in price this past summer, a 10% pullback on top of the recent slippage is on the table.
Below, this monthly chart goes back 20 years. And I’ve labeled three gigantic rallies, each lasting about 18 months to two years. A triple (200% gain), a double (100%), and another triple. GLD has increased tenfold over two decades. That’s very impressive. But 70% of the time, there wasn’t much going on. Just a lot of up and down, leading to nowhere.
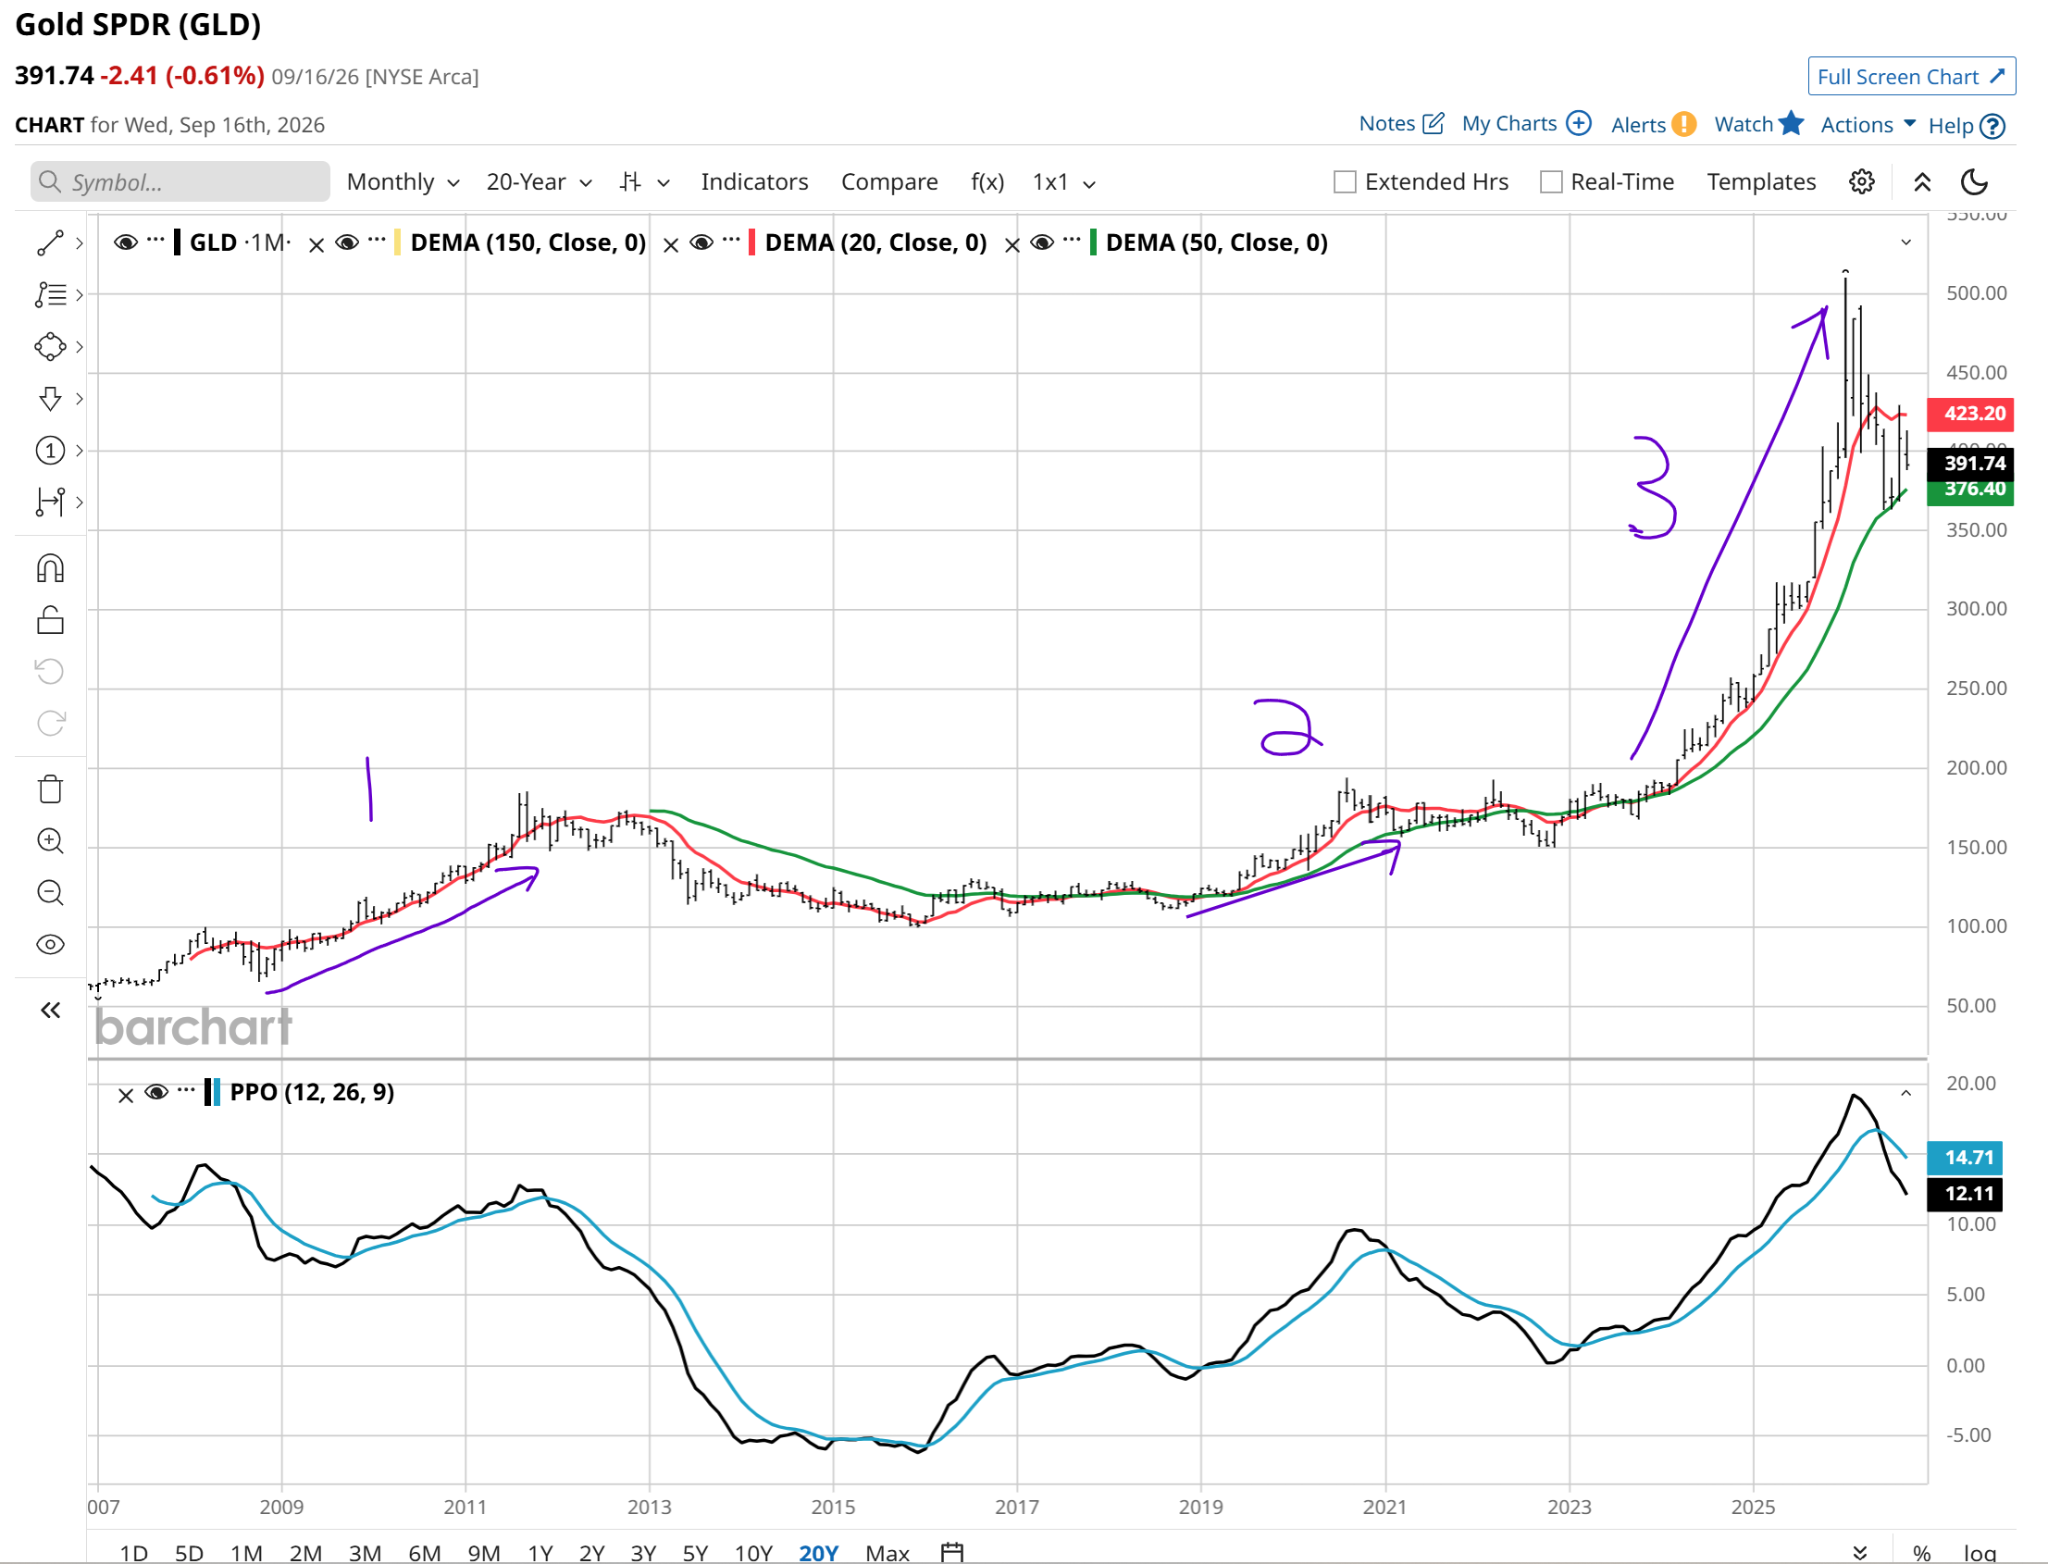
This article is ultimately trying to look ahead. The long-term PPO above is at best concerning to me, so my conclusion on GLD and other ETFs like it is a case of the same old, same old. A 25% rally to the all-time high area around $500 is still on the table.
However, the risk against that is a crash to $200, which would simply retrace two years of progress. That’s just not a good enough risk-return profile for me. Trading gold? Yes, probably a few times a year in my case. But owning gold? Not for me.
The Bottom Line
The fundamental flaw in the gold narrative comes down to basic math: gold is a non-productive asset. It produces no cash flow, pays no coupon, and generates no corporate dividends. When short-term Treasury bills pay now-solid yields, and target-maturity bond ladders allow investors to lock in 4.5% to 5.5% cash flows with a defined endpoint, I just don’t see gold as more than a bit player.
Rob Isbitts is a semi-retired CIO, former fiduciary investment advisor, and Barchart columnist. Check out his other work at ETFYourself.com (featuring the Fresh Charts weekly trading post), and ROAR.PiTrade.com, helping investors to better-manage their own portfolios.
On the date of publication, Rob Isbitts did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes. For more information please view the Barchart Disclosure Policy here.