
How Investors May Respond To NextEra Energy Stock As Merger Concerns Grow
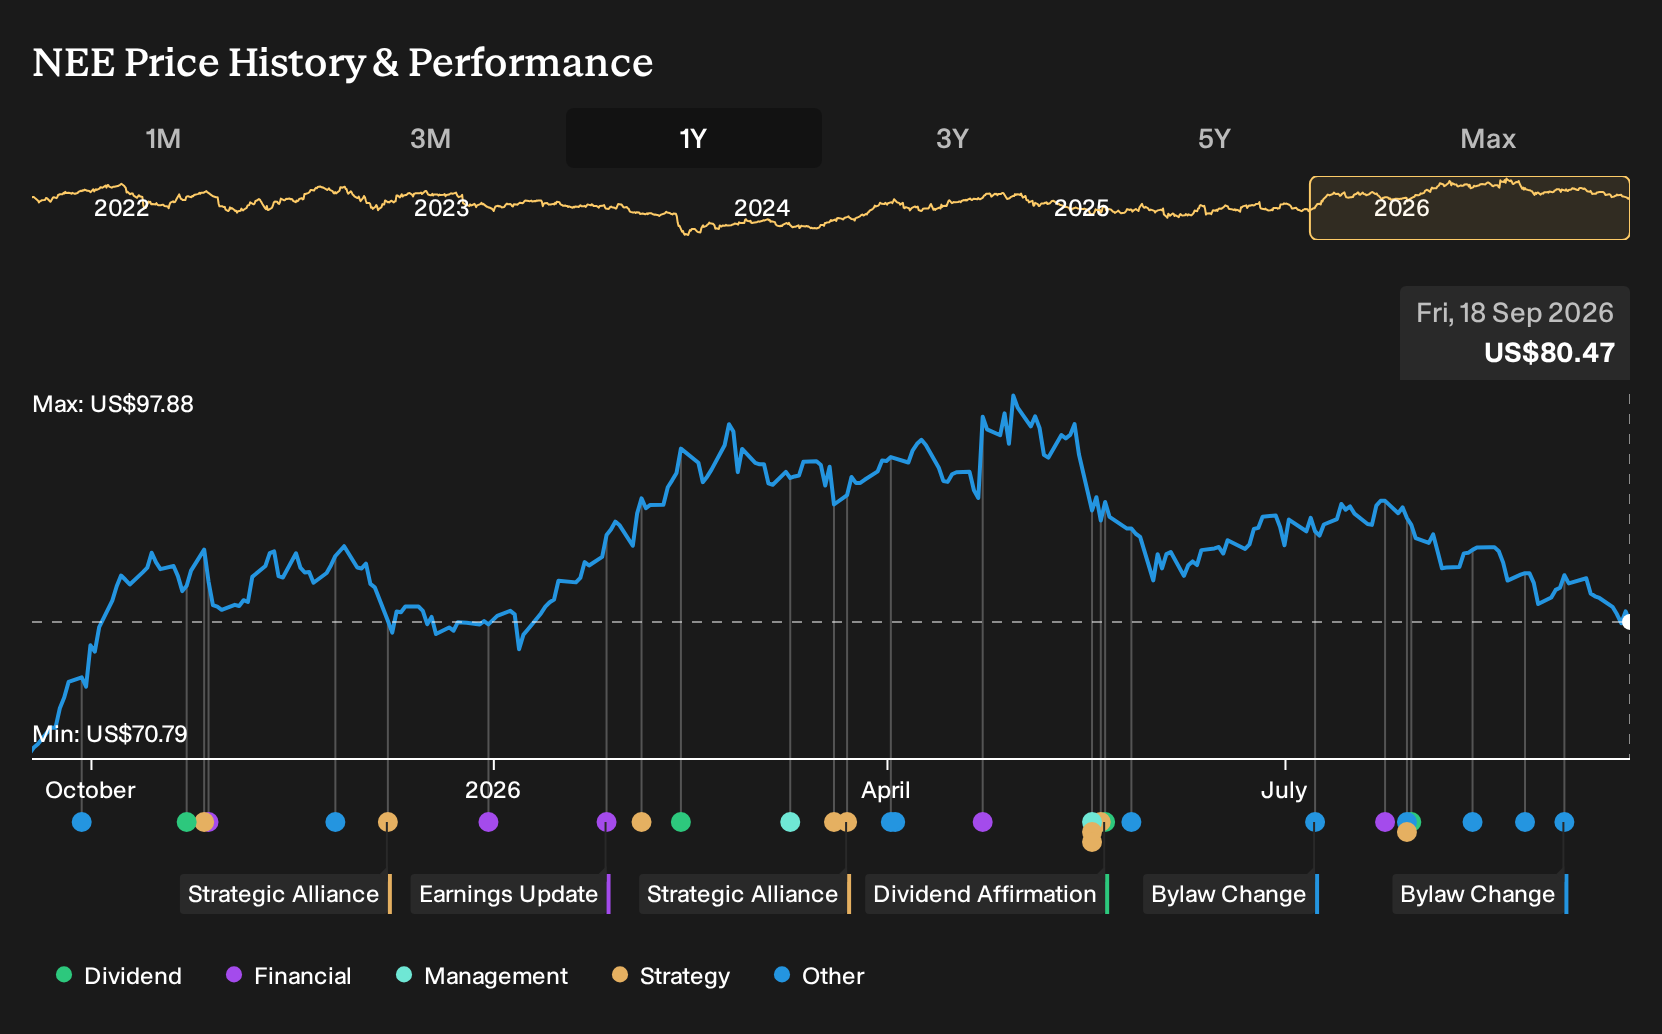
- NextEra Energy recently reported mixed Q2 2026 results, with adjusted EPS above expectations but revenue below forecasts, as rising interest rates and regulatory uncertainty weighed on its capital intensive renewable and utility operations.
- Investor focus has shifted toward execution risk around the pending Dominion Energy merger and how higher financing costs could affect project economics and long term returns on new infrastructure.
- This article examines how NextEra Energy's investment narrative is being tested as higher rates coincide with new merger and regulatory uncertainty.
Stress test your clean energy thesis beyond NextEra Energy by scanning a curated pool of regulated utilities and renewables peers through: 38 power grid technology and infrastructure stocks
NextEra Energy Investment Narrative Recap
To own NextEra Energy, you need to believe that large scale renewables and a big regulated utility like Florida Power & Light can still earn acceptable returns despite higher rates, policy shifts and the capital load of the Dominion Energy merger. The Q2 2026 mix of earnings strength and revenue softness, together with rising financing costs, keeps that belief in focus rather than breaking it.
In the near term, execution on the Dominion deal and keeping project returns intact under higher interest expenses look like the key swing factors. Regulatory decisions around tax credits, permitting and Florida rate outcomes remain the biggest risk, since they directly affect project timing, allowed returns and the cash needed for dividends and expansion.
The most relevant recent signal is not a corporate press release but the market and media reaction highlighted by Jim Cramer turning bearish on NextEra Energy after Q2 2026. His focus on higher rates, the Dominion merger and regulatory uncertainty closely matches the core operational pressure points for the business right now.
For you as a shareholder, that commentary highlights the same issues you should be watching. Can NextEra Energy keep funding heavy capital spending when interest payments are already not well covered by earnings and dividends are not fully supported by free cash flow? The main near term catalyst is clear execution evidence that new projects and the merger can still meet the company’s return hurdles under tougher financing and policy conditions.
NextEra Energy's narrative projects US$39.0b in revenue and US$10.4b in earnings by 2029. That profile assumes 11.9% yearly revenue growth and an earnings increase of about US$2.2b from current earnings of US$8.2b.
Uncover why NextEra Energy's fair value indicates a 22% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest analysts focus almost entirely on financing risk for NextEra Energy. Before this latest news, they were working off revenue reaching about US$33.0b and earnings of US$9.8b by 2029. That is well below consensus. It reflects a view that higher rates and tighter credit conditions could reshape today’s cleaner baseline forecasts.
Explore 9 other NextEra Energy fair value estimates, including one that suggests as much as 5% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your NextEra Energy research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for NextEra Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate NextEra Energy's overall financial health at a glance.
Looking for more investment ideas beyond NextEra Energy?
If the NextEra Energy story has you rethinking how you allocate capital to utilities and clean energy, it can help to widen the lens and compare it with other potential opportunities that share some of the same traits, or avoid some of the same risks.
- If you want to focus on quality at a reasonable entry point, scan a curated pool of companies flagged for valuation support through 33 high quality undervalued stocks.
- If resilience matters more to you than excitement, start with a universe of businesses filtered for balance sheet strength by running the list of solid balance sheet and fundamentals (23 results).
- If you are hunting for fresh ideas that are not already widely followed, broaden your watchlist with the 16 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com