
Will Earnings Miss Change La Z Boy Stock Narrative
- La-Z-Boy recently reported fiscal first quarter results with adjusted earnings, revenue and second quarter sales guidance all coming in below analyst expectations, which has prompted Bronstein, Gewirtz & Grossman, LLC to investigate potential claims on behalf of shareholders.
- The combination of weaker fundamentals and new legal scrutiny highlights how pressure on La-Z-Boy's demand profile, pricing and execution can quickly feed into governance and risk concerns for investors.
- We will look at how La-Z-Boy's investment narrative around expansion and efficiency is pressured by weaker earnings and cautious sales guidance.
Shift your focus from La-Z-Boy's legal and earnings pressure to a hand-picked 30 resilient stocks with low risk scores that may better fit a cautious risk profile.
La-Z-Boy Investment Narrative Recap
To own La-Z-Boy, you need to believe its push into more company-owned stores, omnichannel retail and a leaner distribution network can offset a choppy furniture cycle and pressure on discretionary spending. The weak first quarter and softer second quarter sales outlook point to near term demand and pricing challenges, but they do not fundamentally change that expansion and efficiency story.
Right now, the key near term catalyst is execution on the retail rollout and distribution consolidation without further margin strain. The biggest risk is that softer traffic, heavier promotions and underperforming areas like Joybird and international wholesale keep dragging on profitability while capital remains tied up in new stores and the supply chain project.
The immediate trigger for the legal review was La-Z-Boy’s fiscal first quarter report, where adjusted earnings, revenue and near term sales guidance came in below analyst expectations and the share price dropped. That announcement matters because it brings the operational issues into sharper focus and adds an extra governance overhang just as the business works through expansion and restructuring.
For you as an investor, that update puts more weight on how management handles margin pressure, promotions and underperforming segments while still funding store growth and the multiyear distribution shift. In the short term, any further disappointments around same store sales or profitability could slow confidence in those longer term catalysts, even if the broader retail and supply chain plans remain intact.
La-Z-Boy's current narrative focuses on analysts expecting revenues of $2.2b and earnings of $119.9 million by 2029, based on 1.6% yearly revenue growth and an earnings increase of about $38.4 million from $81.5 million today.
Uncover why La-Z-Boy's fair value indicates a 37% potential upside to its current price, which could narrow quickly.
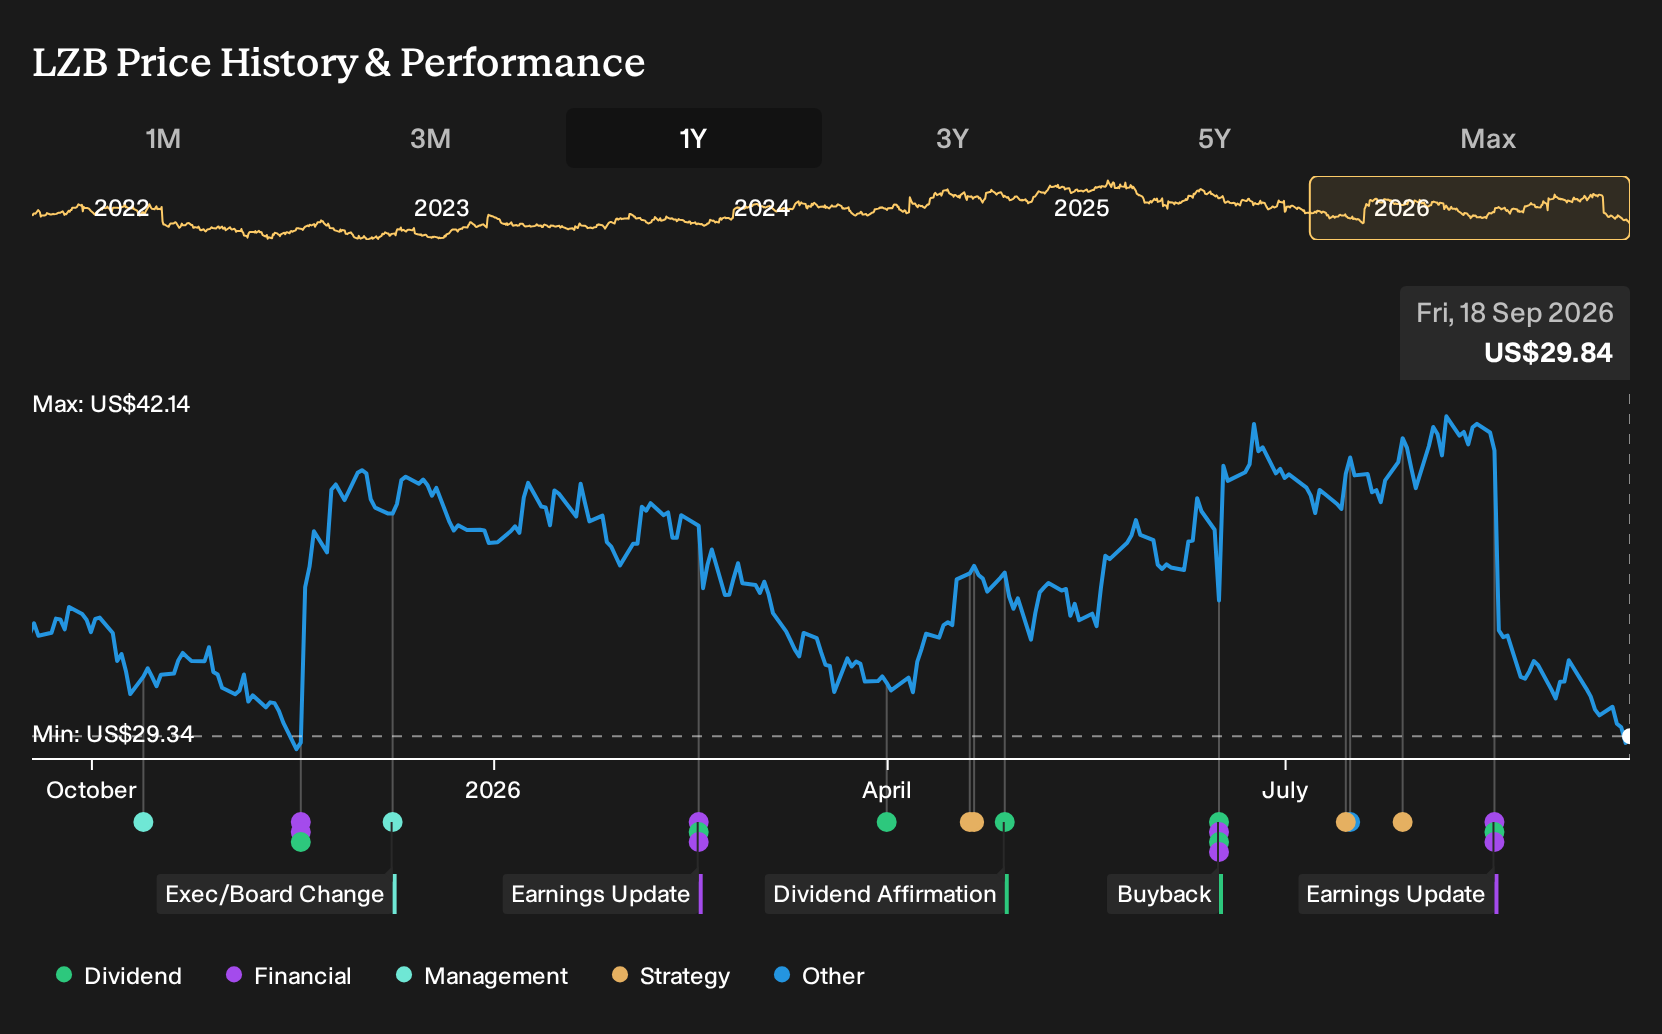
Exploring Other Perspectives
The most striking alternate risk around La-Z-Boy is the idea that brick-and-mortar expansion itself could be the problem. The most cautious analysts were already assuming roughly flat revenue near $2.2b and earnings of about $156.7 million by 2029 before this earnings miss and legal review. That is a far tougher narrative. Use it as a prompt to compare multiple viewpoints and consider how this news might reshape them.
Explore 3 other La-Z-Boy fair value estimates, including one that suggests it could be worth just $41.00!
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis carefully.
- A great starting point for your La-Z-Boy research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for La-Z-Boy. The report includes a fundamental analysis summarized in a single visual, the Snowflake, making it easier to evaluate La-Z-Boy's overall financial profile at a glance.
Looking For More Investment Ideas Beyond La-Z-Boy?
If La-Z-Boy's mix of expansion plans, legal questions and earnings pressure feels too tight for comfort, it can help to widen the search and compare it with other opportunities that better match your risk tolerance and income needs.
- If capital preservation comes first for you, consider starting with a 30 resilient stocks with low risk scores that aims to prioritize resilience over excitement.
- Income focused investors who want their portfolio to work harder for them might prefer a curated set of 6 dividend fortresses built around higher yields.
- For readers hunting for mispriced opportunities, a hand picked universe of 33 high quality undervalued stocks can help surface ideas that merit a closer look.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com