
UK Residential REIT Stocks Facing The Biggest Local Housing Allowance Questions
The debate over Local Housing Allowance has moved from policy niche to front-page risk, and that shift matters for anyone watching UK residential REITs and listed landlords. Changes to how support is funded and paid could reshape rent collection patterns, arrears trends and sentiment around housing exposure. This article unpacks the story and walks through three stocks from our screener that appear most exposed to the current news flow.
The three UK residential REITs and landlords below are just a starting sample from this LHA-exposed corner of the market. The full screen surfaced 13 more companies with equally detailed narratives that are not covered here. To identify and analyze your own highest conviction ideas in this space, head straight to the UK Residential REITs and Listed Landlords screener.
Living REIT (LSE:LIVE)
Overview: Living REIT is a UK-listed landlord investing in social homes to deliver rental income and potential capital growth from residential tenants.
Operations: Living REIT generates about £40.8 million of rental income from its UK residential REIT portfolio, entirely within the United Kingdom.
Market Cap: £287.2 million
Living REIT gives you direct exposure to UK residential rents in social housing at a time when Local Housing Allowance policy is under review. The trust has recently turned profitable and is paying property income distributions. It still carries leverage and funding risks that matter for income resilience, and a single unresolved pressure on rent support could significantly affect how secure that cash yield appears.
That uncertainty around how secure the cash yield really is makes it worth pulling up the 3 key rewards and 2 important warning signs (1 is major!) to see what might be masking or amplifying it.

Land Securities Group (LSE:LAND)
Overview: Land Securities Group is a major UK landlord focused on prime offices, retail destinations and a growing pipeline of urban residential projects.
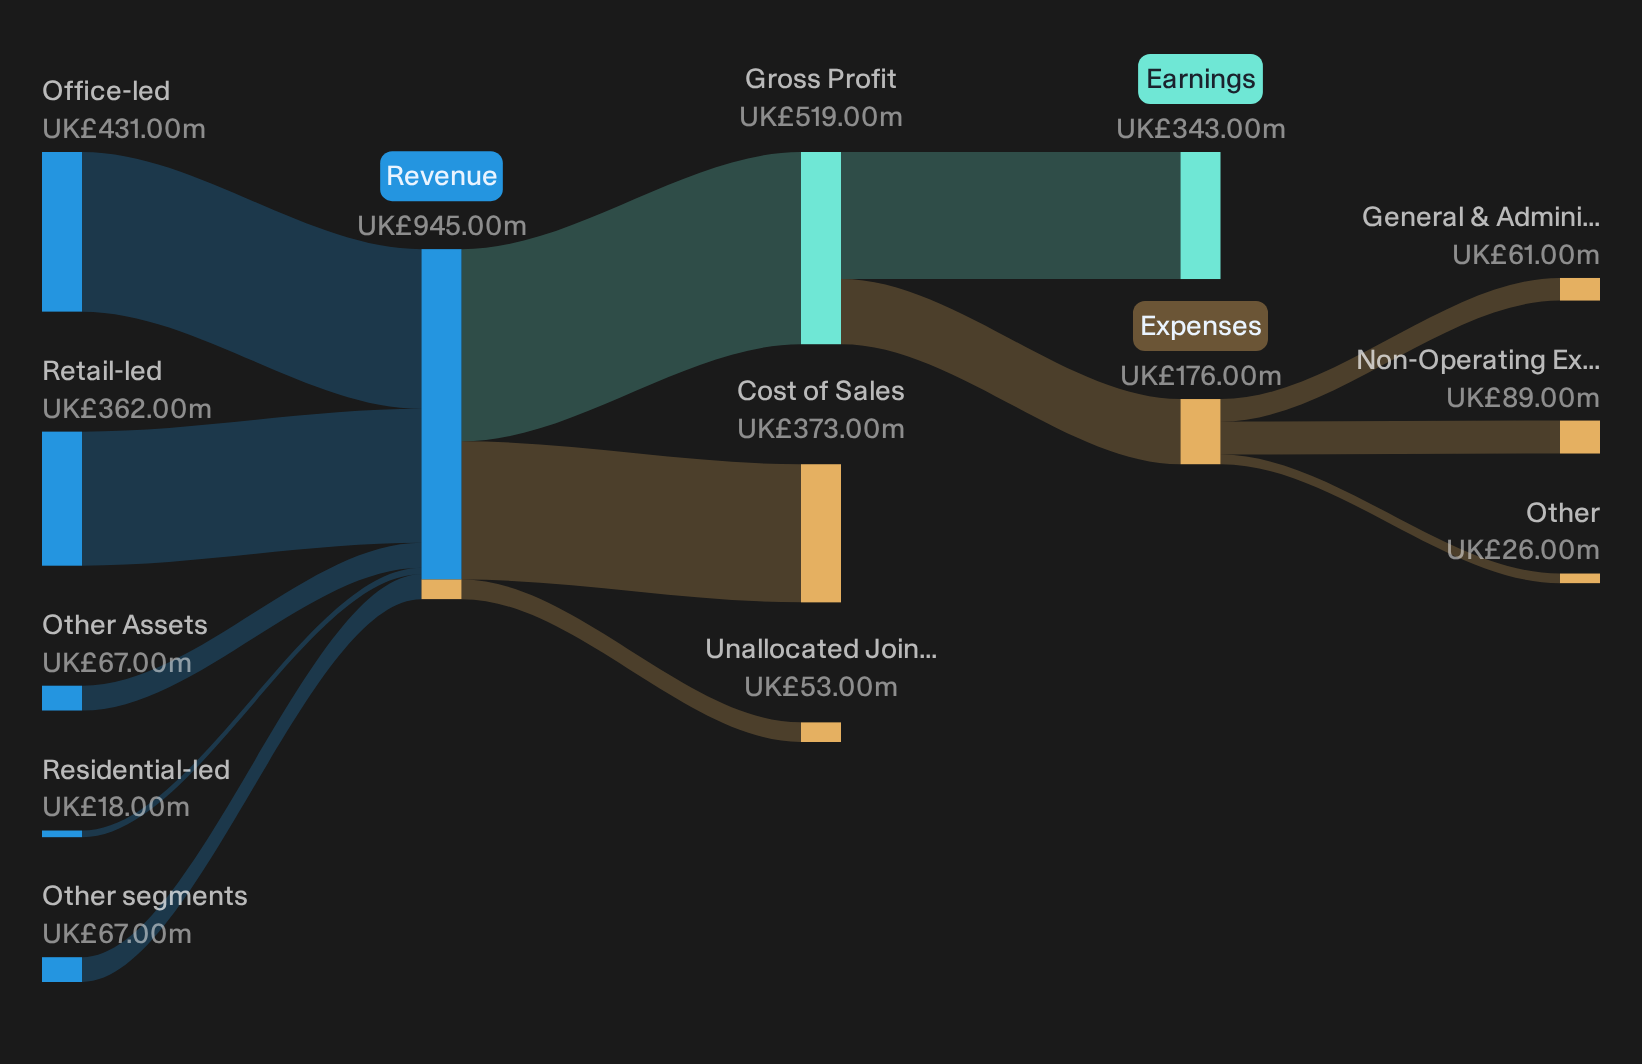
Operations: Land Securities Group earns about £431 million from office-led assets, £362 million from retail-led sites and £18 million from residential-led projects, all in the UK.
Market Cap: £4.6b
Land Securities Group gives you exposure to the same UK housing policy backdrop as pure residential REITs, but through a large commercial-led portfolio. Retail, offices and mixed-use schemes all feel the knock-on effects of Local Housing Allowance decisions.
"Landsec's strategic focus on acquiring prime real estate assets and investing in sustainable developments is expected to drive rental growth, particularly in the major retail sector, which should enhance future revenue streams."
What really matters now is how one pressure on its ability to convert that rental potential into lasting cash returns ultimately plays out.
If that pressure point matters to you, read the full narrative for Land Securities Group to see how Land Securities Group’s mixed-use engine could be accelerating or stalling under LHA shifts.
NewRiver REIT (LSE:NRR)
Overview: NewRiver REIT owns and manages UK community shopping centres and retail parks focused on everyday, essential spending, with some mixed-use and regeneration potential that links indirectly to residential resilience.
Operations: NewRiver REIT generates about £107.2 million from owned retail and £3.6 million from capital partnerships, with most income drawn from the UK.
Market Cap: £336 million
NewRiver REIT matters in this screener because its necessity-led retail assets sit close to the same low-income households affected by Local Housing Allowance decisions. Any shift in support can ripple into tenant health and rent security.
"Recovery in the U.K. retail sector, with resilient consumer spending, a broadly stable labor market and rising in store sales, is supporting higher occupier demand for NewRiver’s convenience focused assets and is expected to underpin sustained rental growth and higher revenue.
What investors really need to watch now is how one quiet funding-related pressure influences the staying power of that income story.
That pressure could be quietly reshaping how secure NewRiver REIT’s cash flows really feel, and the full narrative for NewRiver REIT shows what might be accelerating or masking that shift.

Seeking Alternatives Before Momentum Flies
Fresh ideas move first. Once momentum builds, prices can be flying while the best entry points are already gone. Check these under the radar picks while it matters and consider your options early.
- Explore potential income opportunities by scanning curated high yield candidates in the 1 dividend fortresses before the most attractive entry yields are identified by income-focused investors.
- Look for under the radar balance sheet strength using the list of solid balance sheet and fundamentals (11 results) so you can focus on businesses with numbers that still appear robust while others hesitate.
- Identify early-stage developments with the 38 profitable AI stocks that aren't just burning cash and review companies that are already generating earnings from AI before they move out of value territory.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com