
How Raised 2027 Outlook Will Impact Dollarama Stock Investors
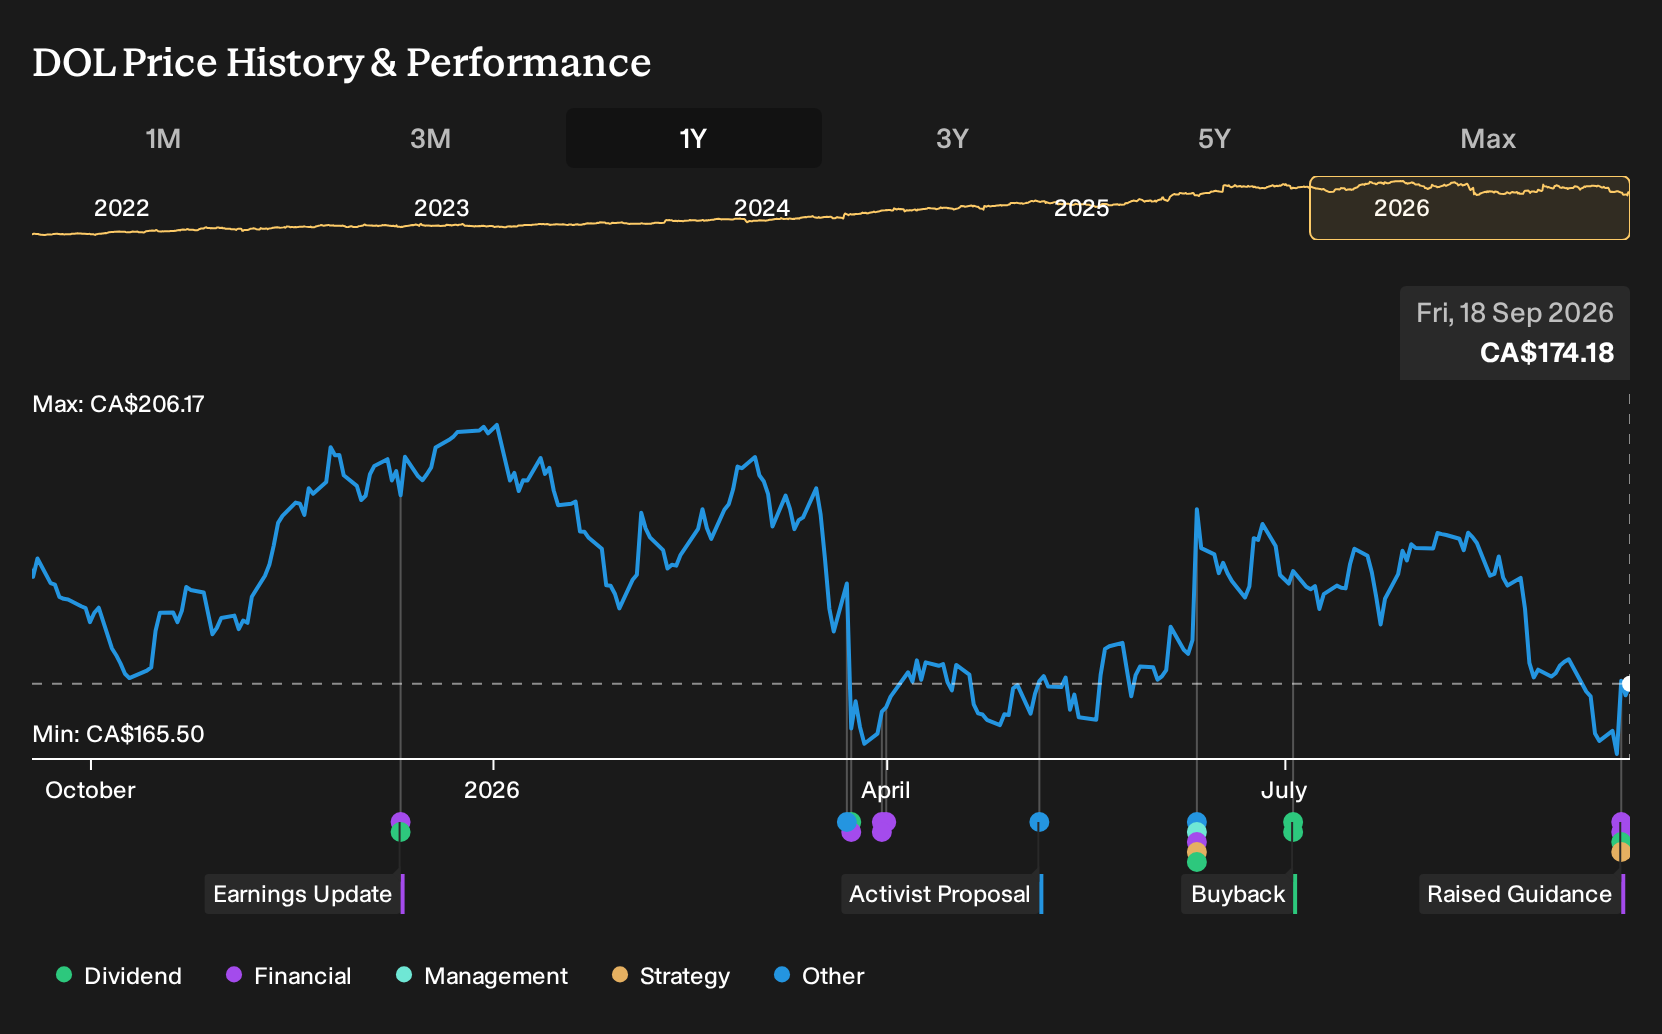
- Dollarama reported Q2 2026 sales of C$2,026.65 million and net income of C$349.32 million, raised fiscal 2027 same store sales guidance to 4% to 4.5%, lifted net new store openings guidance to 65 to 75, and affirmed a C$0.12 quarterly dividend payable in November 2026.
- The combination of stronger recent earnings, a higher outlook for Canadian comparable sales and store growth, and continued investment in Australia highlights how Dollarama is leaning on its established domestic engine while working through early stage international building costs.
- We will now look at how Dollarama's investment narrative could be affected by the raised fiscal 2027 same store sales guidance.
Scan how Dollarama’s upgraded guidance compares with other retailers that are pushing for resilient cash flow and store expansion through our hand-picked list of solid balance sheet and fundamentals (7 results).
Dollarama Investment Narrative Recap
To own Dollarama, you need to believe its Canadian discount format can keep drawing steady traffic while the newer Australian and Latin American operations mature. The raised fiscal 2027 same store sales guidance to 4% to 4.5% leans into that view and supports the idea that the core Canadian engine remains the key near term catalyst.
The biggest immediate risk sits outside Canada. Management expects a net loss from its Australian business in fiscal 2027 as transformation work continues, which could offset some of the upgraded Canadian outlook. If integration drags or costs stay elevated longer than planned, the stronger domestic performance may not translate cleanly into higher profitability.
The most relevant announcement here is the higher same store sales outlook for fiscal 2027, which directly connects to the Q2 result. Dollarama posted Q2 sales of C$2,026.65 million and net income of C$349.32 million, and Canadian comparable sales rose 5.4%, helped by consumables and general merchandise demand.
This guidance bump, alongside plans for 65 to 75 net new Canadian stores, keeps near term attention on execution in the home market while Australian operations run at a loss during their transformation. For you as a shareholder, the key question is whether the current Canadian strength can comfortably carry that investment phase without eroding overall returns.
What The Long Term Dollarama Forecasts Assume
Dollarama's narrative projects CA$9.1b revenue and CA$1.6b earnings by 2028. This rests on analysts assuming 10.9% yearly revenue growth and an earnings increase of about CA$300m from CA$1.3b today.
Uncover how Dollarama's fair value indicates a 21% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
For Dollarama, the alternate, more optimistic view hangs on store growth as a powerful long term catalyst. Before this guidance upgrade, the most bullish analysts were already penciling in revenue reaching about C$9.7b and earnings of roughly C$1.9b. Those projections did not factor in the fresh Q2 numbers or the higher 2027 sales outlook, so you may want to reassess how much those narratives could shift and compare several viewpoints before deciding what feels realistic to you.
Explore 6 other Dollarama fair value estimates, including one that suggests up to 33% potential increase from the current price.
Reach Your Own Conclusion
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Dollarama research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Dollarama. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Dollarama's overall financial health at a glance.
Looking for more Dollarama-sized investment ideas?
If Dollarama has sharpened your focus on business quality and staying power, widen the lens and use the Simply Wall St Screener to spot other opportunities that fit your style and risk comfort.
- If capital preservation and a steadier ride matter to you, start with a group of resilient businesses by checking out 8 resilient stocks with low risk scores.
- For investors who want quality at a reasonable entry point, scan a curated set of attractively priced companies through 4 high quality undervalued stocks.
- If you prefer backing under-the-radar stories before they gain wider attention, consider hunting through 9 high quality undiscovered gems.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com