
Accor (ENXTPA:AC), What Is Drawing Fresh Attention Now?
How Accor Stock Has Been Trading Recently
Accor (ENXTPA:AC) has been trading around €45.58, with the hotel operator showing a mixed return profile. The shares are flat over the past month and down over the past 3 months.
Short-term momentum for Accor looks softer, with the share price drifting lower over the past week and quarter. However, the 1-year total shareholder return of 13.65% and 5-year total shareholder return of 68.50% indicate that longer term holders have still been rewarded.
Scan how Accor compares with other consumer services businesses by checking a hand-picked shortlist of 179 high quality undervalued stocks that pair stronger balance sheets with more appealing valuations.
Bulls point to Accor’s solid multi year shareholder returns and improving earnings, while bears focus on the recent price drift. Which side does the current valuation actually support next?
Most Popular Narrative: 17.6% Undervalued
Accor is priced at €45.58 against a most-followed fair value estimate of €55.29, so the narrative sees meaningful upside built into the model and leans heavily on how the business is reshaping itself.
Accor's rapidly expanding pipeline, driven by strong signings in the U.S., Asia, and growth in Luxury & Lifestyle brands, positions the company to benefit from increased global travel demand, urbanization, and the growing global middle class, which is expected to support revenue and net unit growth. The scaling of the ALL loyalty program, with membership surpassing 100 million and an expanding portfolio of partnerships, is expected to deepen guest engagement, increase direct bookings, enable new revenue streams, and contribute to recurring fee income and margin expansion.
See why 6 investors see Accor as 18% undervalued.
Result: Fair Value of €55.29 (UNDERVALUED)
Still, the story around Accor can change quickly if foreign exchange swings continue to pressure reported earnings or if its heavy European footprint faces a sharper slowdown.
Find out about the key risks to this Accor narrative.
Another View On Accor’s Valuation
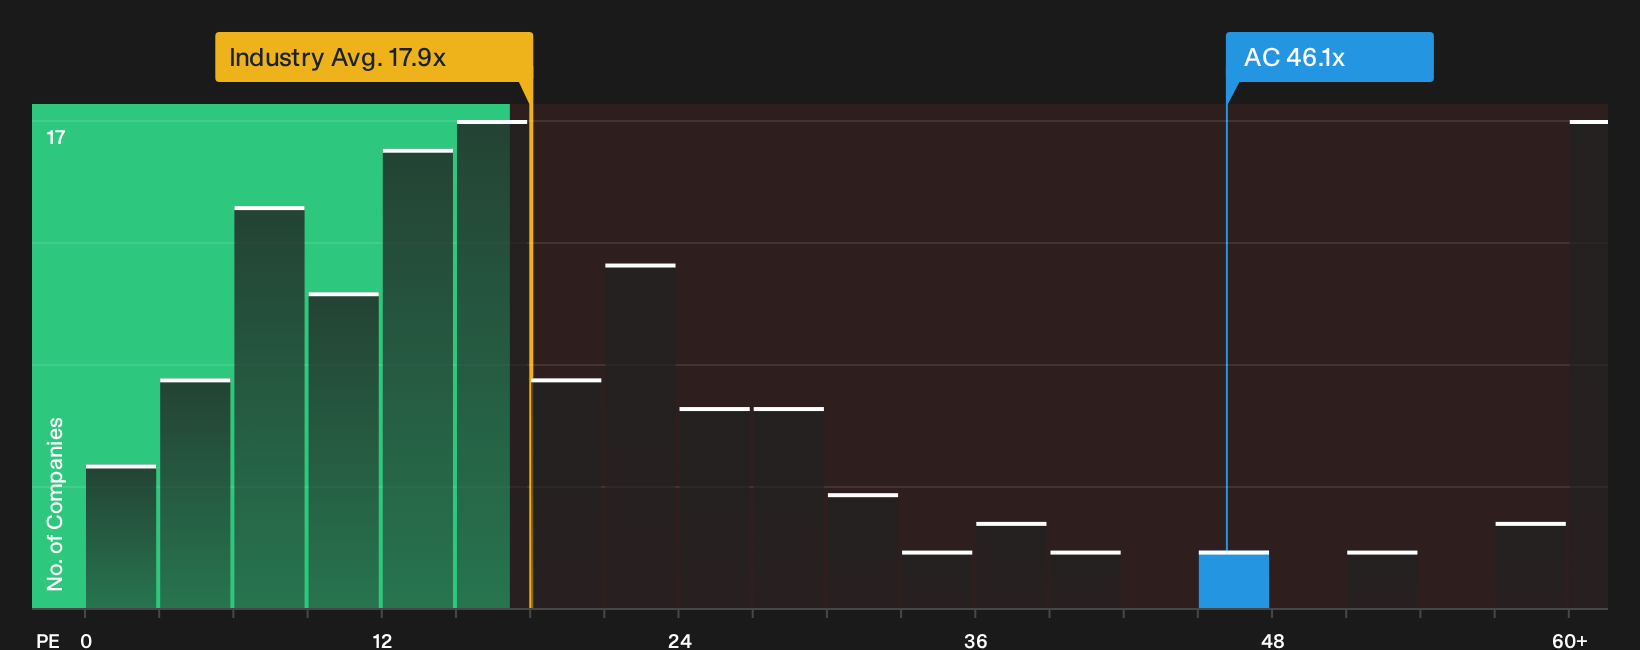
The first fair value story around Accor leans heavily on discounted cash flows and long term earnings power. A quick check of plain P/E math tells a very different story. The shares trade on 46.1x earnings, compared with 17.9x for the European hospitality group and 34.6x for peers. The fair ratio model points to 26.9x as a level the market could move towards. That gap loads more valuation risk onto the multiple, especially if growth or sentiment cool, so how much premium are you really comfortable paying for this stock?
Our valuation tools spell this out in more detail, breaking down how that rich P/E compares to both sector norms and the fair ratio the market could eventually gravitate toward. It is worth reviewing the full breakdown before leaning too hard on the DCF story See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Accor so far, right, with valuation tension, solid long term returns and real risks in the background, so move fast, scan the full picture and weigh both sides using our breakdown of 3 key rewards and 4 important warning signs
Looking for more Accor investment ideas?
Accor is only one opportunity on your radar, so broaden your edge and survey other stock ideas before fresh moves in the market leave you reacting late.
- Target potential value rebounds by scanning a focused shortlist of 131 elite penny stocks with strong financials that pair higher risk with the possibility of outsized share price moves.
- Prioritise quality at a discount by reviewing a curated group of 612 high quality undiscovered gems that combine solid fundamentals with under-the-radar profiles.
- Dial down portfolio stress by checking 227 resilient stocks with low risk scores that score well on financial strength and business stability when conditions turn rough.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com