
Learn Why The Bull Case For Otis Worldwide Stock Could Change Following CEO Retirement Plan
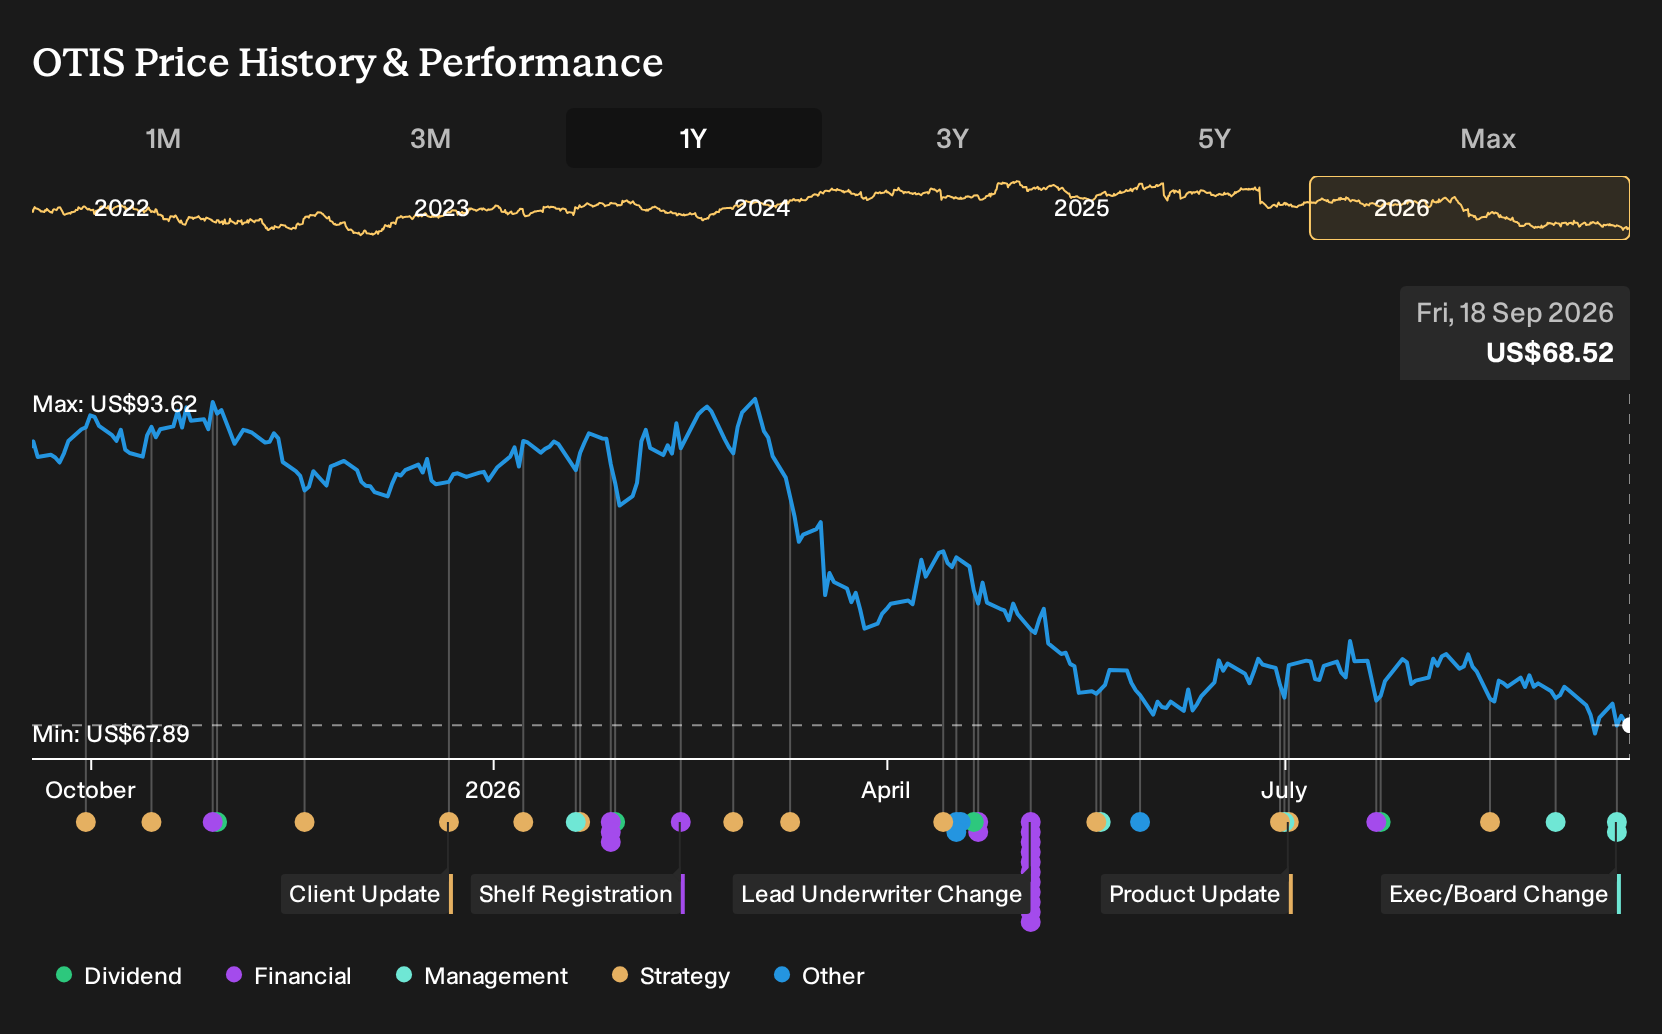
- Otis Worldwide disclosed that long-serving Chair, President and CEO Judy Marks plans to retire after her successor is appointed, with a search under way and a transition period running through July 31, 2027.
- Under Marks, Otis Worldwide focused heavily on its higher margin Service business and capital returns, including US$3.4b in dividends and US$5b in buybacks. This frames investor attention on how a new leader might treat cash allocation and the service portfolio.
- We will now look at how Otis Worldwide's investment narrative could shift as Judy Marks hands over leadership to a successor.
Compare how Otis Worldwide's leadership transition stacks up against peers by scanning companies with resilient balance sheets and disciplined cash use in our 30 resilient stocks with low risk scores.
Otis Worldwide Investment Narrative Recap
To own Otis Worldwide, you need to believe the service and modernization engine can keep offsetting softer new equipment demand, especially where office and China exposure weigh on orders. Management already leans on a large installed base and recurring maintenance to support cash generation, which stays central regardless of who is in the corner office.
The CEO transition looks structured enough that it does not obviously change the near term catalyst, which is execution on modernization backlogs and service pricing. The biggest operational risk still sits in weaker new equipment markets and any pressure on high margin service contracts if competitors or new technologies win share.
The leadership change announcement matters because Judy Marks has been closely tied to the service heavy model, cost programs such as UpLift, and the focus on modernization. Otis Worldwide now needs a successor who can run those same playbooks in markets where organic revenue growth and EPS have recently lagged peers.
Investors are already watching whether modest revenue forecasts and high debt levels are manageable given planned cost savings and prior capital returns. The handover process, with Marks advising through July 2027, gives the board time to choose a CEO who can keep modernization execution on track while addressing slower growth risks in China and commercial real estate.
Otis Worldwide Analyst Expectations Through the Transition
Otis Worldwide's current analyst narrative assumes that revenues reach US$17.3b and earnings come in at US$2.0b by 2029. That profile is built on 5.1% yearly revenue growth and an earnings increase of about US$0.5b from roughly US$1.5b today.
Uncover how Otis Worldwide's fair value indicates a 30% potential upside to its current price, before the discount starts to narrow.
Exploring Other Perspectives
For Otis Worldwide, the most cautious analysts focus on modernization delays as a key risk. They were already modeling slower progress, with revenues around US$16.9b and earnings near US$1.9b by 2029, before this CEO news. That is a more muted story than consensus, and these views may shift as leadership plans become clearer.
Explore 5 other Otis Worldwide fair value estimates, including one that suggests up to 5% downside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Otis Worldwide research is our analysis highlighting 5 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Otis Worldwide. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Otis Worldwide's overall financial health at a glance.
Looking for more Otis Worldwide style investment ideas?
Once you have a view on Otis Worldwide, it can help to scan a wider watchlist so you are not relying on a single story for future returns.
- If you want a starting point for potentially steadier performers, consider companies highlighted in our 30 resilient stocks with low risk scores that focus on resilience and capital discipline.
- For investors hunting for mispriced opportunities, the 33 high quality undervalued stocks can surface businesses where fundamentals differ from what the market is currently pricing in.
- If income is front of mind, you can look at stocks in the 6 dividend fortresses that pair higher yields with an emphasis on sustainability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com