
Will Rapid Cell Banking Change Charles River Stock Narrative
- Charles River Laboratories International recently introduced rapid cell banking programs that combine rapid microbiological methods with CGMP-compliant Next-Generation Sequencing to shorten cell bank timelines and support quality, safety, and regulatory readiness for biologics and advanced therapies.
- The new platform, strengthened by the Pathoquest acquisition and by Charles River’s Alternative Methods Advancement Project focus, tightens end-to-end biologics capabilities while supporting a shift toward in vitro and reduced animal testing in preclinical and quality control work.
- We will now look at how this accelerated, NGS-enabled cell banking platform could reshape Charles River’s broader investment narrative.
Charles River Laboratories International Investment Narrative Recap
To own Charles River Laboratories International, you need to believe its mix of discovery services, research models, and manufacturing solutions can convert a strong R&D pipeline into steadier earnings over time. The rapid cell banking launch supports that view by leaning into higher value biologics work and in vitro tools, which may help offset softer demand in traditional preclinical studies.
In the near term, the key swing factor remains how quickly underlying biopharma spending stabilizes relative to cancellations and a book to bill previously below 1x. The biggest risk is still execution and pricing pressure as Charles River integrates new platforms, manages higher debt, and contends with lower cost CRO competitors.
The rapid cell banking programs, built on CGMP compliant NGS and the Pathoquest acquisition, appear most relevant for near term catalysts. They expand Charles River Laboratories International’s ability to support complex biologics and advanced therapies, which ties directly into higher margin service lines and the push toward new approach methodologies and reduced animal use.
The same announcement also speaks to regulatory positioning and operational speed, since the platform is aligned with FDA, EMA, and ICH guidance and targets an estimated 40% reduction in cell bank timelines. For investors, execution on adoption, pricing, and capacity utilization across this platform will be important signals for how Charles River converts recent share price moves into more durable fundamentals.
Charles River Laboratories International's narrative projects US$4.4b revenue and US$535.6 million earnings by 2029. This assumes 2.9% yearly revenue growth and an earnings increase of about US$774 million from a loss of US$238.5 million today.
Uncover why Charles River Laboratories International's fair value is consistent with its current price.
Exploring Other Perspectives
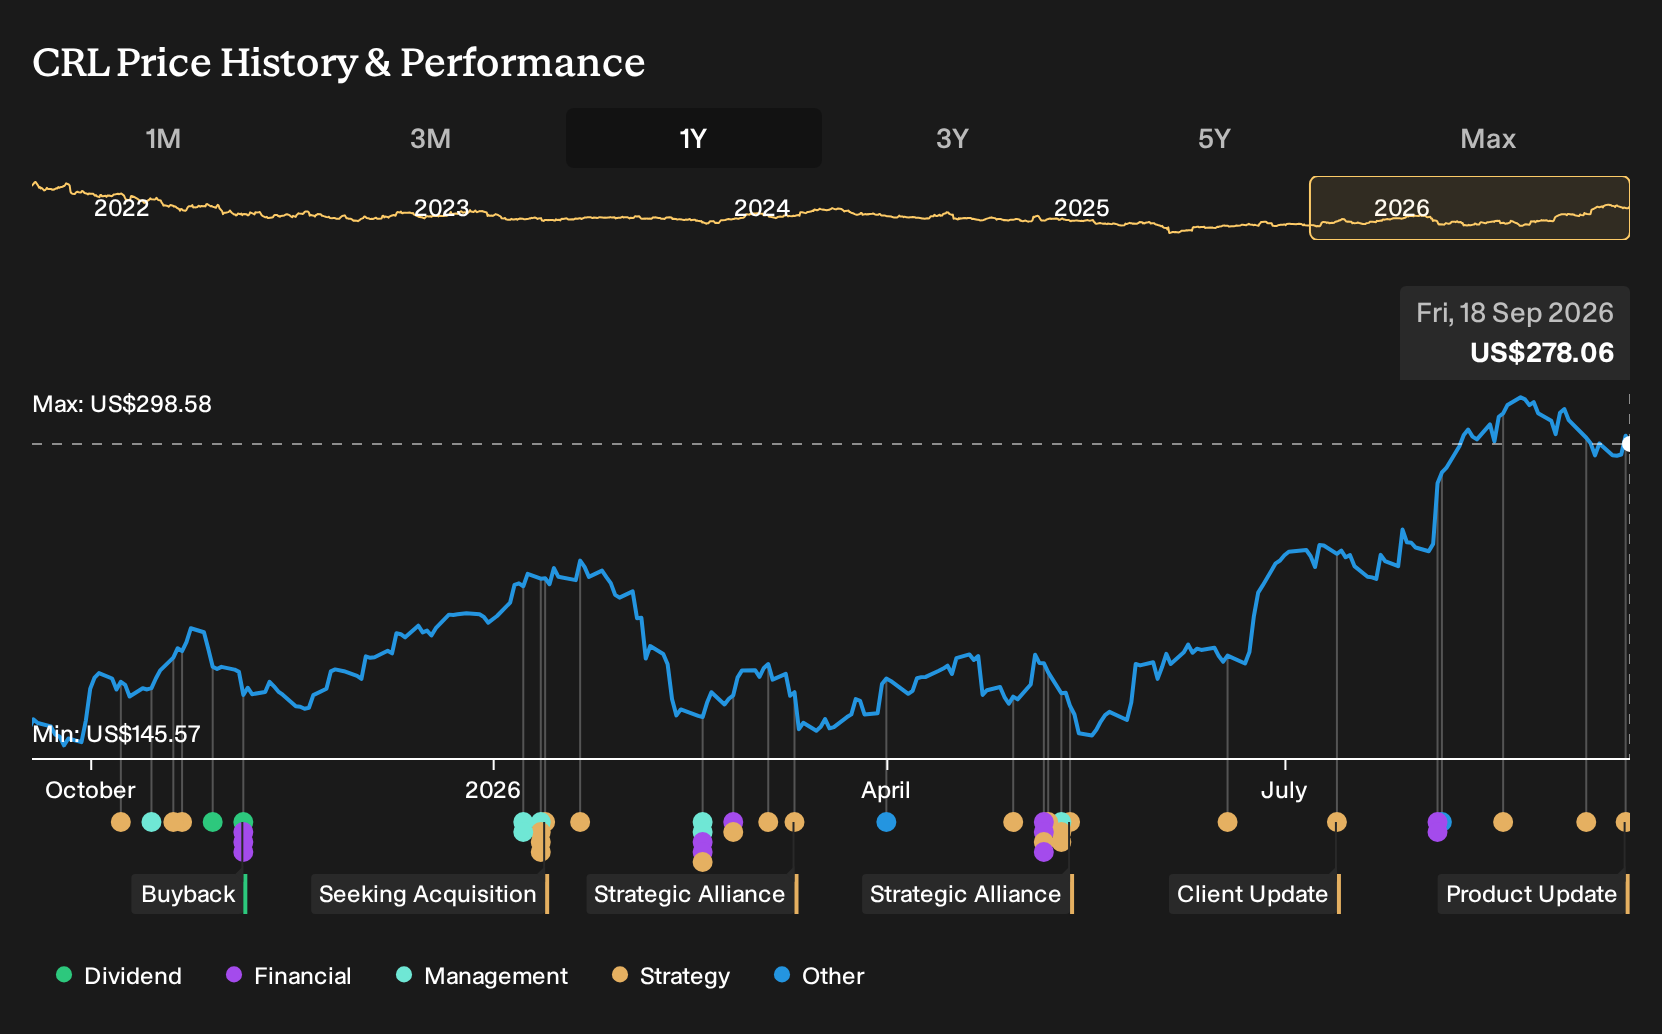
Some of the most optimistic analysts think the real catalyst for Charles River Laboratories International is not rapid cell banking itself, but how quickly clients adopt New Approach Methods around it. Before this news, the bullish camp was modeling roughly 3.2% annual revenue growth and about US$762.1 million in 2029 earnings. That is far above the US$535.6 million consensus view. You should expect those narratives to evolve as this new platform gets digested. Use the spread in forecasts as a reminder that reasonable investors can read the same data very differently.
Explore 3 other Charles River Laboratories International fair value estimates, including one that suggests as much as 14% upside from the current price.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Charles River Laboratories International research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Charles River Laboratories International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Charles River Laboratories International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Charles River Laboratories International?
If the Charles River Laboratories International story has you thinking about portfolio upgrades, it can help to scan a wider field of quality candidates using the Simply Wall St Screener.
- For investors hunting for mispriced quality, start with a curated pool of 33 high quality undervalued stocks that combine fundamentals with a margin of safety.
- If capital preservation is a priority, focus on balance sheet strength by filtering for a list of solid balance sheet and fundamentals (23 results) that can better withstand business setbacks.
- Income focused investors can zero in on cash flow support by reviewing a tailored set of 6 dividend fortresses that aim to pair high yields with resilience.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com