
Brookfield Infrastructure Partners (BIP) Could Be 23% Undervalued After Its Recent Pullback
Brookfield Infrastructure Partners (NYSE:BIP) has drawn fresh attention after a 38.5% total return over three years, which has raised questions about whether its long-lived asset model adequately supports the current unit price.
In the shorter term, the 1 month share price return is down 8.5% and the 3 month share price return is down 4%, while the year to date share price return is 5.2% and the 1 year total shareholder return is 22.3%. This indicates that momentum for Brookfield Infrastructure Partners has cooled after a stronger run, which puts more focus on whether the current US$36.07 quote is justified by its earnings power and perceived risk.
Compare Brookfield Infrastructure Partners with a curated 33 high quality undervalued stocks list that currently shows stronger value signals based on cash flow strength and balance sheet quality.
The recent pullback at Brookfield Infrastructure Partners could either be the market reassessing its infrastructure earnings or simply sentiment cooling after strong multi year returns. The valuation work starts by separating those two stories.
Most Popular Narrative: 23% Undervalued
Brookfield Infrastructure Partners is trading at $36.07 against a widely followed fair value estimate of $46.82, which frames the current pullback as a potential valuation gap rather than a finished story.
The exponential growth in AI-driven data consumption and digital infrastructure requirements, especially in the U.S. and Europe, is fueling record demand for data centers, fiber networks, and digital connectivity. BIP's ongoing and planned investments in these fast-growing, high-utilization assets are expected to drive significant revenue and earnings growth.
See why 35 investors see Brookfield Infrastructure Partners as 23% undervalued.
Result: Fair Value of $46.82 (UNDERVALUED)
Still, Brookfield Infrastructure Partners faces real pressure points, including the risk of overpaying in competitive acquisitions and higher leverage if large deals and refinancing costs stack up.
Find out about the key risks to this Brookfield Infrastructure Partners narrative.
Another View: Brookfield Infrastructure Partners Looks Expensive On Earnings
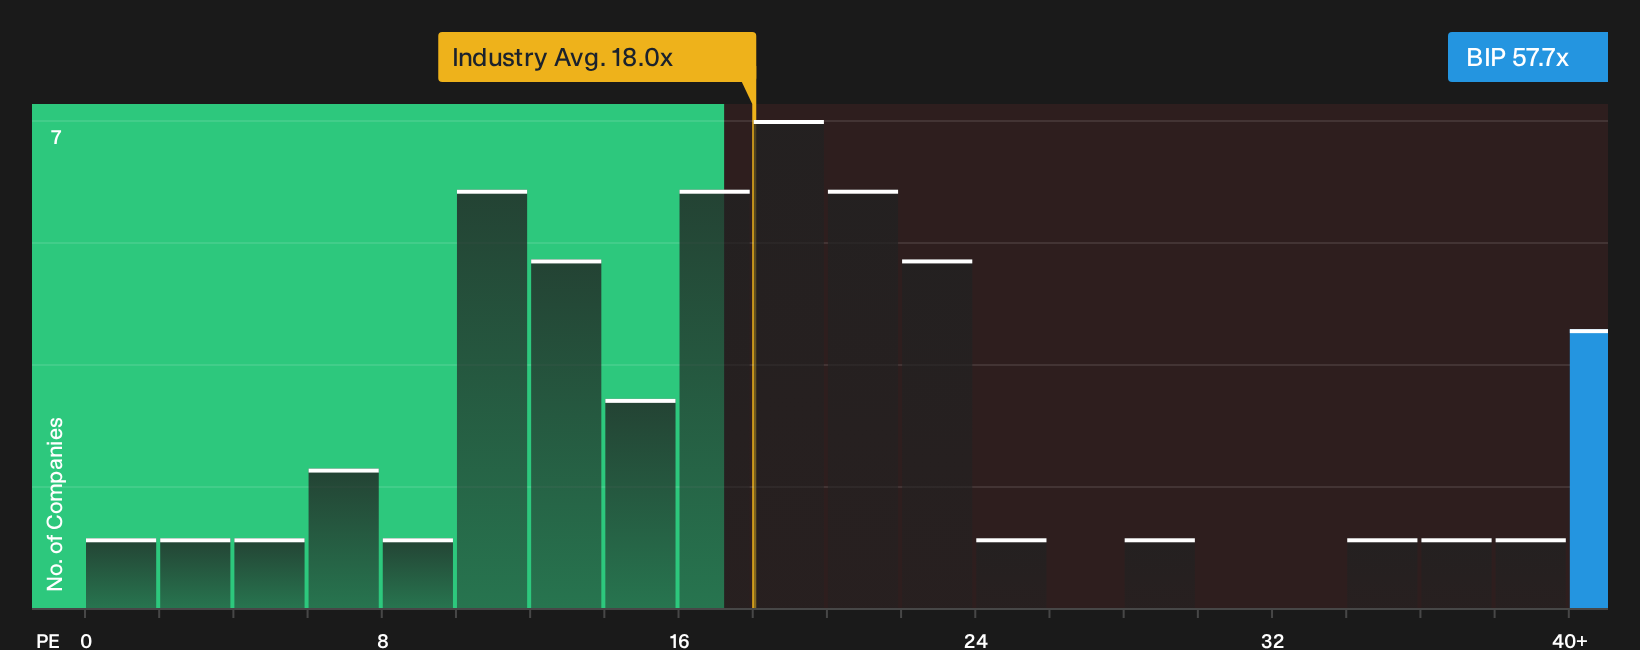
There is a catch. On a simple P/E lens, Brookfield Infrastructure Partners trades at 57.7x earnings, while peers in the Global Integrated Utilities group sit around 18.2x and its own fair ratio is 2.4x. That gap points to real valuation risk if sentiment or assumptions shift.
For a closer look at how that P/E gap could matter to your thesis, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Brookfield Infrastructure Partners so far. If you want to move fast and think independently, consider the full picture yourself by looking at 3 key rewards and 3 important warning signs.
Looking for more investment ideas beyond Brookfield Infrastructure Partners?
If Brookfield Infrastructure Partners has sharpened your thinking, do not stop here. Broaden your watchlist with a few targeted ideas that could sharpen your next move.
- Spot potential value opportunities early by scanning a focused 16 high quality undiscovered gems that highlights companies with strong fundamentals the broader market may be overlooking.
- Prioritise resilience and sleep better at night by using a curated 30 resilient stocks with low risk scores to surface businesses with lower risk scores and steadier profiles.
- Strengthen your core holdings by reviewing a list of solid balance sheet and fundamentals (23 results) that filters for healthier leverage, liquidity and financial durability.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com