
Can Central Bancompany (CBC) Justify Its Valuation As Strong Results Fuel Buybacks?
Why Central Bancompany’s Latest Quarter Matters For Investors
Central Bancompany (CBC) kicked off August with second quarter results that outperformed both the prior quarter and last year, paired with a fresh $100 million buyback and its usual quarterly dividend.
Central Bancompany’s share price has climbed 33.54% year to date and delivered a 69.81% total shareholder return over the past year, while the recent 12.82% 90 day share price return suggests that momentum has been building into these stronger quarterly results and capital return moves.
Scan how other regional banks are handling capital returns and deposit growth by reviewing the list of solid balance sheet and fundamentals (23 results) alongside Central Bancompany’s latest buyback and dividend moves.
That kind of move in Central Bancompany raises a simple tension. Are investors finally catching up with how the business is performing, or has sentiment raced ahead of what the current fundamentals justify?
Most Popular Narrative: 8% Undervalued
Central Bancompany last closed at $31.85, while the most followed narrative pegs fair value at $34.80 using a 7.24% discount rate and detailed cash flow and earnings assumptions anchored on analyst forecasts.
Roughly US$1.8b, or US$7.50 per share, of excess capital and a long history of 47 acquisitions give the company room to pursue accretive M&A or other capital actions, which could affect earnings growth and return on equity if deployed prudently.
See why 1 investors see Central Bancompany as 8% undervalued.
Result: Fair Value of $34.80 (UNDERVALUED)
Still, Central Bancompany’s story can shift quickly if the planned expansion into St. Louis and Denver drags on efficiency, or if Missouri public deposit flows prove less reliable.
Find out about the key risks to this Central Bancompany narrative.
Another View On Central Bancompany’s Valuation
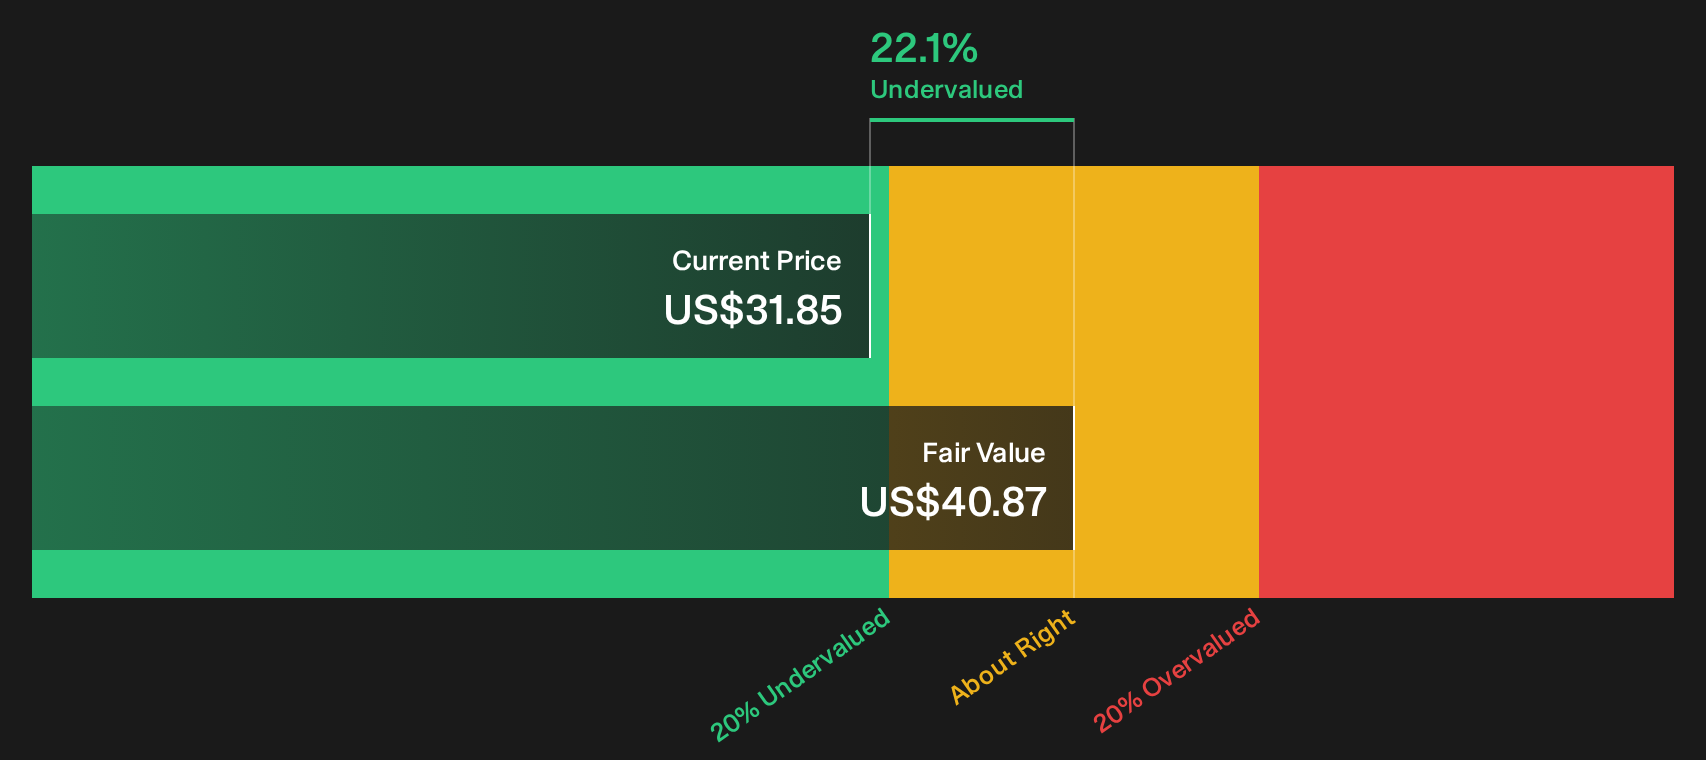
Central Bancompany screens as good value on the SWS DCF model, with the current $31.85 share price compared against an estimated future cash flow value of $40.87. That gap points to an undervalued reading. Yet P/E based comparisons flag the stock as expensive. Which lens do you trust more?
Look into how the SWS DCF model arrives at its fair value.
Next Steps
If this mix of confidence and concern around Central Bancompany feels familiar, treat it as a prompt to move quickly and test the numbers yourself. Then weigh both the cautious signals and the upbeat factors in the 3 key rewards and 1 important warning sign.
Looking for more investment ideas beyond Central Bancompany?
Do not stop with Central Bancompany. Put this research to work by lining up a few more targeted watchlist candidates that fit your risk and income preferences.
- Target resilient balance sheets and stronger fundamentals by reviewing the list of solid balance sheet and fundamentals (23 results) for ideas that could better handle tougher conditions.
- Hunt for potential value opportunities by scanning the 33 high quality undervalued stocks and see which businesses currently trade below their assessed worth.
- Build a cash flow focused watchlist by checking the 6 dividend fortresses for companies pairing higher yields with more robust underlying metrics.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com