
Should Gas Processing Upgrade Require Action From Cheniere Energy Stock Investors?
- BASF Catalysts LLC reported that Cheniere Energy has commissioned Durasorb LNG MAX technology across multiple liquefaction trains at its Corpus Christi LNG facility in Texas, with full deployment at the site targeted by the end of 2027.
- This rollout gives Cheniere Energy a single-unit process to remove heavy hydrocarbons, BTEX and water to cryogenic specifications, aiming to cut freeze related outages and keep LNG production schedules more predictable.
- We will now look at how Cheniere Energy's upgraded gas purification capability could influence the broader investment narrative around its LNG platform.
Scan beyond Cheniere Energy and see how other LNG and gas infrastructure plays stack up on reliability and balance sheet strength with our hand picked 30 resilient stocks with low risk scores.
Cheniere Energy Investment Narrative Recap
To own Cheniere Energy, you need to believe its LNG platform can keep high utilization through global supply swings and shifting energy policies while funding large projects with a balance sheet that already carries meaningful debt. The Durasorb rollout fits that view by targeting fewer freeze related outages and tighter control of gas quality at Corpus Christi.
The key near term swing factor is execution on capacity additions such as the midscale Corpus Christi trains and related debottlenecking. Durasorb looks more like an incremental support to uptime rather than a game changing catalyst. The bigger risk still sits with global LNG oversupply, contract pressure and capital intensive expansion plans.
The Durasorb LNG MAX deployment at Corpus Christi lines up tightly with Cheniere Energy's broader push to squeeze more reliable output from existing facilities through debottlenecking and process optimization. Management is pursuing roughly 1 mtpa of extra capacity without entirely new large builds, so technology that condenses dehydration and contaminant removal into a single unit directly serves that goal.
This announcement also connects back to the expansion of Corpus Christi midscale trains 8 and 9, where higher run time and fewer process interruptions can be important for economics when new capacity comes on line in a market facing rising LNG supply. Execution risk remains, particularly with high capex and debt, but smoother operations give Cheniere more room to manage pricing and contract risk if spot markets soften.
Cheniere Energy's current earnings sit at US$1.5b, with analysts projecting US$24.5b in revenue and US$3.0b in earnings by 2029, based on an assumed 5.6% yearly revenue growth rate. That implies an earnings increase of US$1.5b from today's level to reach the consensus forecast.
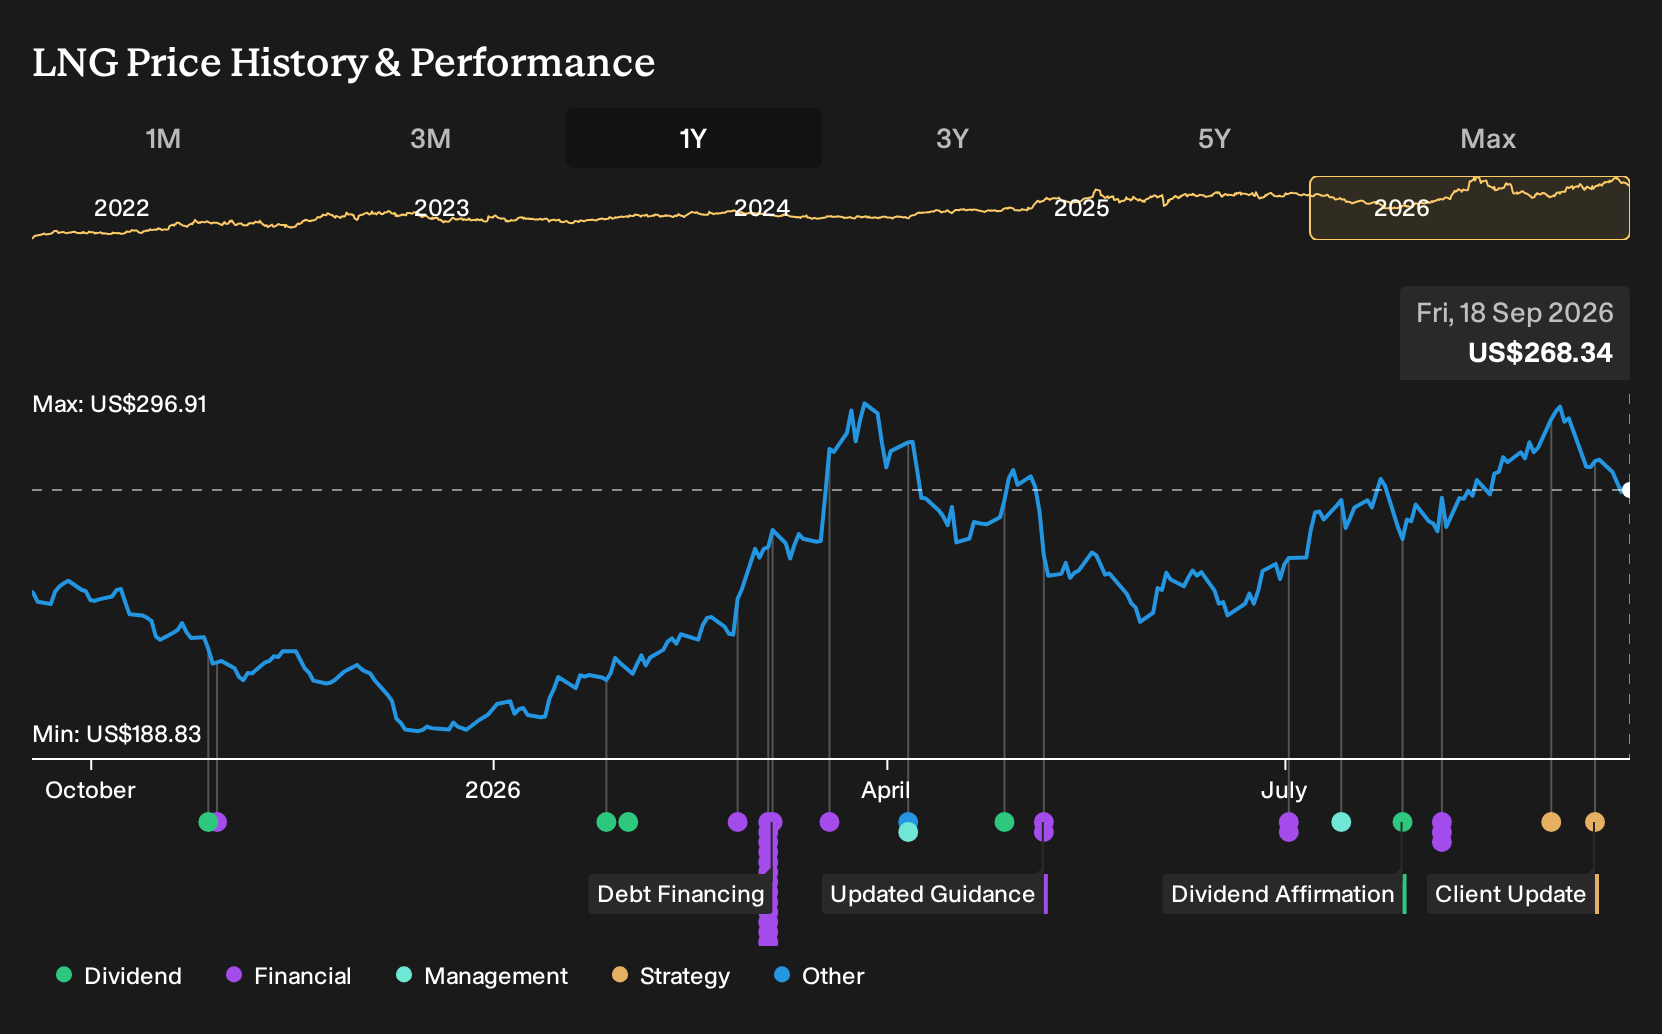
Uncover why Cheniere Energy's fair value indicates a 13% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Five fair value estimates from the Simply Wall St Community span roughly US$129 to US$321 per share, which shows how far opinions on Cheniere Energy can stretch. Some users lean on expansion projects and Durasorb backed reliability as upside catalysts, while others focus on LNG oversupply and contract risk. Use that spread to test your own thesis.
Explore 4 other Cheniere Energy fair value estimates, including one that suggests as much as 52% downside from the current price.
The Verdict Is Yours
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider conducting your own research.
- A great starting point for your Cheniere Energy research is our analysis highlighting 1 key reward and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Cheniere Energy. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Cheniere Energy's overall financial health at a glance.
Looking For More Cheniere Energy Sized Ideas?
Once you have an initial view on Cheniere Energy, it can help to compare it with other opportunities that share similar qualities or offer something completely different for your portfolio. The Simply Wall St Screener lets you do that in a structured way without needing to build your own filters from scratch.
- If you want steadier balance sheets in focus, start with a list of solid balance sheet and fundamentals (23 results) that can handle swings in cash flow and funding conditions.
- For investors hunting for value opportunities, scan through 33 high quality undervalued stocks that pair solid fundamentals with pricing that may not fully reflect them.
- Those who care most about capital preservation and smoother rides might prefer 30 resilient stocks with low risk scores that screen well on resilience and risk controls.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com