
PCCW (SEHK:8) Draws Fresh Valuation Focus, Is The Modest Upside Enough?
PCCW (SEHK:8) is back in focus after recent trading left the share price at HK$5.30, with total return over the past year rising 6.6% and the past 3 years showing a very large gain.
Short term, PCCW’s share price has drifted lower, with the 7 day return down 2.1% and the year to date share price return down 4.3%. However, the 1 year and 3 year total shareholder returns of 6.6% and roughly 84.7% point to momentum that has been built over a longer stretch.
Scan beyond PCCW’s recent 3 year surge and line it up against other potential movers in a hand picked list of 612 high quality undiscovered gems, which also pair strong fundamentals with under the radar momentum.
PCCW now trades at HK$5.30 while analyst and intrinsic estimates point higher, which raises a simple issue: How far does fair value sit from today’s price after this multi year surge?
Most Popular Narrative: 9% Undervalued
PCCW’s most followed valuation story puts fair value at HK$5.80, a touch above the HK$5.30 last close. This leaves a modest gap that depends on how much weight you give to its media and connectivity growth plans versus current losses.
Accelerated enterprise demand for digital transformation, high-speed fiber, and 5G mobile services, driven by remote/hybrid work and business modernization across Asia, has already fueled 4% growth in HKT's revenues and is likely to drive further top-line revenue and margin improvement as digital infrastructure adoption deepens.
See why 2 investors see PCCW as 9% undervalued.
Result: Fair Value of HK$5.80 (UNDERVALUED)
Still, the PCCW story can change quickly if competition in OTT streaming squeezes Viu harder than expected, or if high infrastructure spending continues to pressure free cash flow.
Find out about the key risks to this PCCW narrative.
Another View on PCCW Using Sales-Based Valuation
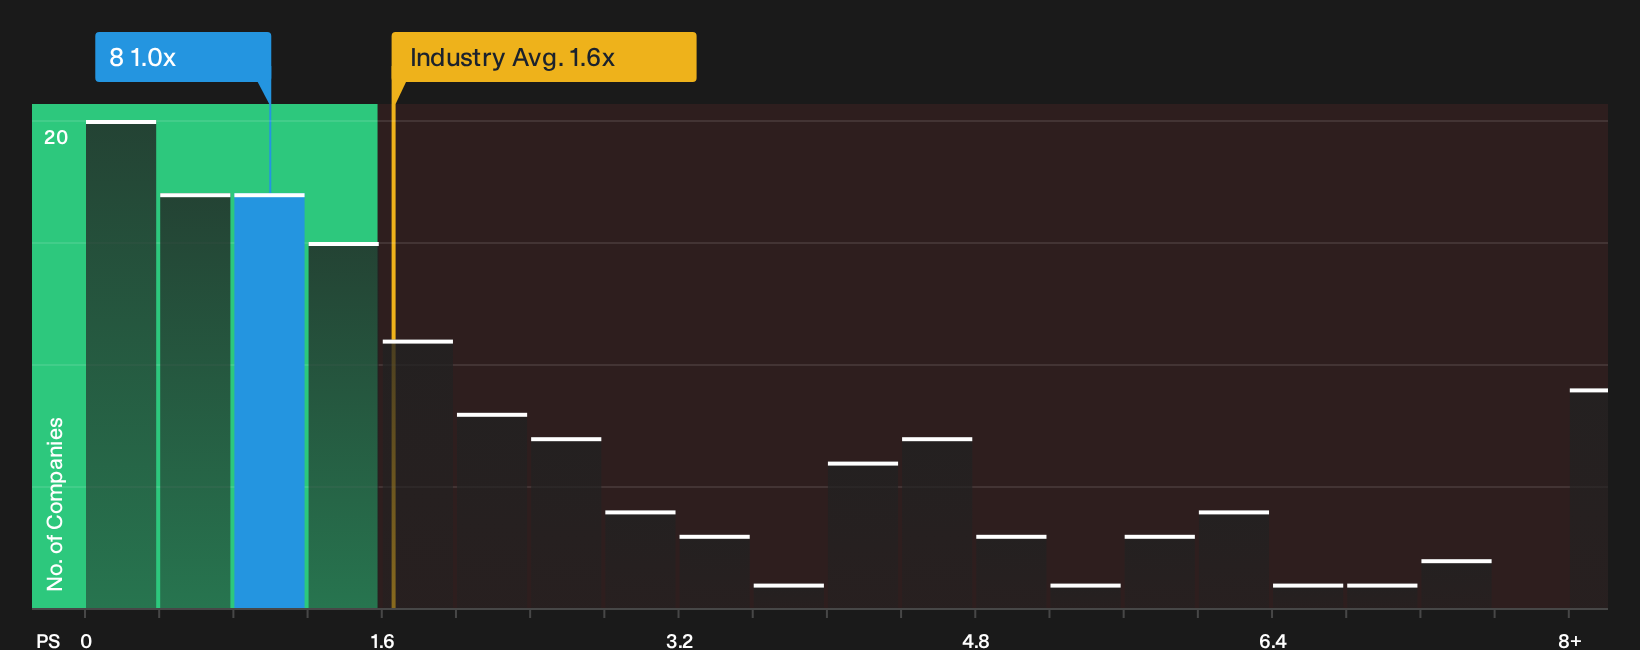
There is a twist when shifting from fair value estimates to a simple sales multiple. PCCW trades on a P/S ratio of 1x, while the fair ratio implied by the SWS model is 0.8x. That gap points to valuation risk if sentiment cools.
To see how that sales-based view lines up with other checks on PCCW, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around PCCW are clear, with both concerns and bright spots identified. Act while the facts are fresh and weigh the 2 key rewards and 2 important warning signs.
Looking for more PCCW sized investment ideas?
If PCCW has you thinking more carefully about value and risk, do not stop here. The real edge comes from comparing it with other clear, data driven ideas.
- Target dependable cash flow and steadier ride potential by hunting for resilient candidates in the 227 resilient stocks with low risk scores.
- Zero in on companies where strong balance sheets back up the story, starting with a focused list of solid balance sheet and fundamentals (197 results).
- Spot opportunities that the crowd has not fully noticed yet by scanning the 131 elite penny stocks with strong financials before momentum catches up.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com