
FormFactor (FORM) Could Be 15% Undervalued As AI Testing Demand Drives The Debate
FormFactor (FORM) has been drawing attention after recent share price swings, with the stock closing at $118.38. Investors are weighing how the company’s probe card and systems business aligns with its current valuation.
Recent trading has been choppy for FormFactor, with the latest 6.14% 1 day share price gain and 2.98% 7 day share price return coming after a 90 day share price decline of 20.84%. At the same time, the 1 year total shareholder return of 236.02% and 3 year total shareholder return of 256.35% indicate momentum that has been strong over a longer stretch.
Scan how FormFactor’s sharp move fits into the wider chip-testing story by comparing it with 89 AI infrastructure stocks that are riding the same demand for advanced semiconductor equipment.
FormFactor’s sharp pullback over 90 days sits against a multi year surge and a fresh pop back toward US$120. Does that recent path still leave enough potential upside to outweigh the risks at today’s valuation?
Most Popular Narrative: 15% Undervalued
FormFactor’s most followed valuation story pegs fair value at about $138.63, which sits above the latest $118.38 close and frames the recent volatility as a debate about how much future AI related demand is already reflected in the price.
Accelerating adoption of generative AI, high-performance computing, and HBM DRAM in data centers is driving substantial increases in test complexity and intensity. FormFactor's differentiated probe cards and early leadership in HBM4 chiplet testing position the company to benefit from higher ASPs and revenue growth as these markets scale. (Impacts: Revenue, potential margin improvement)
See why 15 investors see FormFactor as 15% undervalued.
Result: Fair Value of $138.63 (UNDERVALUED)
Still, the bullish FormFactor narrative leans heavily on analyst forecasts and on the assumption that trade and customer concentration risks do not derail those targets.
Find out about the key risks to this FormFactor narrative.
Another View: What FormFactor’s P/E Is Telling You
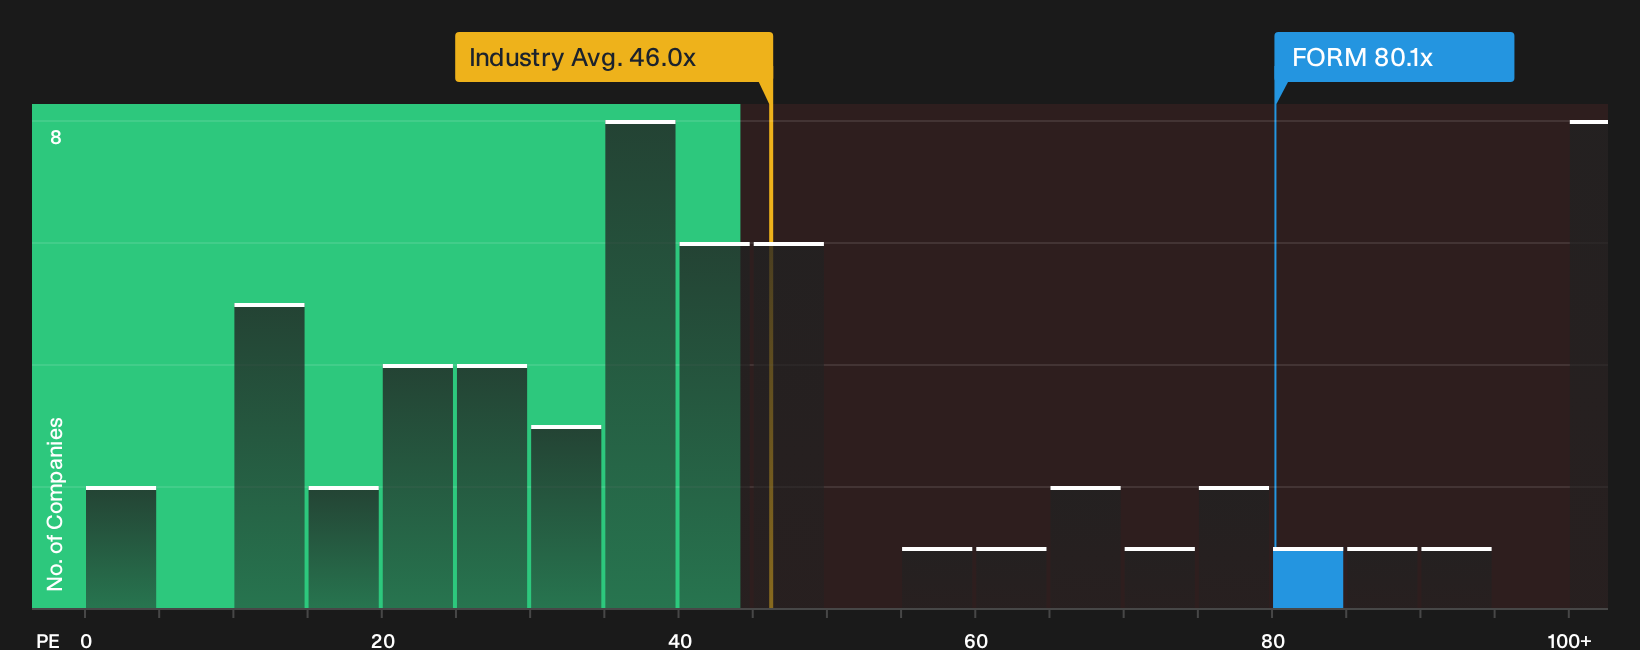
FormFactor might look appealing against a $138.63 fair value line, yet the current P/E of 80.1x sits well above both the 47x US Semiconductor industry average and the 46.3x fair ratio that the market could move toward. If sentiment cools, how much compression risk are you really comfortable with at this price?
For investors who prefer to weigh this against a detailed multiples breakdown rather than a single headline number, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on FormFactor’s valuation story so far. Act quickly, stress test the numbers yourself, and weigh the 3 key rewards and 2 important warning signs.
Looking for more FormFactor sized investment ideas?
If FormFactor has your attention, do not stop here. Use the same structured thinking to uncover fresh candidates that fit your return and risk preferences.
- Target quality at a discount and scan a curated 33 high quality undervalued stocks that applies consistent fundamental checks before a stock ever hits your watchlist.
- Build steadier income potential and review a focused 6 dividend fortresses that concentrates on higher yielding companies with payout histories you can actually analyze.
- Dial down portfolio stress and work through a refined 30 resilient stocks with low risk scores that filters for resilient balance sheets and lower risk profiles across the market.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com