
3 British Dividend Stocks With Yields Over 5%
Central banks are lifting interest rates again, which has pushed up bond yields and reminded investors that cash and fixed income now compete harder for attention. Reliable dividend payers that already yield more than 3% suddenly look very interesting, especially if those payouts are well covered and steadily rising. This article breaks down three UK dividend powerhouses from that screen that could help anchor a long term income portfolio.
The three stocks below are just a sample from this idea. The full screen surfaced 64 more high-yield companies with equally compelling income stories that are not covered here.
If you want to go deeper into this dividend theme, head straight to the Dividend Powerhouses (3%+ Yield) screener to filter, analyze, and identify the income plays that best fit your goals.
MONY Group (LSE:MONY)
MONY Group runs a suite of UK consumer websites that help households compare insurance, money, home services and travel deals, with its Insurance arm providing the steady, cash-rich activity that underpins its place in a screen focused on robust dividend payers.
MONY Group generates £236.9 million from Insurance, £110.5 million from Money, £54.8 million from Home Services and £49.3 million from Cashback, with smaller segment adjustments, all in the UK, and carries a market value of around £990 million.
For income investors, MONY Group is interesting because its comparison and lead-generation platform is built on recurring, fee-based activity that can support regular cash returns if that engine keeps running efficiently.
"The ongoing investment in digital and AI-enabled platforms is increasing automation and operational efficiency. This is evidenced by a 300% improvement in tech productivity and cost reductions from replatforming, which is likely to support sustainable long-term expansion of net margins."
What really matters now is how one quiet pressure on the business model shapes the gap between those higher margins and future dividend headroom.
If that pressure on the model matters to you, read the full narrative for MONY Group to see how MONY Group’s efficiency drive could reshape its income story and risk profile.

Foresight Group Holdings (LSE:FSG)
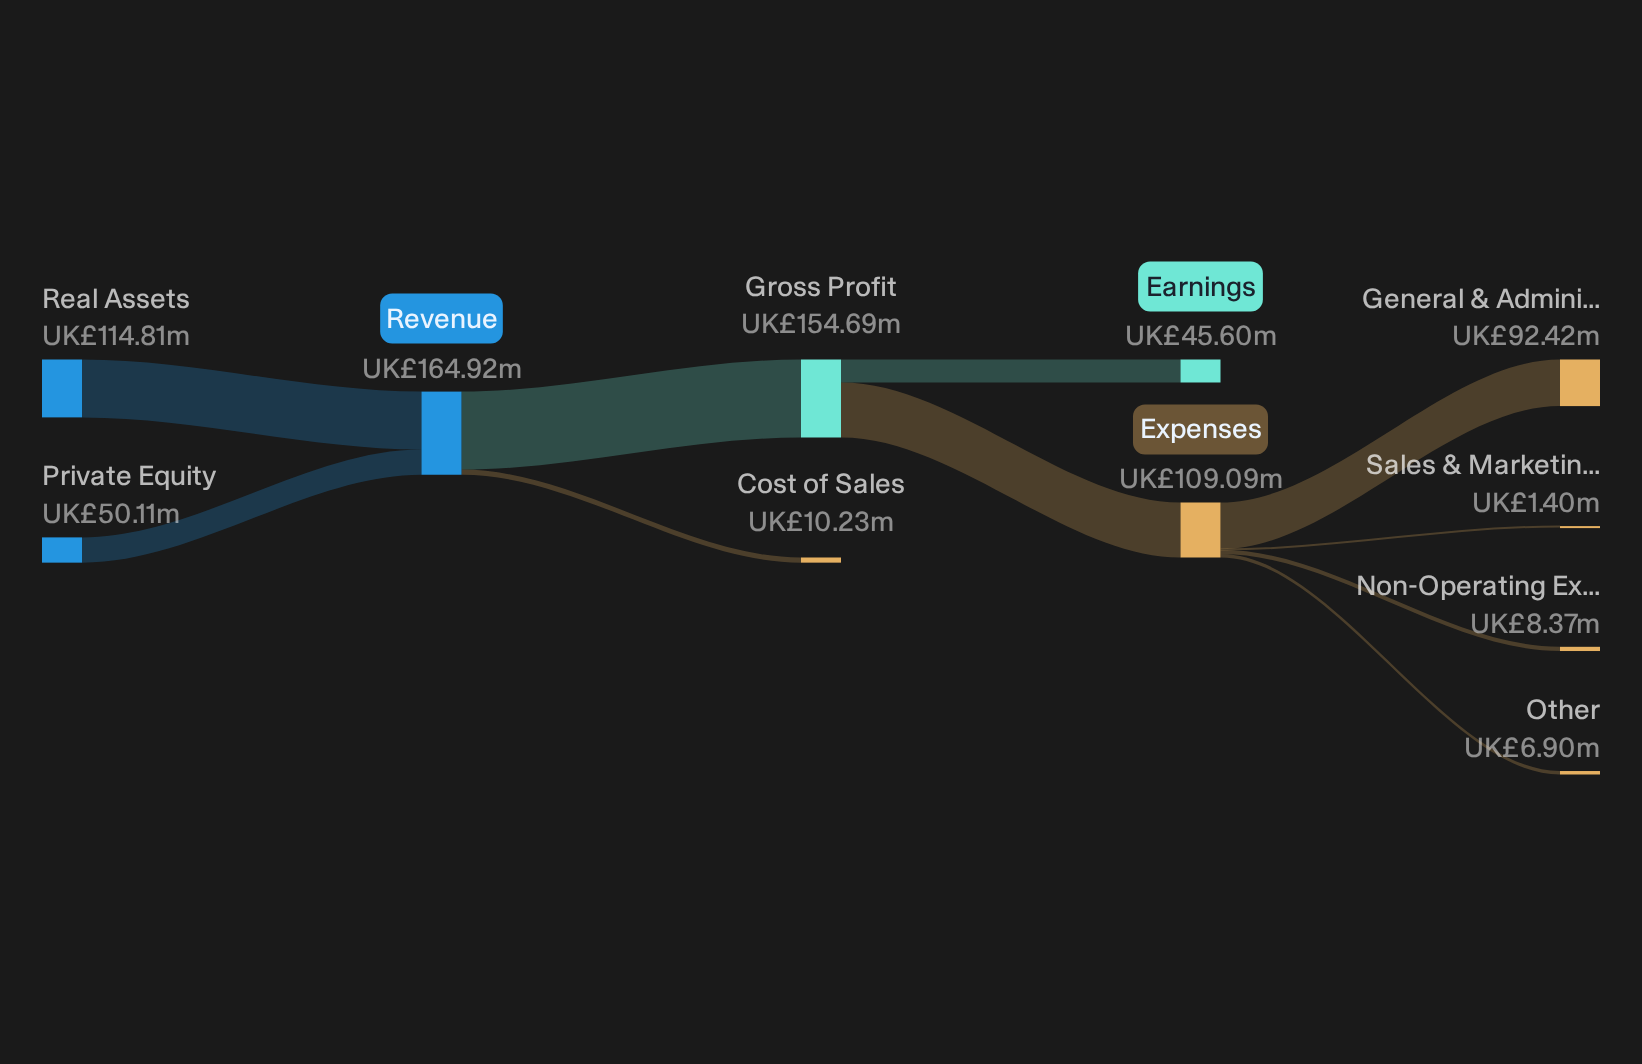
Foresight Group Holdings is focused on channeling long-term capital into income-focused infrastructure and smaller private businesses, with its £114.8 million Real Assets arm managing renewable energy and other cash-generative projects, £50.1 million from Private Equity mandates, and a market value around £488 million.
For income-focused investors, Foresight Group Holdings matters because a large slice of its Real Assets business is tied to renewable and regulated infrastructure funds that are built to distribute steady cash flows. This directly feeds into the kind of covered, resilient yield this dividend screen is seeking.
"Foresight is rapidly evolving new product strategies such as standalone private credit-focused business relief, with early demand signaling the potential to become a flagship offering, accessing sizeable, untapped wealth and institutional flows and elevating recurring revenue growth rates as financial advisors and pension funds shift allocations for long-term yield."
The real test for Foresight Group Holdings is how one quiet shift in where those long-term capital flows land ultimately affects dividend headroom.
As that capital mix quietly shifts, read the full narrative for Foresight Group Holdings to see how Foresight Group Holdings could turn evolving flows into long term income opportunities.
NWF Group (AIM:NWF)
NWF Group links the dividend powerhouse theme directly to its Fuels operation, where recurring cash from heating and road fuel distribution helps cover payouts while Food logistics and Feeds manufacturing add extra income streams.
NWF Group generates £645.8 million from Fuels, £193 million from Feeds and £90.7 million from Food, after £9.2 million of inter segment offsets, and has a market value of about £77 million.
NWF Group gives you a higher starting yield with coverage rooted in that fuels cash engine. This is exactly what this screen looks for when it flags income ideas that feel built to last rather than flash in the pan.
"Although the rollout of the regional Fuels operating model is improving miles per drop and price per liter, the complexity of consolidating 30 depots into 9 hubs could dilute the efficiency gains and limit the anticipated uplift in operating margins and earnings."
What really shapes how that generous yield evolves is whether one quiet strain on future margins stays contained or starts to bite harder.
If that strain on margins is what you are weighing, read the full narrative for NWF Group to see how NWF Group’s fuel engine could keep funding resilient dividends.

Seeking Fresh Alternatives For Your Income?
Some of the most interesting opportunities move from quiet to crowded quickly. Scan fresh dividend, quality and niche themes before momentum is fully caught by the crowd and act now.
- Spot cash-rich leaders with low debt profiles by running the list of solid balance sheet and fundamentals (11 results) while information is still under the radar for now and pricing has not fully reacted.
- Target high-yield candidates built around robust cash generation through the 1 dividend fortresses before payout momentum attracts broader income hunters and yields start dropping.
- Hunt for resilient performers with muted volatility using the 4 resilient stocks with low risk scores and position ahead of risk-averse capital that may chase the same defensive qualities.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com