
Corcept Therapeutics (CORT) Dropped, So What Is Behind The Latest Attention?
Corcept Therapeutics (CORT) is back in focus after regulators in Europe moved its lead oncology asset a step closer to potential approval for platinum-resistant ovarian cancer, following supportive late-stage clinical data.
Short term, the share price has cooled, with Corcept Therapeutics down 3.98% over the last session and 8.89% over 30 days. However, a 38.02% 90 day share price return and 188.72% year to date share price gain sit alongside a 5 year total shareholder return of 443.57%, indicating strong longer term momentum despite recent consolidation.
Capitalize on Corcept Therapeutics' regulatory momentum by scanning a curated list of oncology focused opportunities across 37 healthcare AI stocks.Corcept Therapeutics now trades at a sizeable discount to both intrinsic value estimates and analyst targets after that sharp run and recent pullback. Is the market sensibly cautious, or is it mispricing the oncology and cortisol pipeline story?
Most Popular Narrative: 22% Undervalued
On the most followed view, Corcept Therapeutics carries a fair value estimate of $141 against a last close of $110.29, which puts the spotlight on how much of the oncology and cortisol pipeline story is already baked into that gap.
The publication of the CATALYST study and the resulting increased awareness and screening for hypercortisolism among physicians are expanding the potential addressable patient pool, which is expected to drive significant acceleration in revenue growth over the next several years. Anticipated regulatory approvals for relacorilant in both hypercortisolism and platinum-resistant ovarian cancer, supported by clinically differentiated safety and efficacy data, create major new revenue and margin expansion opportunities as the company moves past single-product dependence.
See why 60 investors see Corcept Therapeutics as 22% undervalued.
Result: Fair Value of $141 (UNDERVALUED)
Still, Corcept Therapeutics carries real risk from Korlym concentration and patent litigation. Faster generic pressure or adverse rulings could quickly challenge the undervaluation case.
Find out about the key risks to this Corcept Therapeutics narrative.
Another View: Corcept Therapeutics Through a Sales Multiple Lens
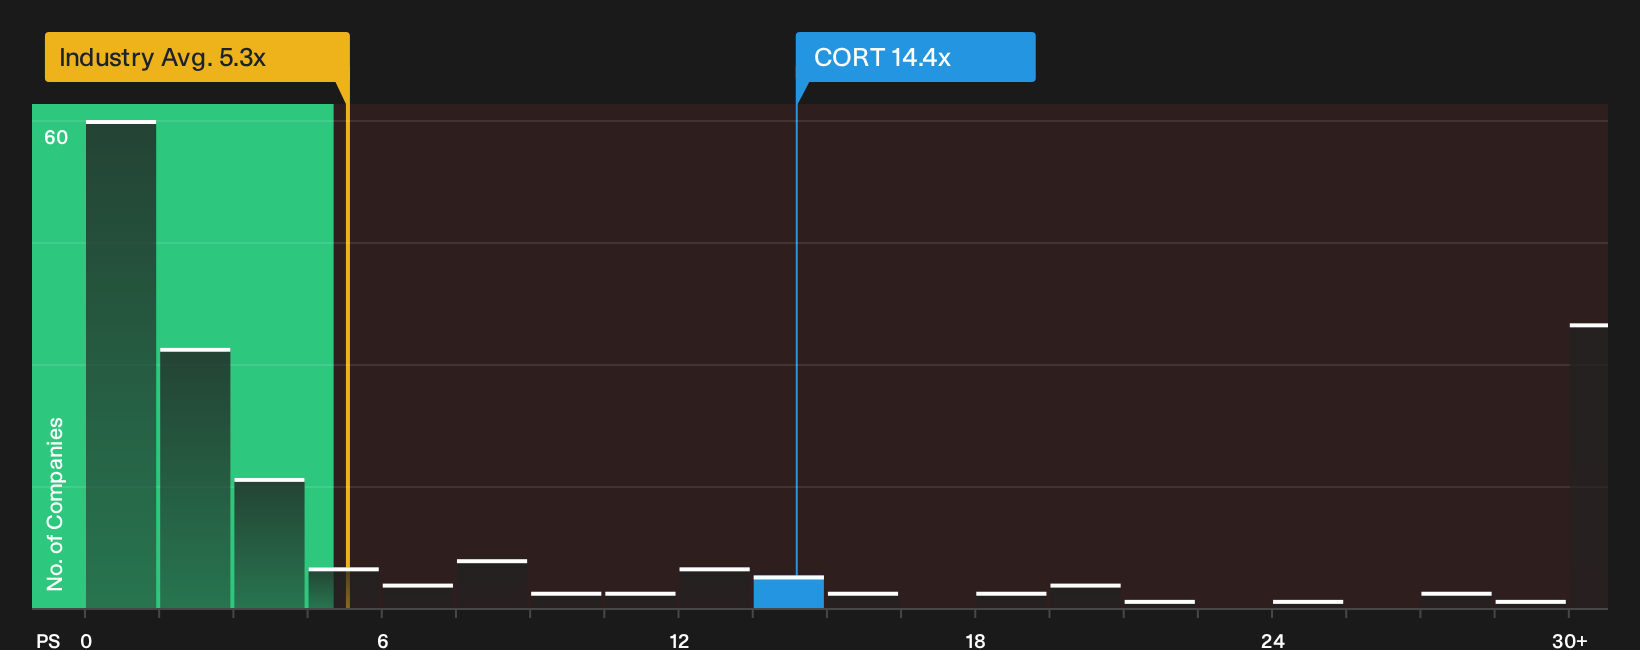
On a simple sales multiple, Corcept Therapeutics looks expensive at a P/S of 14.4x compared with 5.3x for the wider US pharmaceuticals group and 9.8x for peers. Yet the fair ratio sits higher at 16.5x, which suggests the market could still move toward richer pricing if growth unfolds as expected. Does that gap represent valuation risk if sentiment cools, or room for the stock to re rate if execution holds up?
To see how this sales based view fits with the rest of the numbers, take a look at the See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Corcept Therapeutics can be useful if you act before the crowd settles on a single story. Review the numbers, weigh the oncology and cortisol pipeline, and pressure test the 2 key rewards and 2 important warning signs.
Looking For More Investment Ideas Beyond Corcept Therapeutics?
If you like the Corcept Therapeutics story but want a broader watchlist, use the screener to spot fresh ideas before most investors catch on.
- Target dependable cash generators by scanning a 6 dividend fortresses that can help anchor your portfolio when sentiment swings.
- Hunt for mispriced opportunities through a focused 16 high quality undiscovered gems list that most investors are not watching yet.
- Prioritize staying power by zeroing in on a list of solid balance sheet and fundamentals (23 results) that can better withstand setbacks and funding stress.
This article by Simply Wall St is general in nature. We provide commentary based on historical data and analyst forecasts only using an unbiased methodology and our articles are not intended to be financial advice. It does not constitute a recommendation to buy or sell any stock, and does not take account of your objectives, or your financial situation. We aim to bring you long-term focused analysis driven by fundamental data. Note that our analysis may not factor in the latest price-sensitive company announcements or qualitative material. Simply Wall St has no position in any stocks mentioned.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com